


EN
Lionsgate Studios (LION) Faces A 40% Overvalued View On Quarterly Results
Lionsgate Studios (LION) just reported second quarter sales of US$668.8 million and a sharply reduced net loss, giving investors new data to reassess the stock.
The share price reaction has been muted in the very short term, with a 1-day share price return showing a 1.26% decline and a 7-day share price return showing a 2.26% decline, even after Lionsgate Studios announced stronger quarterly results and new partnerships. Over a longer stretch, momentum has been firmer, with a 30-day share price return of 10.66% and a year-to-date share price gain of 35.05%, while total shareholder return over the past year sits at 78.66%, indicating that investors have been re-rating the stock as execution and content output evolve.
Spot opportunities around Lionsgate Studios by scanning a curated list of 21 high quality undiscovered gems with fundamentals that may not yet be fully reflected in their share prices.Lionsgate Studios is clearly getting more attention after stronger quarterly results and fresh partnerships, but a sharp share price gain is already in the rear-view mirror. Is the stock’s current valuation still leaving enough on the table for new investors?
Most Popular Narrative: 40% Overvalued
The most followed narrative pegs Lionsgate Studios at a fair value of $9.00, well below the recent $12.56 close. This frames current pricing as already baking in a lot of execution success and offering limited margin for error.
The numbers on debt, recent share price gains of roughly 105 to 150% over 12 months, and at least one estimate that the stock is about 16.6% above fundamentals together imply that Lionsgate Studios' current valuation already prices in strong execution and leaves limited room for disappointment.
See why 2 investors see Lionsgate Studios as 40% overvalued.
Result: Fair Value of $9.00 (OVERVALUED)
Still, if Lionsgate Studios keeps converting its US$1.5b to US$1.6b backlog cleanly and further trims leverage around 4.3x, this cautious narrative could weaken.
Find out about the key risks to this Lionsgate Studios narrative.
Another View: Lionsgate Studios Through A Cash Flow Lens
The bearish narrative anchors on a $9.00 fair value, yet Simply Wall St's DCF model points in a different direction. At $12.56, Lionsgate Studios trades about 6% below the model's estimated future cash flow value of $13.37. That hints at a modest cushion instead of a 40% air pocket, so which story feels closer to how you see the next few years playing out?
Look into how the SWS DCF model arrives at its fair value.
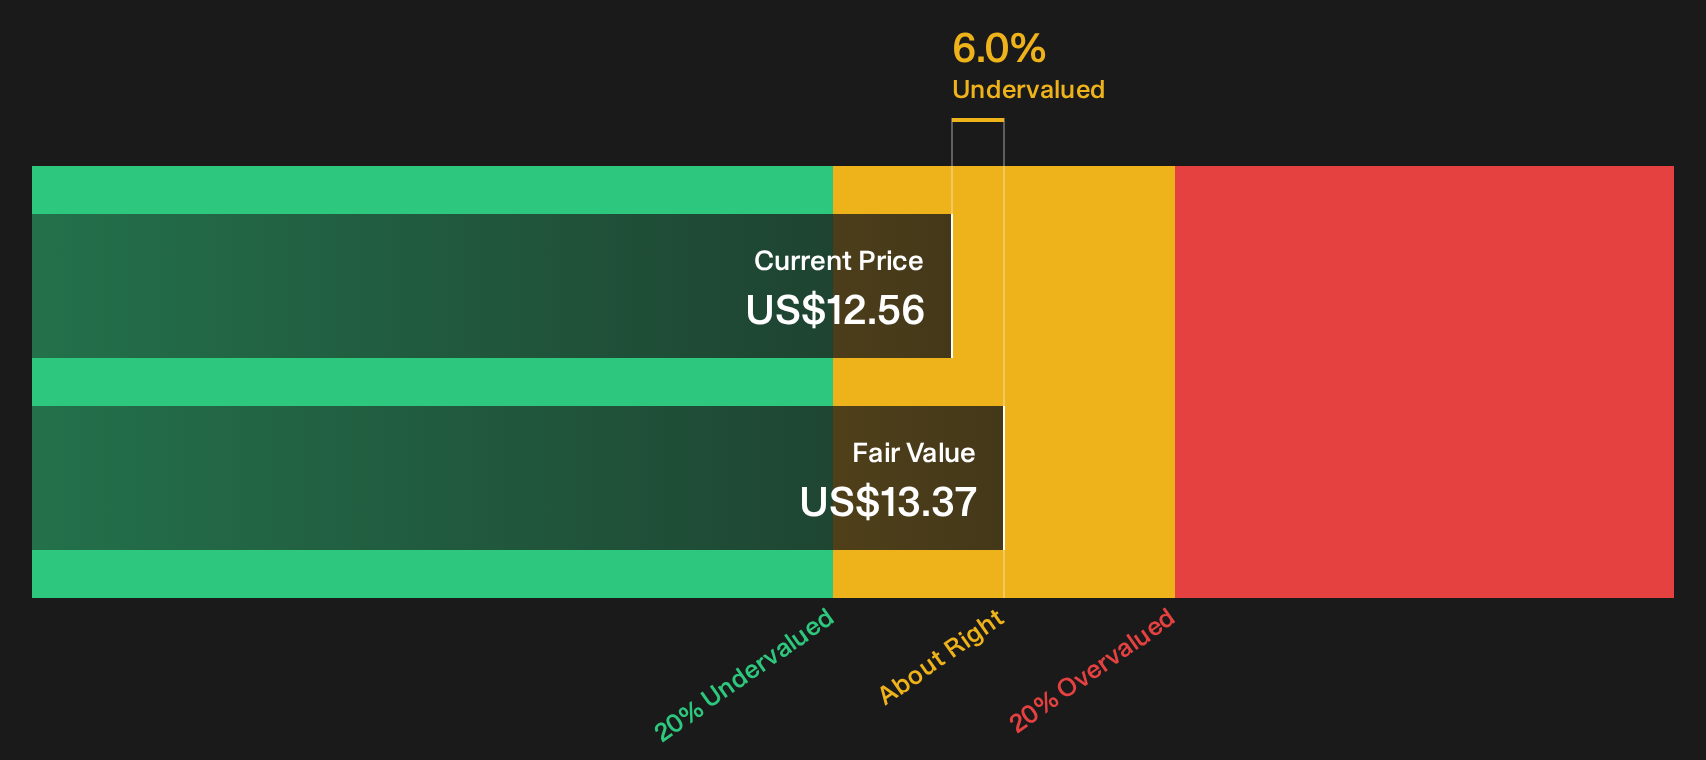
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Lionsgate Studios for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of caution and optimism around Lionsgate Studios feels familiar, do not wait for consensus to form. Instead, review the underlying data carefully and weigh both the 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Lionsgate Studios?
If Lionsgate Studios has sharpened your appetite for opportunity, do not stop here. Use focused screens to find other businesses that fit your risk and return preferences.
- Target resilient cash generators by checking a list of solid balance sheet and fundamentals (24 results) that can help you focus on companies with financial strength at their core.
- Hunt for potential mispricings by scanning a 42 high quality undervalued stocks that may highlight businesses where quality and price still look out of sync.
- Build a steadier income stream by reviewing a 6 dividend fortresses that focuses on higher yielding payers with more robust distributions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com