


EN
What Samvardhana Holders Bought Into
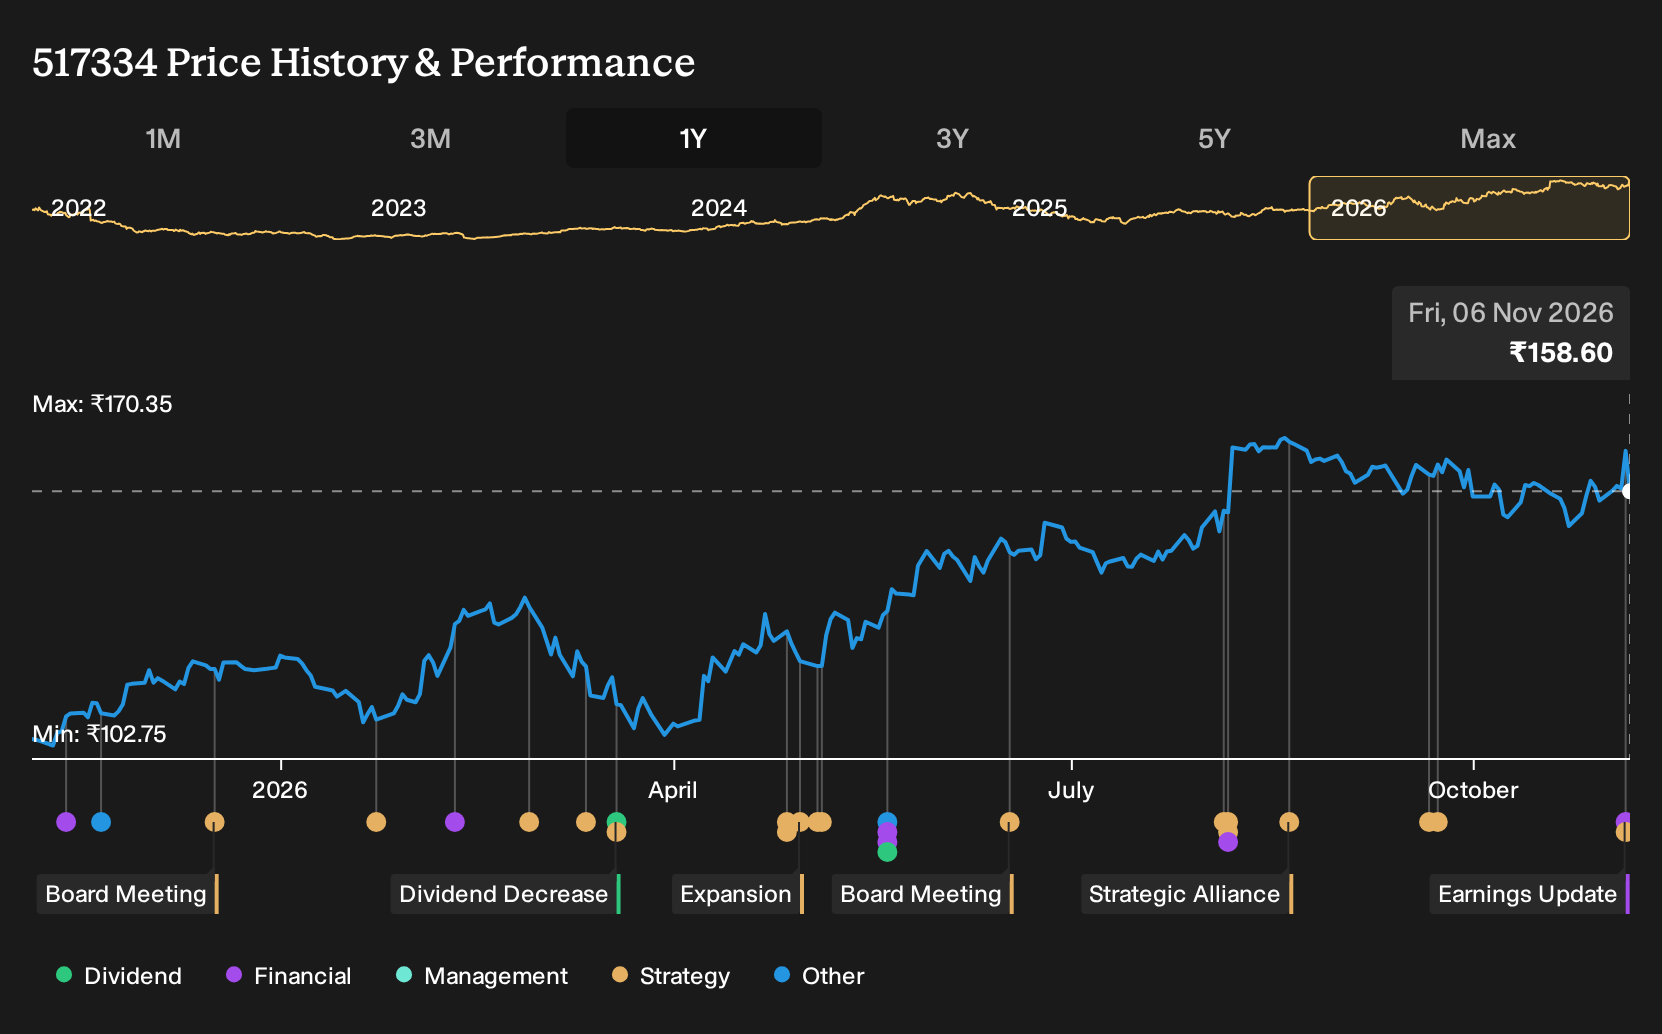
If you had been weighing Samvardhana Motherson International on 6 November 2025 and decided to buy, the outcome over the next twelve months turned out very differently from what either camp of analysts was sketching out. Investors who held Samvardhana Motherson International over the past year are up 53.6%, including dividends. That return now sits against a completed Autoelectric acquisition and fresh quarterly results, raising a sharper question. Which signals, if any, fairly justified an early commitment to this expansion story?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Samvardhana Motherson International. Zero in on 227 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing On Samvardhana Motherson International
The shares cost ₹104 at the start of the period, and anyone looking at Samvardhana Motherson International then saw two very different stories that still felt plausible.
The upbeat narrative pinned fair value at ₹110. It leaned on assumptions that revenue could grow 8.7% a year and that profit margins might settle at 4.6% over three years as acquisitions were integrated and new plants began operating.
The cautious narrative put fair value at ₹82. It focused on the risk that faster electric vehicle adoption would reduce demand for traditional components, even as heavy capital spending and acquisitions kept pressure on margins.
What The Results Changed For Samvardhana Motherson International
The completed purchase of Autoelectric, a €207 million harness supplier with €708 million in 2025 sales, supported the upbeat Samvardhana Motherson International narrative about scaling content and electrification exposure. Quarterly figures pointed in the same direction. Revenue increased from ₹298,760.1 million in Q2 2026 to ₹378,799.7 million in Q2 2027, while net income and net margin also improved, so the evidence leaned toward the optimistic case.
The key takeaway is straightforward: when an investment thesis depends on acquisitions and margin recovery, it is more useful to track how each deal changes reported revenue, net profit and net margin in the following year than to focus only on the purchase headline or projected synergies.
What Samvardhana Motherson International’s Run Already Prices In
Samvardhana Motherson International now trades at ₹159 after a 53.6% gain over the past year. This Narrative’s Fair Value sits below the current price, so its lens is that the market already bakes in a lot of good execution on new projects and acquisitions.
The focus is less on disruption risk and more on whether heavy capex, higher input costs and greenfield build outs can translate into sustained, profitable utilization without stretching the balance sheet. A buyer at today’s level has to judge whether large new facilities and deals can be filled and integrated at healthy margins.
"The main thing that has to go right is that heavy capex, acquisitions, and new facilities in emerging markets convert into sustained, profitable utilization across automotive and D.E.M.A.L. based non auto businesses, without eroding the group’s currently low leverage."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Looking One Step Beyond Samvardhana
Samvardhana Motherson International links your portfolio to how vehicles are built. One step away sits a business chasing a different prize.
Where Samvardhana focuses on components, this other firm is targeting labor itself. It wants machines that can handle physical work, not just driving.
Its pitch is simple. Sell the robot once, then keep selling skills that run on it.
Cleaning, welding, warehouse work, home help, each task becomes an add on.
If that model gains traction, attention could shift from car volumes to whoever controls the software running tomorrow’s physical workers.
That argument has a Narrative and a number behind it. → See the company one Narrative values 94% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com