


EN
Learn Why The Bull Case For Schneider National (SNDR) Could Change Following Intermodal Rail Partnership
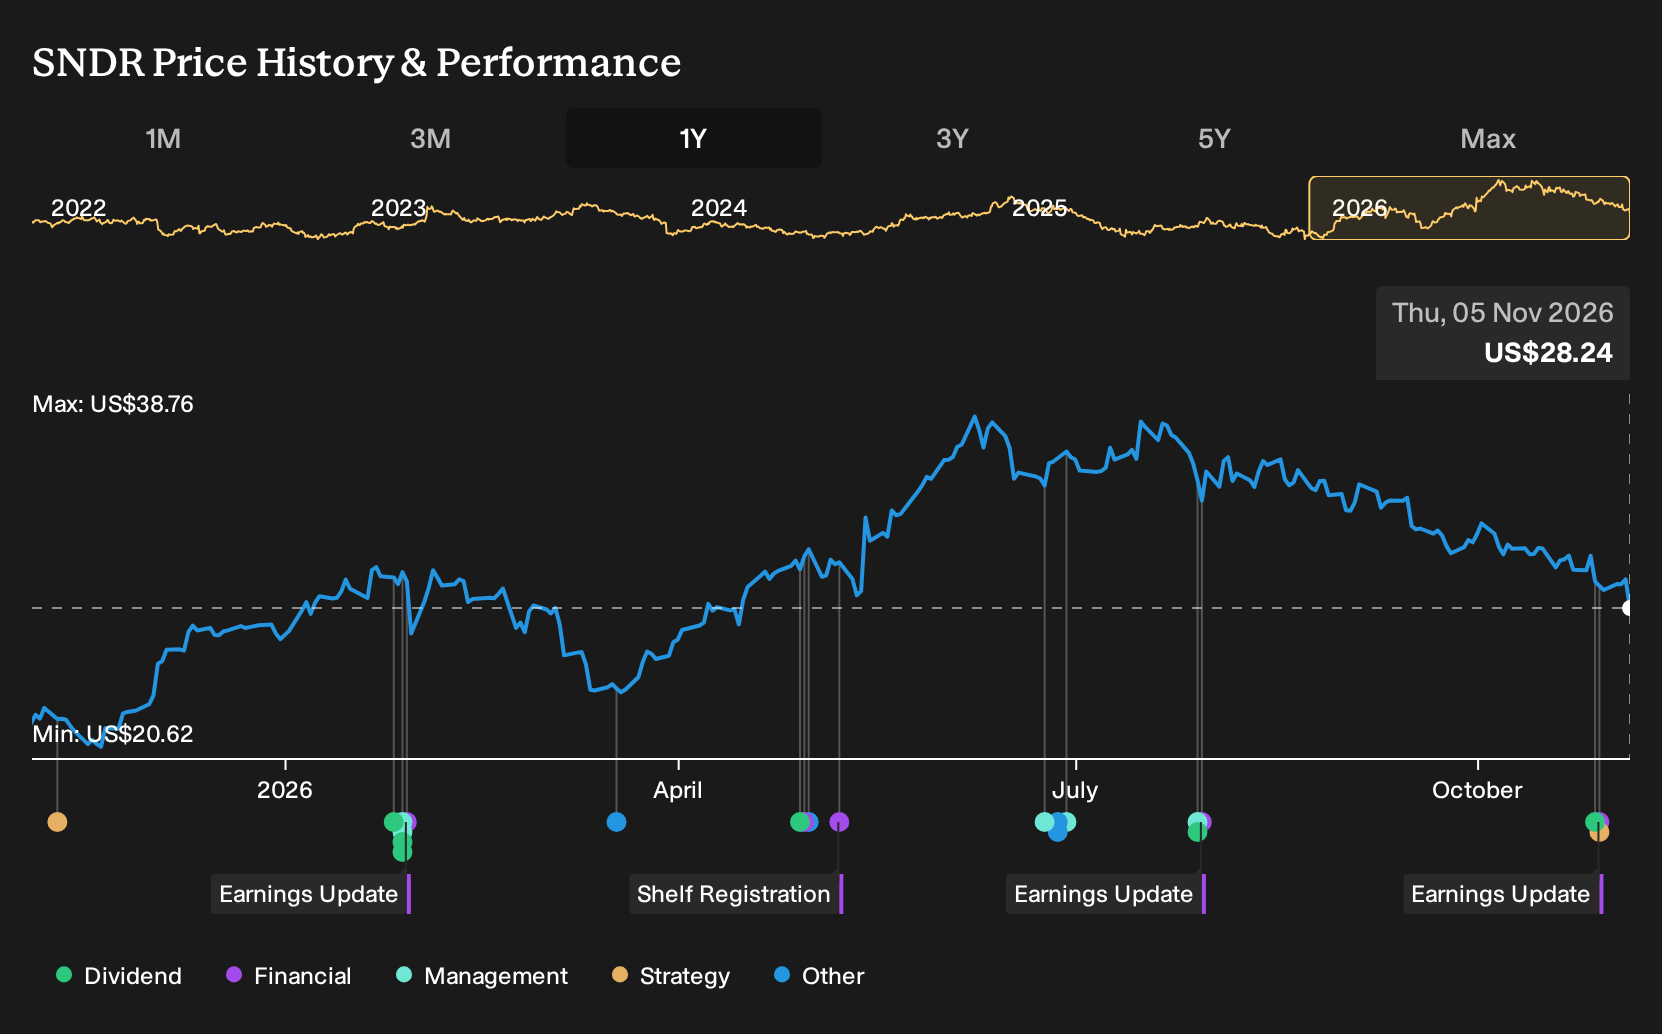
- Schneider National reported third quarter 2026 sales of US$1,585.3 million and net income of US$49.5 million, alongside a new intermodal collaboration with Norfolk Southern that ties Schneider's owned fleet and logistics platform into Norfolk Southern's eastern U.S. rail network.
- The combination of stronger earnings and the Norfolk Southern partnership highlights how Schneider National is leaning into intermodal scale, using company-owned equipment, rail access and logistics capabilities to support service reliability, cost control and long haul freight conversion from highway to rail.
- We will look at how Schneider National's investment narrative lines up with this earnings jump and the Norfolk Southern intermodal agreement.
Compare Schneider National’s intermodal-driven story with other freight and logistics stocks on our hand picked list of solid balance sheet and fundamentals (24 results) to see who else is pairing assets with disciplined financials.
Schneider National Investment Narrative Recap
To own Schneider National, you need to believe the business can keep shifting more freight into higher quality Intermodal and Dedicated contracts while holding margins together in a choppy trucking cycle. The latest quarter, with higher sales and net income versus a year ago, points to some progress on that execution, but freight demand and pricing still matter a lot.
Right now, the key near term swing factor is whether Intermodal growth and cost programs can offset pressure from any weaker spot activity and Dedicated churn, including the loss of a large customer. The biggest risk remains sharp swings in customer volumes or costs that could quickly squeeze margins again.
The most relevant recent development is the Norfolk Southern intermodal agreement. It ties Schneider National’s large company owned container and chassis fleet, drayage network and logistics platform into a major eastern rail network, which directly supports the Intermodal expansion that sits at the center of the current story.
If execution on that partnership is solid, it could help offset some volatility in the Truckload and Logistics segments by deepening rail based long haul offerings and potentially improving service reliability. Investors watching catalysts may track volumes on those eastern lanes, how pricing holds up and how well Schneider integrates this capacity while still controlling operating costs.
Schneider National's narrative projects US$7.2b revenue and US$502.6 million earnings by 2029. This scenario is based on an assumed 7.1% yearly revenue growth and an earnings increase of about US$391 million from US$111.6 million today.
Uncover why Schneider National's fair value indicates a 27% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate Schneider National story puts more weight on the risk that heavy AI and automation spending from larger rivals could squeeze its traditional trucking and brokerage profits. The lowest analysts were only penciling in US$6.9b revenue and US$469.2 million earnings for 2029 before this news. That is a more cautious script. Use that gap to stress test your own view and see how this new Norfolk Southern deal might shift forecasts.
Explore 2 other Schneider National fair value estimates, including one that suggests as much as 13% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Schneider National research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Schneider National. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Schneider National's overall financial health at a glance.
Looking For More Ideas Beyond Schneider National?
Once you have a handle on Schneider National, it can help to compare its story with other businesses that share similar financial traits or offer very different risk and return profiles. The Simply Wall St Screener is one way to surface a wider watchlist without getting lost in thousands of tickers.
- If capital preservation is near the top of your list, start with a 32 resilient stocks with low risk scores that aims to keep volatility and financial stress in check.
- If income matters more to you, scan a set of potential 6 dividend fortresses that pair meaningful yields with fundamental strength.
- If you prefer earlier stage potential, review a focused 9 elite penny stocks with strong financials that filters for smaller companies with stronger balance sheets than the typical micro cap.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com