


EN
Madrigal Pharmaceuticals (MDGL) Stock Trades At a Discount To Its Sales Base
Madrigal Pharmaceuticals has turned into a very different business now that Rezdiffra is generating material revenue. The real question for you today is whether a share price around recent levels is still matched by what the company is doing in sales.
- Over the past 5 years the stock has returned about 340.4%, which puts a lot of past optimism on the line when you ask how much current revenue can reasonably support.
- Crossing more than US$1b in net sales from Rezdiffra with an annualized run rate above US$1.7b and reaching profitability can reshape how investors think about the company’s ability to convert its MASH opportunity into sustained top line and cash generation.
- There is a second opinion on Madrigal Pharmaceuticals worth weighing. See what analysts think Madrigal Pharmaceuticals's shares could be worth.
For investors, the debate is whether Madrigal Pharmaceuticals' current share price is adequately backed by the level and trajectory of its sales from Rezdiffra.
If you want a second reference point alongside Madrigal Pharmaceuticals, you may also consider reviewing a focused screen of other 34 healthcare AI stocks.
Does Madrigal Pharmaceuticals Look Undervalued on Sales?
P/S suits Madrigal Pharmaceuticals because Rezdiffra has quickly become the main driver of the business and investors are focusing heavily on sales capacity rather than current earnings.
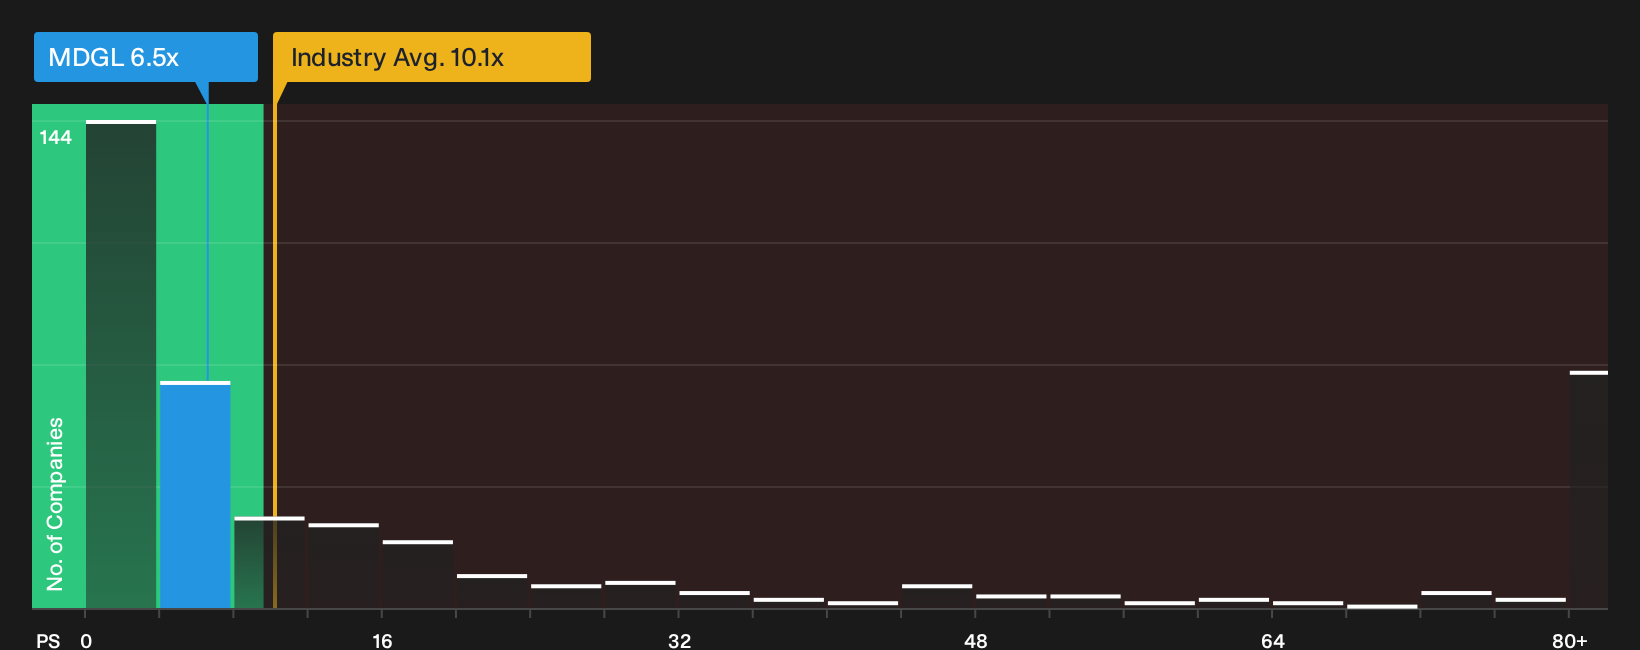
The stock trades on a P/S of 6.5x, which sits below the biotech industry average of 10.1x and also under a peer group average of 24.4x. A tailored fair P/S estimate, which factors in Madrigal’s margins, addressable market, size and risk profile, points to a higher ratio than where the shares trade today, so the current multiple screens as undervalued relative to that model. Because the recent move to profitability and the first US$1b from Rezdiffra are now in the public numbers, this gap reflects how much weight the market is putting on sustainability of that revenue stream rather than a lack of information. Despite that Q3 2026 milestone and ongoing real world data around Rezdiffra, the current P/S leaves Madrigal Pharmaceuticals priced at a discount to both its sector and closer peers on sales. Explore the numbers behind Madrigal Pharmaceuticals's P/S valuation.
The Madrigal Pharmaceuticals Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle leaves off for Madrigal Pharmaceuticals' P/S by spelling out which views on future growth, profitability and earnings power would need to hold for the stock to be worth much more or much less than it is today. Each narrative links its number to a clear view of how Madrigal Pharmaceuticals' potential, margins and risk profile could evolve, giving you something concrete to revisit as fresh information comes through.
One of the top community narratives on Madrigal Pharmaceuticals: 25% undervalued
"The current valuation implies the share price already reflects concerns about ongoing net losses and ex-U.S. reimbursement hurdles more than it does the potential…"
Discover why this Narrative puts Madrigal Pharmaceuticals at 25% undervalued.
The share price is only one piece of the Madrigal Pharmaceuticals puzzle
Before you treat Madrigal Pharmaceuticals as a straight valuation story, it is worth checking the broader health of the business, where internal risk checks have flagged potential pressure points that deserve your own review. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com