


EN
Is Hawaiian Electric Industries (HE) Cheap On Its Court Approved Settlement?
The recent court approval of a US$47.75 million securities settlement has put Hawaiian Electric Industries (HE) back in focus for investors who are weighing legal overhangs against fundamentals and the upcoming Q3 2026 results.
The current US$8.44 share price reflects a tough run, with the stock down 31.94% on a 90 day share price basis and the 1 year total shareholder return declining 27.18%. Recent pressure therefore looks more like fading momentum than a short blip as investors reassess legal and operational risks around Hawaiian Electric Industries ahead of the Q3 2026 update.
Compare how Hawaiian Electric Industries fits alongside other regulated utilities by scanning our hand picked 40 power grid technology and infrastructure stocks that are closely linked to grid reliability, resilience and infrastructure spending.
Hawaiian Electric Industries now trades close to published analyst targets after a steep slide that reflects heavy legal and operational caution. Is that discount tight for the risk, or still generous given the unresolved questions?
Most Popular Narrative: 7% Undervalued
The most widely followed narrative on Hawaiian Electric Industries points to a fair value of $9.06 versus the recent $8.44 close. This frames today’s legal headlines inside a longer view built around wildfire funding, grid investment and regulated returns.
Recent Hawaii legislation enabling wildfire liability caps, state funding for settlements, and securitization of wildfire safety investments significantly reduces legal and financial risk exposure while supporting large-scale infrastructure upgrades, which is likely to stabilize earnings and improve net margins.
Progress in implementing enhanced wildfire safety measures, supported by dedicated funding mechanisms, reduces future risk of catastrophic losses, strengthens public trust and regulatory goodwill, and may result in more favorable treatment of capital expenditures in rate base calculations, positively impacting future regulated earnings and revenue stability.
See why 16 investors see Hawaiian Electric Industries as 7% undervalued.
Result: Fair Value of $9.06 (UNDERVALUED)
Still, wildfire litigation costs and the need to finance settlement and grid resilience spending could strain Hawaiian Electric Industries' cash flow and keep leverage elevated.
Find out about the key risks to this Hawaiian Electric Industries narrative.
Another View: Hawaiian Electric Industries Through The Cash Flow Lens
The earlier discussion leaned on earnings and P/E to suggest Hawaiian Electric Industries looks cheap relative to peers. The SWS DCF model tells a different story. On that cash flow view, the estimated value is $2.88 per share, well below the current $8.44 price, which points to an overvalued outcome. How much weight do you give to a model that prices in long term cash strain from wildfire costs and borrowing needs?
Look into how the SWS DCF model arrives at its fair value.
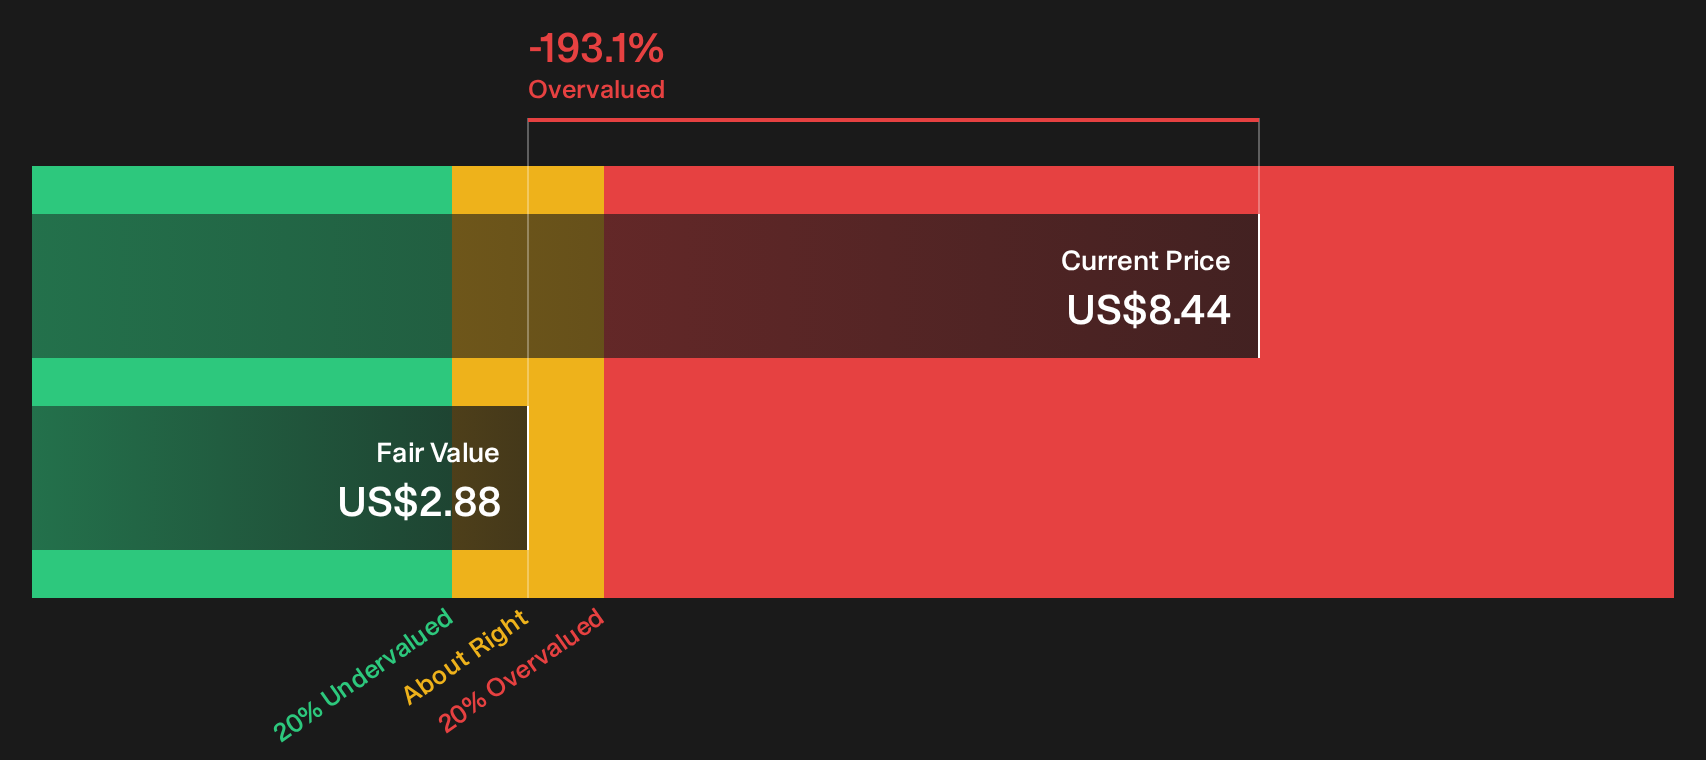
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hawaiian Electric Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Hawaiian Electric Industries so far. Use that tension as a prompt to move quickly, review the underlying data, and weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Hawaiian Electric Industries?
Do not stop with Hawaiian Electric Industries. Use this as a starting point, then widen your watchlist with focused stock ideas that match your risk and income goals.
- Target resilience first by reviewing a 32 resilient stocks with low risk scores that highlights companies with stronger downside protection and more measured risk profiles.
- Hunt for value by scanning a 21 high quality undiscovered gems that surfaces lesser known businesses with solid fundamentals before they hit wider radars.
- Prioritise financial strength by working through a list of solid balance sheet and fundamentals (24 results) so you can focus on companies backed by healthier balance sheets and sturdier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com