


EN
StepStone Group Stock What Record Earnings Beat Means
- StepStone Group reported quarterly revenue of US$362.71 million and earnings of US$0.66 per share, with fee-related earnings and margins reaching record levels alongside strong fundraising and higher fee-earning assets under management.
- The firm is using this momentum to expand into U.S. retirement and insurance solutions while deepening data and technology partnerships that support its private markets platform.
- We will now examine how StepStone Group's record fee-related earnings and fundraising shape the broader investment narrative for the business.
Scan how StepStone Group's private markets focus compares to other asset managers by reviewing a curated list of solid balance sheet and fundamentals (24 results) that are built to handle fundraising cycles and fee swings.
What Is StepStone Group's Investment Narrative?
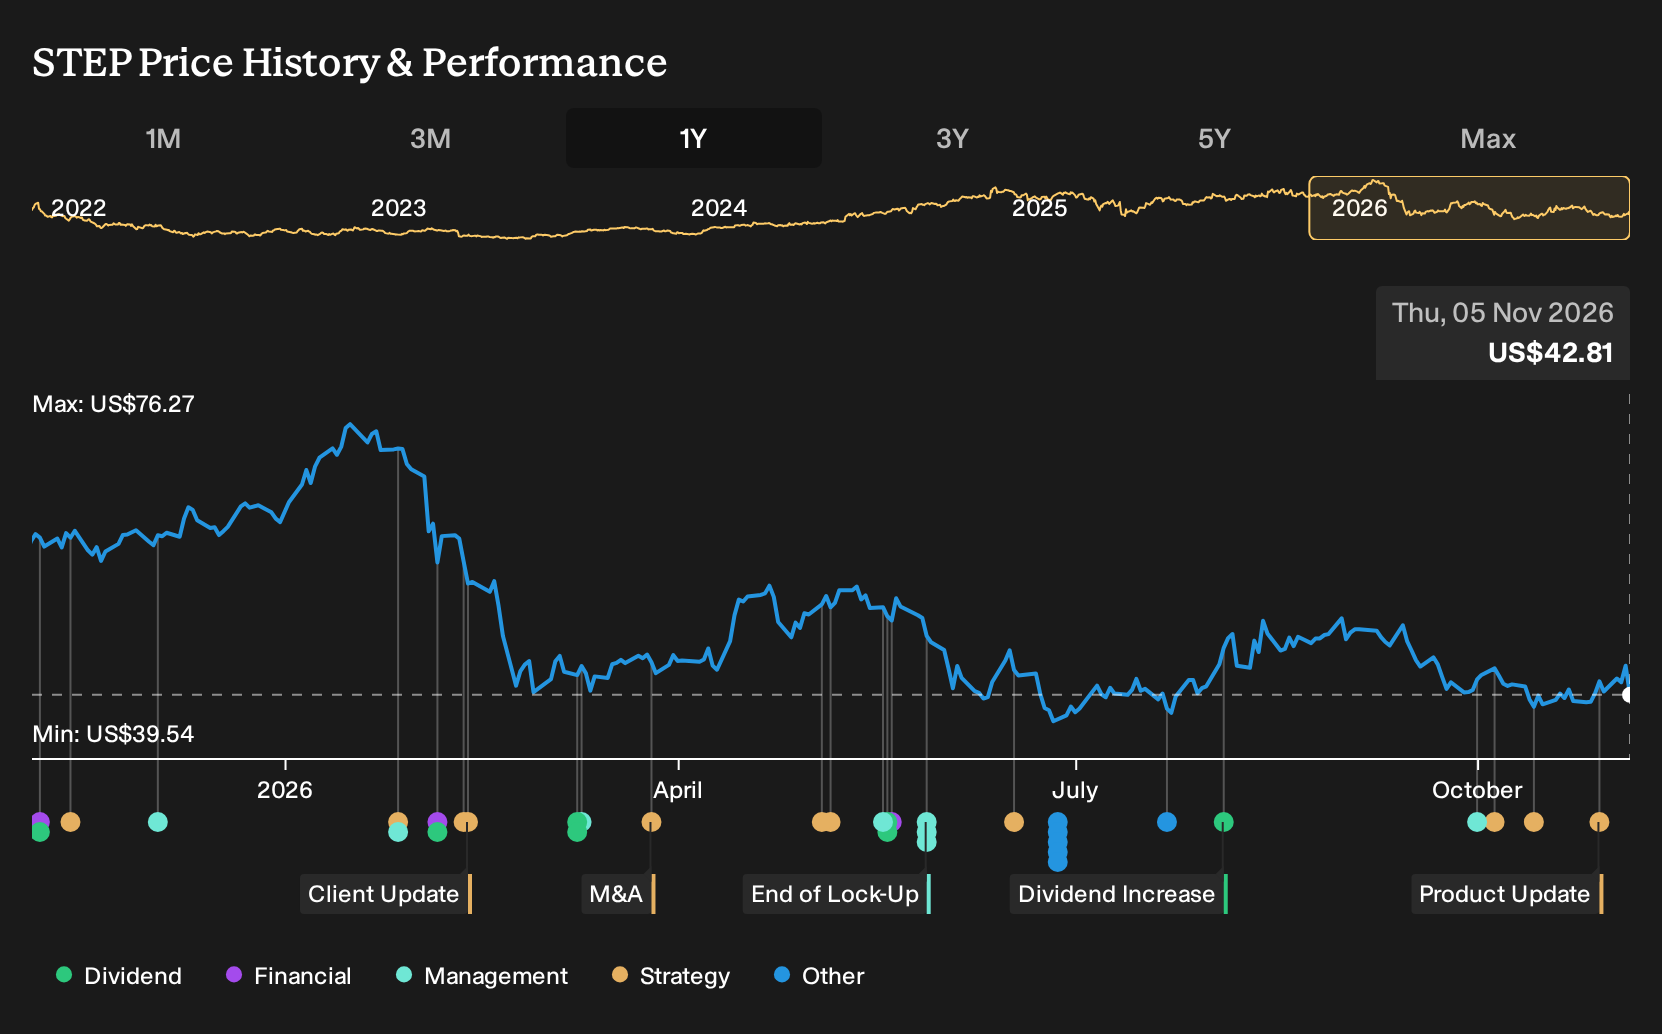
To own StepStone Group, you need to buy into a private markets platform that is fee driven, relatively light on capital needs, and dependent on sustained demand for outsourced alternatives expertise. The recent quarter fits that story by showing record fee related earnings alongside higher fee earning assets, plus strong capital raising across private debt and infrastructure. The joint launch with Kroll of new private credit PIK indicators also reinforces the data and analytics pitch that StepStone uses to win mandates and justify its pricing.
The wrinkle is on the income statement. Recent results show much higher revenue over six months yet still a net loss of US$187.03 million and ongoing pressure on earnings based payout metrics, which matters for a dividend that is flagged as not well covered by profits or free cash flow. In the short term, the key swing factors are whether fundraising momentum and high margin fee pools can keep offsetting volatile investment income, and whether expansion into retirement and insurance channels scales efficiently rather than adding cost faster than fee streams.
Even so, the appeal of StepStone Group as a scaled private markets platform has to be weighed against one stubborn pressure that keeps lurking in the background...
There's only one way to know the right time to buy, sell or hold StepStone Group. Head to Simply Wall St's company report for the latest analysis of StepStone Group's Fair Value.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your StepStone Group research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for StepStone Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate StepStone Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond StepStone Group?
If you want to stress test your thesis on StepStone Group, it can help to compare it with a wider watchlist of companies filtered by balance sheet strength, income potential, or valuation quality. The Simply Wall St Screener lets you do exactly that by narrowing the universe down to businesses that fit the kind of risk and return profile you care about most.
- For investors who prize financial resilience, start with a list of solid balance sheet and fundamentals (24 results) that can help you focus on companies built to withstand tougher conditions.
- If you are hunting for opportunities where quality and valuation intersect, consider a 42 high quality undervalued stocks that may align better with your return expectations and risk tolerance.
- Income focused readers can round out their research by scanning a 6 dividend fortresses that prioritize higher yields backed by underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com