


EN
Haemonetics (HAE) Lifted Guidance, Is The Stock Fully Valued?
Haemonetics (HAE) is back in focus after reporting fiscal second quarter results that topped revenue and earnings forecasts, with management also lifting guidance for the rest of the year on stronger product uptake.
Investors have leaned into the Haemonetics story over the past year, with the share price delivering a 55.18% year to date gain and a 41.29% 90 day share price return. The 1 year total shareholder return of 84.94% signals strong momentum building despite a recent 2.60% daily pullback.
Scan beyond Haemonetics and evaluate other medical technology players showing strong execution and product uptake with our curated 32 resilient stocks with low risk scores.
After a run that has taken Haemonetics close to analyst targets, yet still at an implied intrinsic discount, the gap between modelled value and market hesitation now matters. Is that caution grounded in reality or mispricing?
Most Popular Narrative: 30% Undervalued
Haemonetics last closed at $124.11, while the most widely followed narrative pegs fair value at $124.50 using a 7.92% discount rate. That small dollar gap, combined with a roughly 30% intrinsic discount to future cash flows, puts the focus squarely on how much of the plasma and hospital story is already reflected in the price.
Enterprise wide portfolio transformation that has already lifted adjusted gross margin to 60.3% and adjusted operating margin to 25.4%, together with free cash flow conversion above 100% of adjusted net income over the last twelve months, supports the idea that a richer mix of disposables and software can help maintain net margin resilience and cash generation.
See why 9 investors see Haemonetics as 0% undervalued.
Result: Fair Value of $124.50 (UNDERVALUED)
Still, higher tariffs and Haemonetics' roughly US$1.2b debt load could pressure margins and limit flexibility if cash generation or plasma volumes disappoint relative to expectations.
Find out about the key risks to this Haemonetics narrative.
Another View: Haemonetics On Earnings Multiples
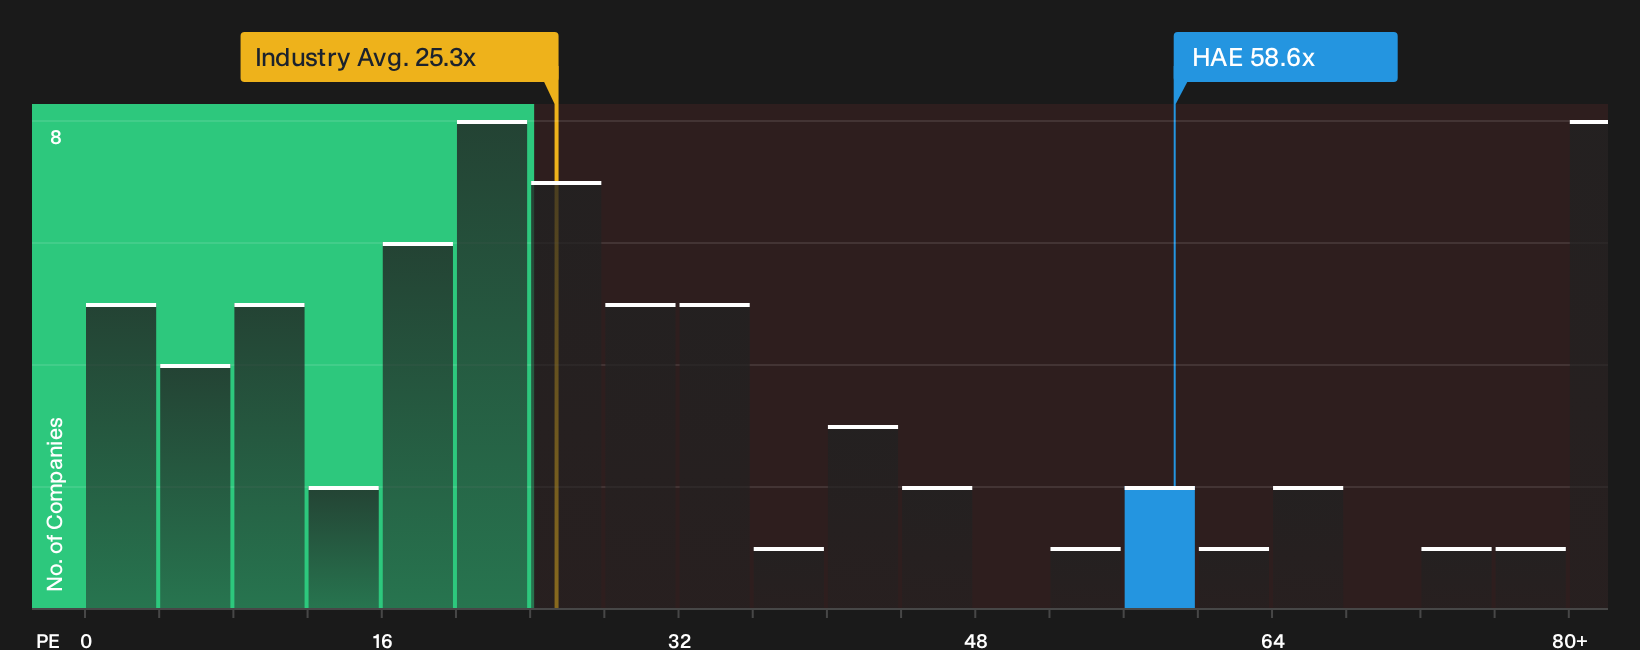
While the SWS DCF model points to Haemonetics trading at a discount to its future cash flow value, the picture changes when looking at earnings multiples. The stock trades on a P/E of 58.6x, above both the US Medical Equipment industry at 26.5x and peers at 54.8x, and well ahead of a 27.8x fair ratio that the market could gravitate toward over time. Does that gap represent patience being rewarded or a richer entry point than you are comfortable with?
For a closer look at how the current earnings multiple compares with what the numbers imply, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Haemonetics story so far. Act while the data is fresh and weigh the balance of 2 key rewards and 3 important warning signs.
Looking for more Haemonetics sized opportunities?
If Haemonetics has you rethinking what is possible for your portfolio, do not stop with one idea. Use fresh data, compare high quality businesses and upgrade your watchlist.
- Target resilient balance sheets and steady fundamentals with a curated list of solid balance sheet and fundamentals (24 results) that helps you separate durable businesses from fragile stories.
- Hunt for quality at a reasonable price through our hand picked 42 high quality undervalued stocks that surfaces cash generative companies trading below their implied worth.
- Stack potential income and stability by reviewing a focused 6 dividend fortresses that highlights higher yielding businesses with stronger supporting metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com