


EN
Is Softer Earnings Altering The Investment Case For Nolato Stock?
- Nolato reported third quarter 2026 sales of SEK 2,500 million and net income of SEK 172 million, with basic EPS from continuing operations at SEK 0.64.
- For the first nine months of 2026, Nolato's revenue reached SEK 7,311 million while earnings from continuing operations totaled SEK 522 million, highlighting pressure on profitability relative to reported sales.
- We will now examine how Nolato's investment narrative is affected by higher sales but softer earnings in the latest quarterly results.
Nolato Investment Narrative Recap
To stay invested in Nolato, you need to believe that the shift toward higher value Medical Solutions and engineered materials can support healthier earnings over time, even when input costs or demand look choppy. The latest report shows higher sales but softer earnings, so the near term focus sits squarely on restoring margin quality.
The key short term catalyst is execution on large healthcare and materials programs, including automation and cost pass through, so that volume turns into cash rather than just headline revenue. The biggest current risk is that raw material inflation and uneven demand in areas like hygiene or automotive keep squeezing profitability.
The third quarter 2026 earnings announcement is the update that matters most right now. Sales for the quarter reached SEK 2,500 million while net income came in at SEK 172 million, and basic EPS from continuing operations was SEK 0.64. For nine months, Nolato reported SEK 7,311 million in revenue and SEK 522 million in earnings from continuing operations.
Those figures give you a clear checkpoint on whether the longer term catalysts are translating into results. Healthcare and engineered materials remain central to the story, but the softer profit trend highlights execution risk around cost inflation, overheads and volume swings. Your assessment is whether current earnings pressure is a temporary drag on that broader thesis.
Nolato's current consensus narrative points to revenue of SEK 12.7 billion and earnings of SEK 1.2 billion by 2029, based on analysts' assumption of 10.4% yearly revenue growth and an earnings increase of about SEK 484 million from SEK 716.0 million today.
Uncover why Nolato's fair value indicates a 31% potential upside to its current price that could narrow quickly.
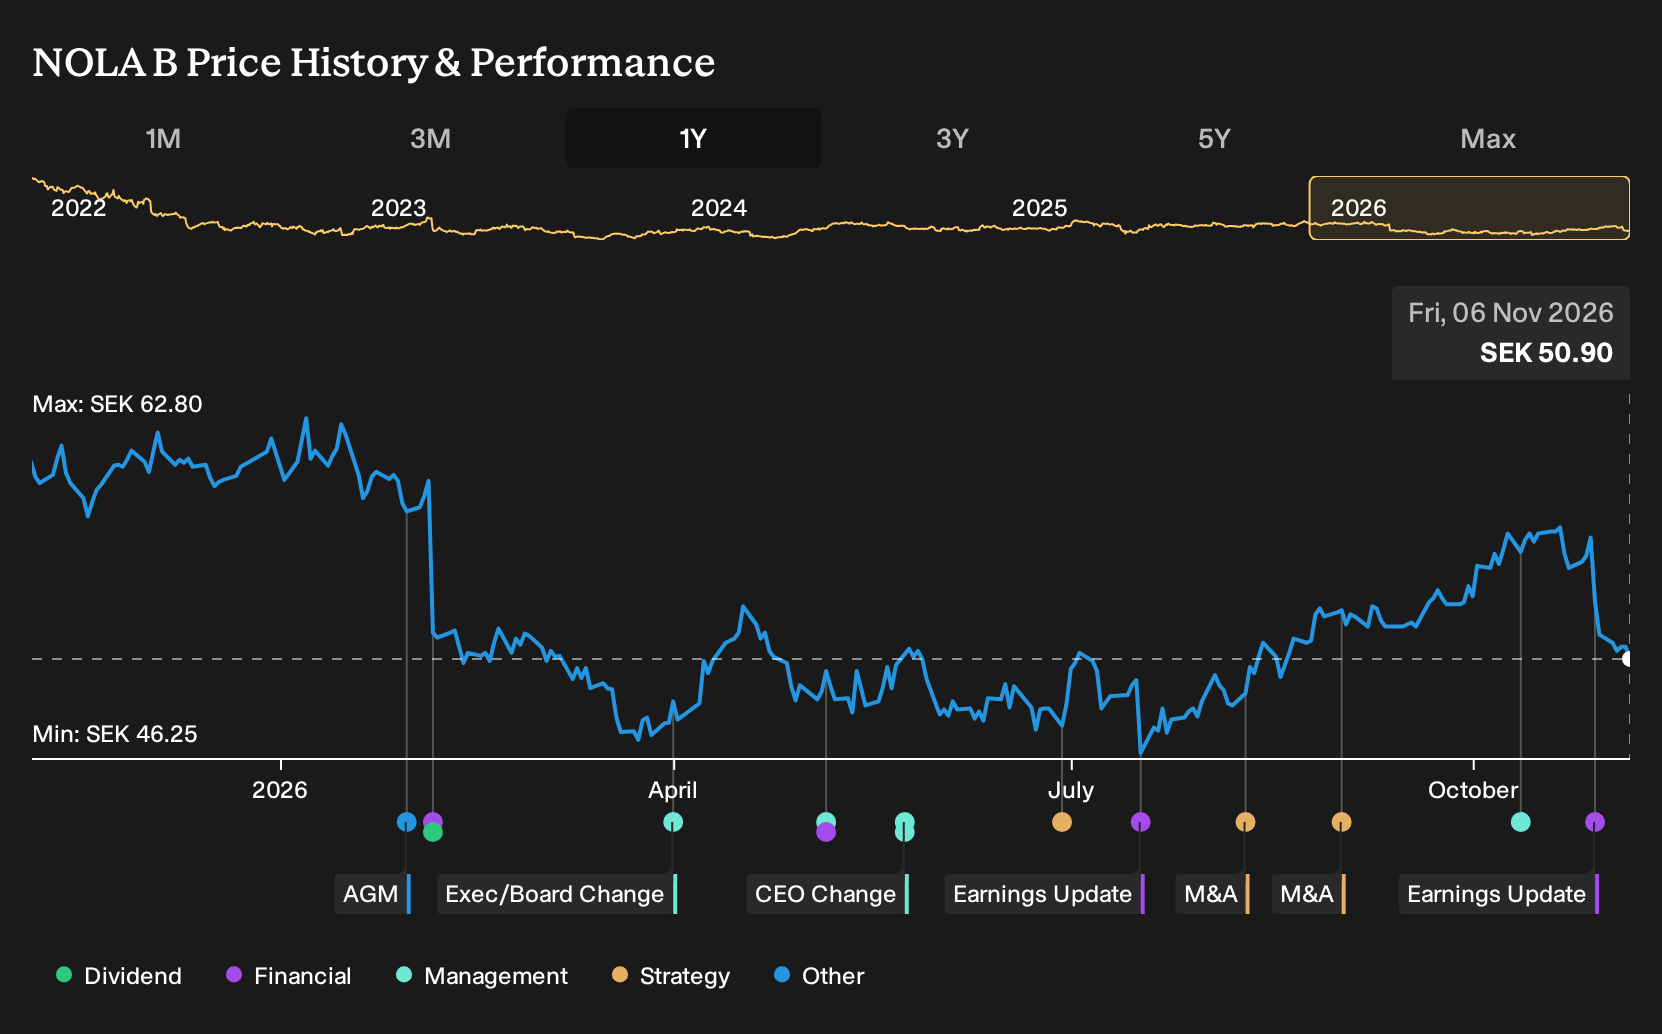
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between SEK 66.5 and about SEK 94.9, so even a tiny sample shows a wide personal valuation spread. Set those opinions against Nolato’s earnings pressure from higher input costs and uneven volumes, then weigh how such moving parts could shift your own view.
Explore another Nolato fair value estimate, including one that suggests as much as 86% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Nolato research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nolato. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nolato's overall financial health at a glance.
Looking for more Nolato investment ideas?
If Nolato has sparked your interest but you want a broader watchlist, use the Simply Wall St Screener to line up other companies with financial profiles that fit how you like to invest.
- If you care most about resilient balance sheets and steady fundamentals, start with this curated list of solid balance sheet and fundamentals (192 results) to help you spot businesses built on firmer financial ground.
- If value is your priority, compare Nolato with a targeted 224 high quality undervalued stocks that filters for quality companies trading below their estimated worth.
- If you are hunting for less crowded opportunities, scan a focused 592 high quality undiscovered gems that highlights under-the-radar stocks with strong underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com