


EN
Are Stronger Sales Altering The Investment Case For Woolworths Group (ASX:WOW)?
- Woolworths Group reported first quarter sales of $19,353 million for the period ended October 4, 2026, compared with $18,483 million a year earlier, alongside recent updates pointing to 3.8% revenue growth and a 239.3% rise in earnings per share year on year.
- The combination of higher quarterly sales and the sharp improvement in earnings per share suggests Woolworths Group is converting trading conditions into stronger operating performance, which matters for a retailer investing heavily in supply chain automation, e commerce and new earnings streams.
- We will now look at how Woolworths Group's stronger quarterly sales performance may influence the existing investor narrative around cost discipline.
Scan how Woolworths Group's latest trading update compares across the sector by lining it up against 6 resilient stocks with low risk scores in consumer staples and beyond.
Woolworths Group Investment Narrative Recap
To own Woolworths Group, you effectively need to believe that steady supermarket demand, supply chain automation and growing e commerce can offset margin pressure from value programs and regulation. The latest quarter, with A$19,353 million in sales and strong earnings per share, supports the idea that current trading conditions are feeding through to profitability.
The near term swing factor is whether cost efficiency from automation, AI and online fulfilment keeps outpacing higher fuel, logistics and value investment. The biggest risk is that tighter pricing rules, supplier levies and any ongoing weakness in New Zealand Food compress margins faster than Woolworths Group can cut costs.
The most relevant piece of news for that thesis is the recent trading update pointing to 3.8% revenue growth and a 239.3% rise in earnings per share year on year. You see a retailer not just holding the top line, but also converting sales into much stronger per share profitability over the last reported period.
For catalysts, that EPS jump intersects directly with Woolworths Group investment in automated distribution centres, e commerce fulfilment and AI enabled service. The key question now is execution. If operational projects keep supporting earnings while funding value for shoppers, the thesis around cost discipline and complementary businesses such as Petstock and Everyday Rewards remains central.
What The Analyst Scenario Implies For Woolworths Group
Analysts sketch a fairly specific roadmap for Woolworths Group over the next few years, and it leans heavily on steadier earnings and measured capital discipline. The story is simple enough to follow. Revenue is assumed to grow by 4.3% each year. Profit margins are modeled to move from 1.6% today to 2.7% in three years, which is a big shift for a supermarket operator working on tight spreads.
On that framework, consensus forecasts point to earnings of A$2.2b by around October 2029, compared with A$1.1b today. That is roughly a 2x lift in profit. Analysts are also baking in very mild share count reduction, with outstanding shares expected to fall by about 0.19% per year across the next three years. All of this is wrapped into a discounted cash flow style setup that uses a 7.33% discount rate to bring those future cash flows back to today.
There is also a valuation bridge built into the Woolworths Group narrative. To line up with the current analyst price target, the business would need to trade on a P/E of 27.2x in 2029, versus 44.1x today, on those A$2.2b earnings. Analysts quote that future multiple as being lower than the current P/E for the broader AU Consumer Retailing group at 36.7x. In practice, that means the scenario assumes both higher earnings and a lower earnings multiple at the same time.
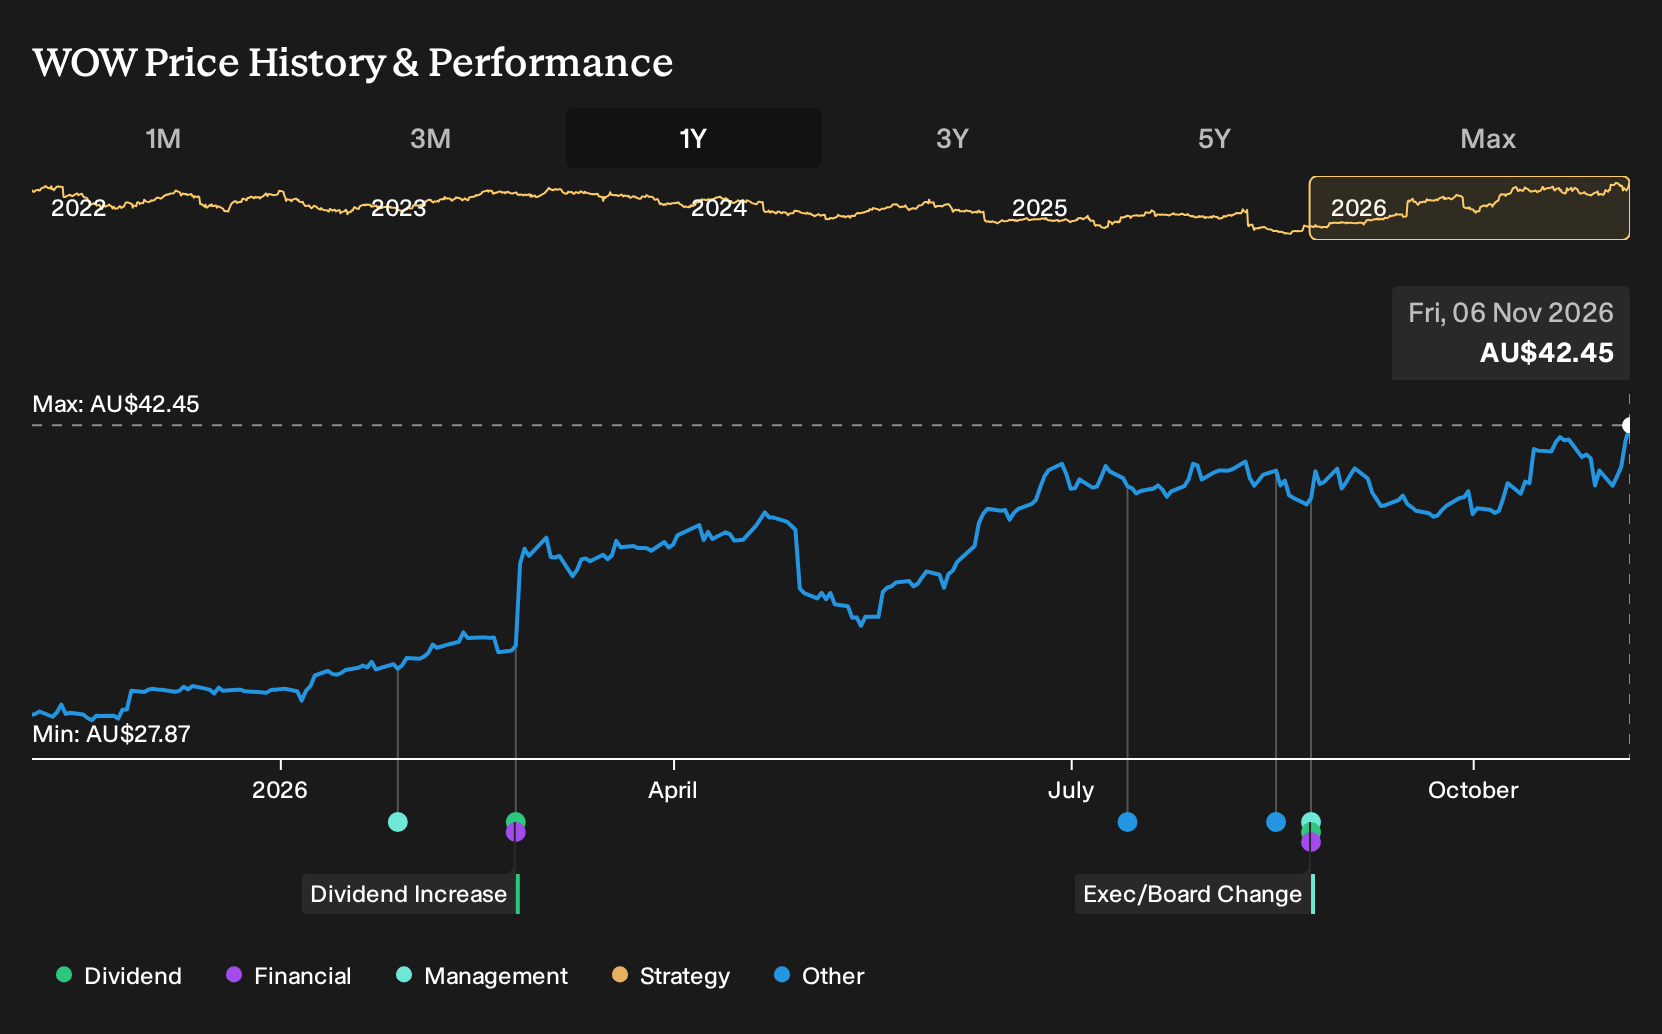
The consensus target price sits at A$39.32. With Woolworths Group last quoted around A$41.16, that target is about 4.7% below the market price as of early November 2026. Forecasts are not uniform either. Individual analyst targets range from A$31.50 on the low side to A$43.50 at the top end, which gives you a sense of how differently people are interpreting the same cost and regulation themes.
Woolworths Group's narrative projects revenue of A$81.2b and earnings of A$2.2b by 2029. This rests on 4.3% yearly revenue growth and roughly a 2x increase in earnings from A$1.1b today.
Uncover why Woolworths Group's fair value indicates a 7% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about A$39.32 and A$62.36, so some private investors see Woolworths Group close to current pricing while others model a much richer outcome. When you set that alongside margin and fuel cost risks, as well as automation and e commerce catalysts, it becomes clear why opinions can diverge so sharply. Use these contrasting viewpoints as a prompt to explore several alternative angles before forming your own stance.
Explore 2 other Woolworths Group fair value estimates, including one that suggests as much as 7% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Woolworths Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Woolworths Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Woolworths Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Woolworths Group?
If the Woolworths Group story has sharpened your thinking about risk, income and resilience, you can use that same lens to scan a wider opportunity set with the Simply Wall St Screener.
- For investors who want resilience to come first and volatility second, you can start with a basket of 6 resilient stocks with low risk scores that already screen well on core risk metrics.
- If growing income is a priority and you care about the reliability of those cheques as much as the size, you can focus on companies that show up as 5 dividend fortresses.
- When you want to look beyond the usual tickers and see what smaller companies with solid fundamentals look like, you can filter for 14 high quality undiscovered gems that might warrant a spot on your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com