


EN
Is Keysight Technologies (KEYS) Cheap As XR3 And Software Growth Drive Its Next Phase?
Keysight Technologies (KEYS) just put new hardware and software capabilities in front of customers, led by its XR3 rack-mounted oscilloscope and a broad test portfolio shown at electronica 2026.
The latest XR3 launch and wider electronica 2026 showcase come after a sharp pullback, with Keysight Technologies’ share price down 32.84% over the past month and 23.57% over 90 days, even though the year-to-date share price return is 26.15% and the 3-year total shareholder return is 113.77%. This suggests that longer term holders have still seen strong compounding, while short term momentum has clearly faded.
Scan beyond Keysight Technologies and size up other test, measurement, and AI infrastructure plays with our curated list of 53 AI infrastructure stocks.
So after a sharp pullback but still solid multi year gains, is Keysight Technologies now priced for most of the story already, or does the recent slide leave real upside still on the table once you run the numbers?
Most Popular Narrative: 37% Undervalued
Keysight Technologies closed at $260.61 compared with the most followed fair value estimate of $415.08. The pullback therefore aligns with a valuation gap that this narrative treats as meaningful rather than marginal.
Expansion of software, simulation and recurring service offerings is advancing, with software and services reaching roughly 33% of Q3 2026 revenue, annual recurring revenue at 24% of mix and the simulation business expected to exceed US$0.5b in 2026. This supports high gross margins near the upper 60s percentage range and contributes to operating margin strength.
See why 22 investors see Keysight Technologies as 37% undervalued.
Result: Fair Value of $415.08 (UNDERVALUED)
Still, two pressure points hang over the Keysight Technologies story: ongoing supply constraints that push roughly US$100m of revenue out in time, and acquisition integrations where promised cost synergies and margin targets may arrive more slowly than bulls expect.
Find out about the key risks to this Keysight Technologies narrative.
Another Take On Keysight Technologies: Valuation Through The P/E Lens
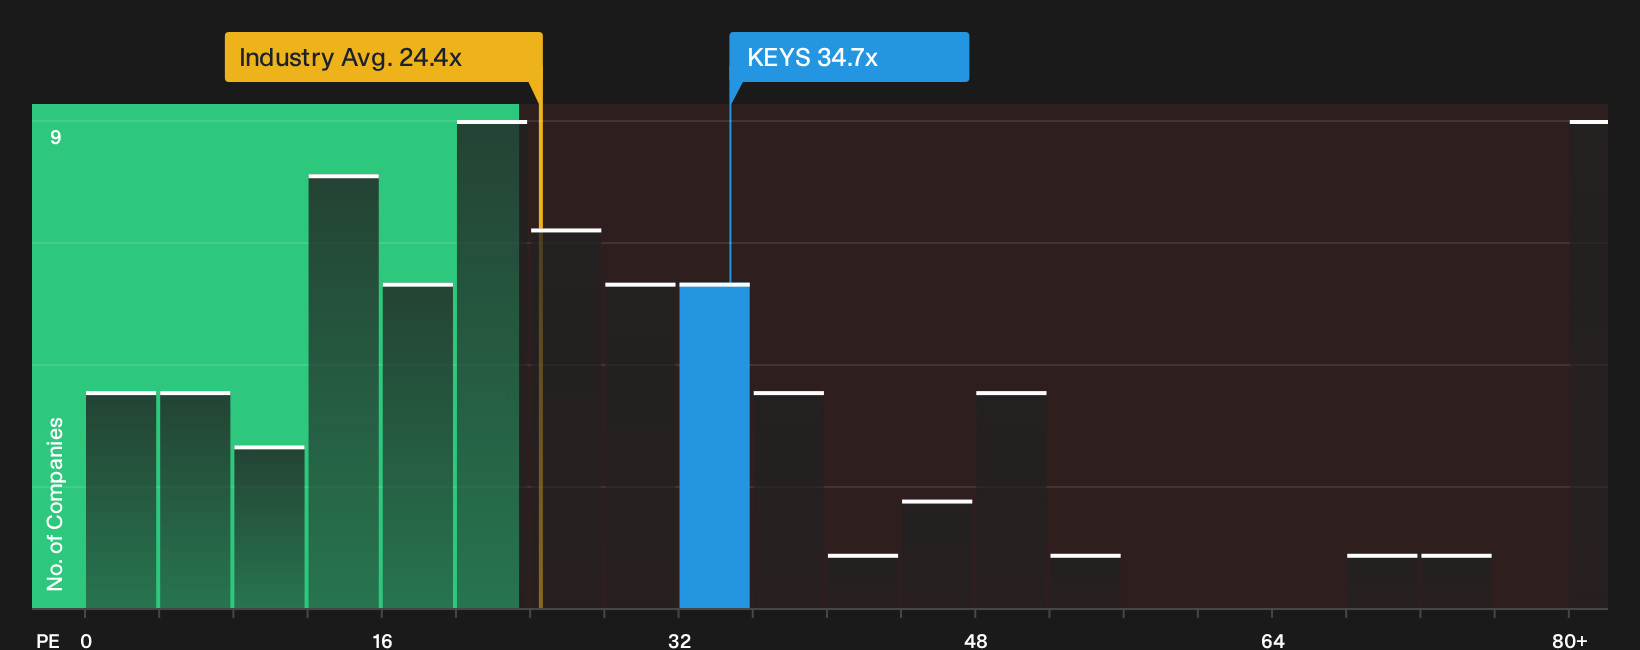
The first narrative leans heavily on a fair value of $415.08, yet Keysight Technologies currently trades on a P/E of 34.7x compared with 24.4x for the US Electronic industry and 27.7x for peers. Even against a fair ratio of 31.7x, that premium is clear and raises the risk that any slip in execution, or sentiment, could hit the share price faster than the income statement.
That leaves a genuine question for you as an investor. Is the 34.7x P/E simply the going rate for a high quality test and measurement specialist with AI and aerospace exposure, or is the market already paying in advance for a lot of the upside that others expect?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals in the Keysight Technologies story can feel uncomfortable, so move quickly on your own homework and weigh both sides of the argument. To see the full balance of potential upside and the issues investors are watching, drill into the 4 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Keysight Technologies?
If you stop your research with Keysight Technologies, you risk missing other opportunities that might suit your goals even better across quality, value, and resilience.
- Target strong balance sheets and robust fundamentals by scanning our list of solid balance sheet and fundamentals (24 results) that focuses on financially secure businesses.
- Hunt for potential value opportunities by reviewing the 42 high quality undervalued stocks that highlight companies trading below their assessed worth.
- Prioritize resilience and capital preservation by checking the 32 resilient stocks with low risk scores built around businesses with lower assessed risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com