


EN
Is Independence Realty Trust (IRT) Overvalued On Earnings Today?
Independence Realty Trust has delivered a 33.7% share price gain over the past three years, and now the key issue for investors is whether that performance is backed up by the apartment REIT's earnings power. With the stock changing hands at around US$15.32, the question is how much of its current profit profile is already reflected in that price.
- The 33.7% return over three years puts real money on the line for anyone asking whether Independence Realty Trust's current earnings can support the valuation implied by that move.
- The planned US$1.8b merger with Centerspace, which would create an US$8b apartment portfolio, can reshape future earnings through scale, operating efficiencies, and integration costs that all matter for what investors are paying for today.
- The analysts covering Independence Realty Trust have run their own numbers. See what analysts think Independence Realty Trust's shares could be worth.
For investors, the debate is whether Independence Realty Trust's current share price is justified by the earnings it is generating today and expected to sustain over time.
If you are weighing Independence Realty Trust against other apartment-focused ideas, it can help to compare it with 42 high quality undervalued stocks.
Is Independence Realty Trust Getting Expensive on Earnings?
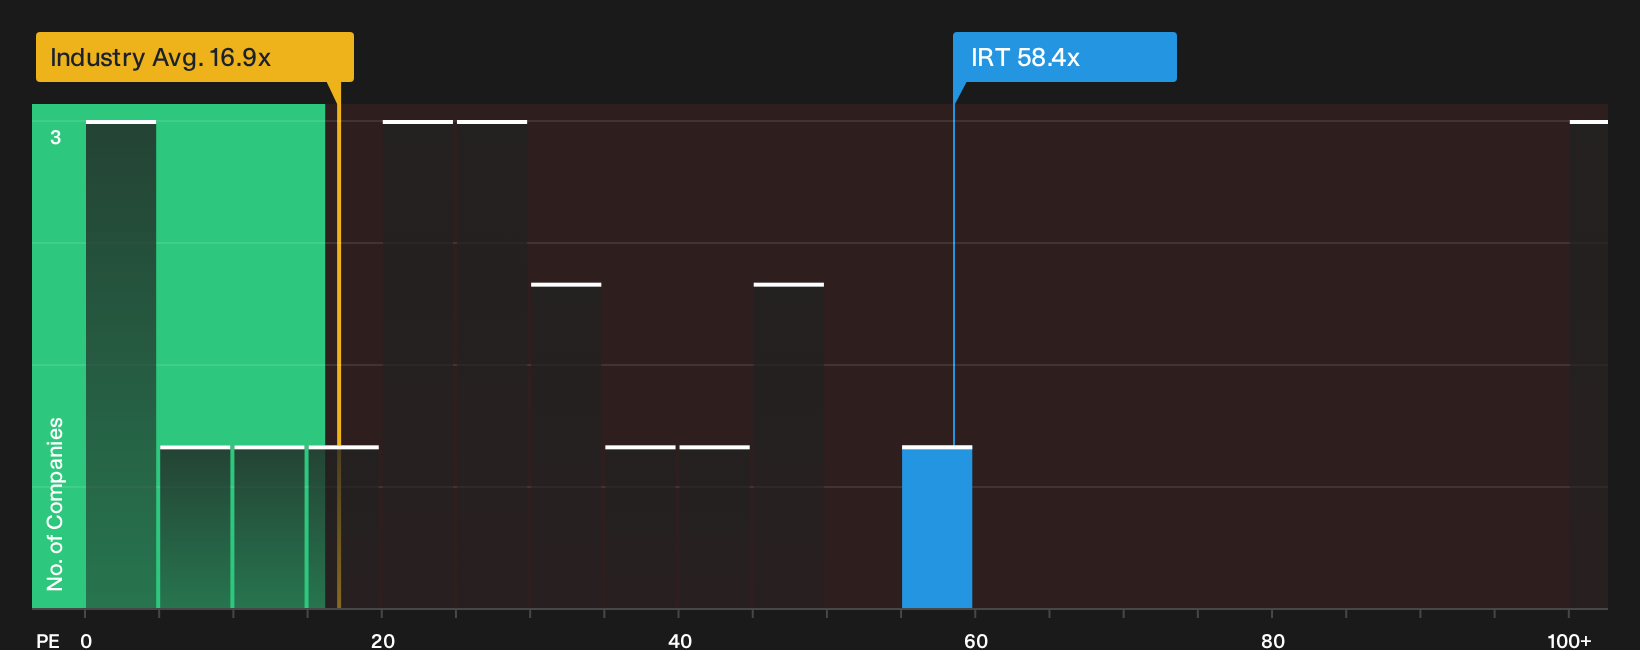
P/E is usually the cleanest yardstick for a REIT like Independence Realty Trust because earnings already capture interest costs and other recurring expenses that equity holders care about. On this lens, the stock trades at about 58.4x earnings, which is far above the Residential REITs group on roughly 16.9x and also clear of the broader peer set near 24.3x.
Despite the planned US$1.8b merger with Centerspace lifting attention on the story, the current P/E sits well above the level suggested by a more tailored fair multiple that blends Independence Realty Trust's sector, size and risk profile. That gap points to investors paying a premium for each dollar of earnings compared with what this framework implies is justified, so anyone considering the shares needs to decide whether the balance of earnings quality, growth prospects and merger execution risk supports that richer tag. Explore the numbers behind Independence Realty Trust's P/E valuation.
The Independence Realty Trust Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Independence Realty Trust valuation puzzle leaves off by spelling out which growth, margin and earnings paths would need to play out for the stock to look meaningfully cheap or expensive relative to today's price. Each Narrative treats Independence Realty Trust's fair value as a hypothesis about how the business might perform and then leaves it open to be tracked over time as new results come through.
One of the top community narratives on Independence Realty Trust: 20% undervalued
"High affordability barriers for single-family homeownership, underpinned by elevated home prices and mortgage rates, continue to extend renter tenure and bolster demand…"
Discover why this Narrative puts Independence Realty Trust at 20% undervalued.
One more Independence Realty Trust check that belongs beside the valuation work
Share price comparisons only tell part of the story, because Simply Wall St's broader review of Independence Realty Trust has flagged specific risk checks that deserve a closer look before you decide what to do next. Take a closer look at 4 warning signs (2 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com