


EN
Did Earnings And Buybacks Just Shift Simpson Manufacturing's (SSD) Investment Narrative?
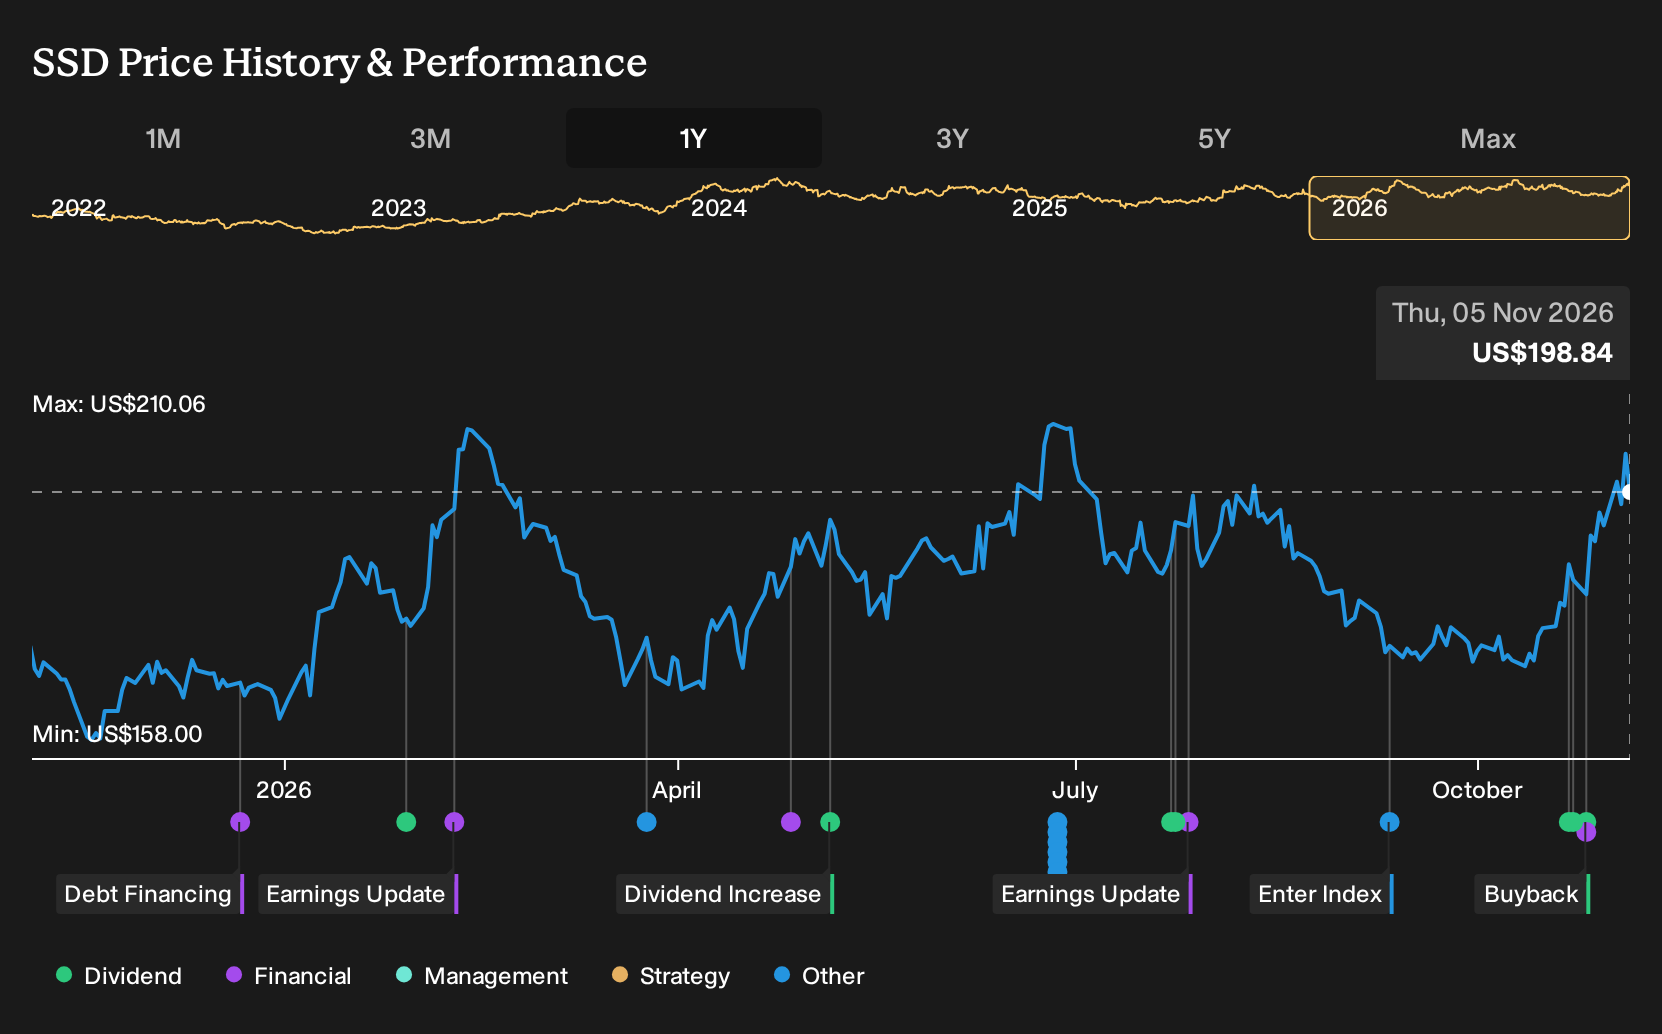
- Simpson Manufacturing reported third quarter 2026 sales of US$638.13 million and net income of US$109.12 million, alongside a US$1,000 million share repurchase authorization and a regular quarterly dividend of US$0.30 per share declared in October 2026.
- The company combined earnings resilience, explicit cost and pricing discipline around higher steel input costs, and a sizeable, open-ended buyback program that together highlight management’s focus on both operating efficiency and capital returns.
- We will look at how Simpson Manufacturing's investment narrative evolves given resilient earnings and the newly expanded US$1,000 million repurchase plan.
Look beyond Simpson Manufacturing and consider other businesses that combine resilient earnings with disciplined capital returns through our hand picked 32 resilient stocks with low risk scores.
Simpson Manufacturing Investment Narrative Recap
To own Simpson Manufacturing, you need to be comfortable with a construction tied business that is relying on pricing, product mix and cost control rather than booming housing demand. Recent quarterly results show sales of US$638.13 million and net income of US$109.12 million in a weak housing backdrop, which keeps the core story centered on margin discipline and code driven demand.
The key short term swing factor is still how effectively Simpson Manufacturing offsets higher steel and other input costs with price increases and efficiency gains. The main risk remains a deeper or longer dip in construction activity that would pressure volumes, especially in higher content regions and more competitive fastener categories.
The most relevant update right now is management’s guidance for a full year 2026 consolidated operating margin of 20.0% to 20.5%, which includes a US$11 million gain on a land sale. This margin range frames how Simpson Manufacturing is thinking about profitability while it works through higher steel costs and uneven housing demand.
For you, that guidance becomes a practical reference point for watching execution on pricing, mix and cost control. If volumes remain soft or competitive pressure in fasteners intensifies, holding that 20% area margin could become harder, which would feed directly into how investors think about the durability of the current earnings profile and any future catalysts tied to capital returns.
Analysts currently map Simpson Manufacturing's trajectory to US$2.7b in revenue and US$433.9 million in earnings by 2029. This forecast is based on an assumed 3.3% yearly revenue growth rate and an earnings increase of about US$55 million from US$378.9 million today.
Uncover how Simpson Manufacturing's fair value indicates a 10% potential upside to its current price, which could narrow quickly if sentiment shifts toward Simpson Manufacturing.
Exploring Other Perspectives
Five fair value estimates from the Simply Wall St Community span a wide band, from US$73.50 to US$219, so opinions on Simpson Manufacturing’s worth are clearly all over the map. You are weighing that dispersion against risks from softer construction activity and pricing pressure, plus potential catalysts in modular building and code driven demand. Explore those contrasting viewpoints before you commit fresh capital.
Explore 4 other Simpson Manufacturing fair value estimates, including one that suggests as much as 63% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Simpson Manufacturing research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Simpson Manufacturing. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Simpson Manufacturing's overall financial health at a glance.
Looking for more investment ideas beyond Simpson Manufacturing?
Once you have a view on Simpson Manufacturing, it can help to compare it with other opportunities that line up with your risk tolerance, income needs and appetite for underappreciated stories. The Simply Wall St Screener can narrow that universe quickly so you spend time assessing a focused set of stocks rather than scrolling through tickers without a plan.
- If you want income potential with an emphasis on resilience, consider companies that currently offer strong yields by reviewing our 6 dividend fortresses.
- For readers who care most about financial strength and balance sheet quality, focus on businesses that pair solid fundamentals with lower risk using this curated list of solid balance sheet and fundamentals (24 results).
- If you prefer opportunities that are off most investors’ radar, concentrate on lesser known stocks with strong fundamentals through our hand picked 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com