


EN
What Grupo Cibest Holders Saw Early
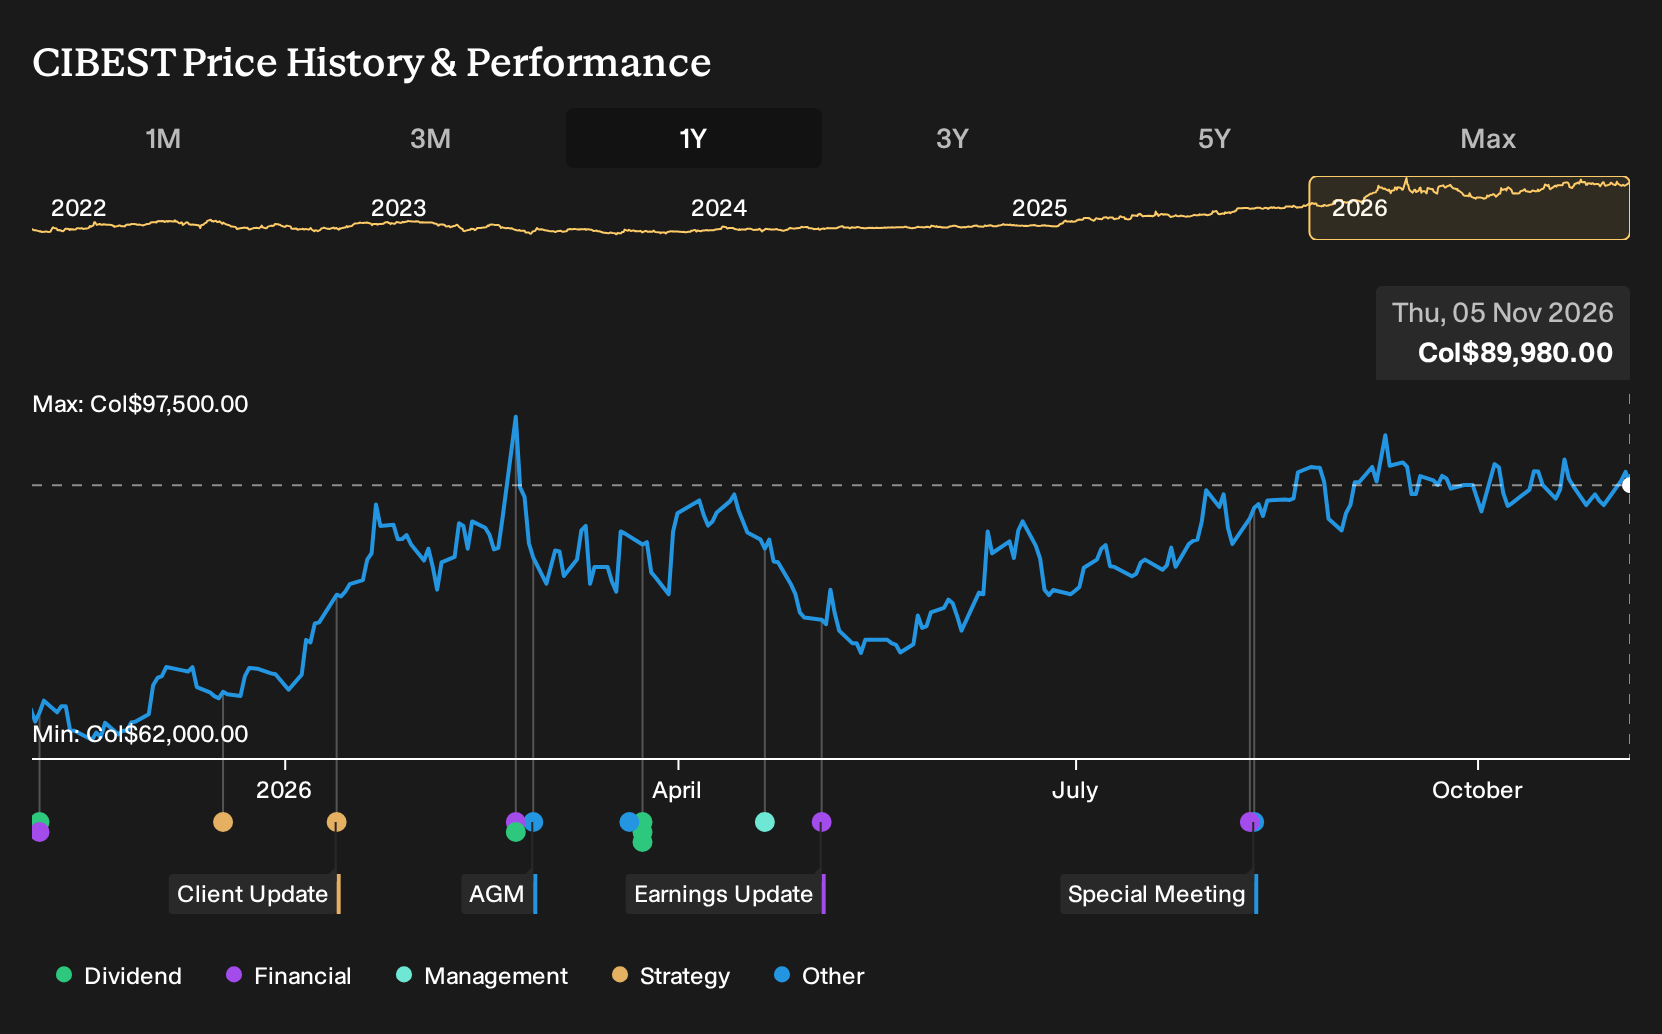
Nequi’s push toward breakeven and rapid loan expansion turned from theory into hard numbers when Grupo Cibest reported Q2 2026 net income of COP 2,816,097m on COP 7,384,517m of revenue, with net margin at 38.1%. For Grupo Cibest shareholders, the return over the past year was 43.2%, including dividends. If you had bought before this acceleration showed up, what exactly did you have to believe about digital banking and profitability back on 5 November 2025?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
If the move has made Grupo Cibest harder to judge, start where the gap is still open and scan 229 high quality undervalued stocks.
The Two Stories Investors Had To Choose Between On Grupo Cibest
The shares cost COP64,800 at the start of the period, so anyone looking at Grupo Cibest then had to decide which story felt more realistic.
The bullish Narrative pointed to a Fair Value of COP168,638. That view leaned on Nequi reaching breakeven by year-end 2025 with five-fold loan growth over 12 months and scalable digital platforms supporting a future P/E assumption of 33.3x.
The more cautious Narrative put Fair Value at COP57,045. It still expected Nequi to aid customer and fee growth, but focused on risks from rising operational and compliance costs and a future P/E assumption of 12.5x.
What The Results Changed For The Grupo Cibest Thesis
The clearest update came from the Q2 2026 report. Grupo Cibest booked COP 7,384,517m in revenue and COP 2,816,097m in net income, compared with COP 5,859,999m and COP 1,682,340m a year earlier, and net margin moved from 28.7% to 38.1%. That pattern broadly supported the view that argued for stronger profitability.
The key lesson is about which metric you watch. The whole debate focused on whether digital banking would lift Grupo Cibest’s margin. For any other lender with a similar story, track net income and reported net margin together and see if digital expansion actually shows up in those two lines.
What Today's Grupo Cibest Price Already Expects From Digital
Grupo Cibest now trades at COP89,980 and the selected Narrative’s Fair Value sits below that level. The author therefore sees the recent move over the past year as ahead of their own valuation work.
The Narrative turns on funding costs, credit quality and digital returns. For today’s price to hold, a buyer has to judge that digital growth keeps converting into earnings without a jump in cost of risk or operating expenses.
"The main thing that has to go right is that Grupo Cibest keeps translating its digital ecosystem growth, including Nequi's growing loan book and Wompi's transaction volumes, into sustainable profitability without a step up in group cost of risk or operating expenses."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Which Company Could Surprise You Next?
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 38% below our estimate - helps clients run complex user research, safety investigations and regulator responses together.
- Company 2 - 17% below our estimate - extends antibiotic bone graft technology into additional infection cases and shorter treatments.
- Company 3 - 28% below our estimate - ties subscription software and AI tools directly to rising cloud usage by customers.
Three companies from the same screener. Open every one of the 192 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com