


EN
How Investors Are Reacting To Rexford Industrial Realty (REXR) Portfolio Sale Plan
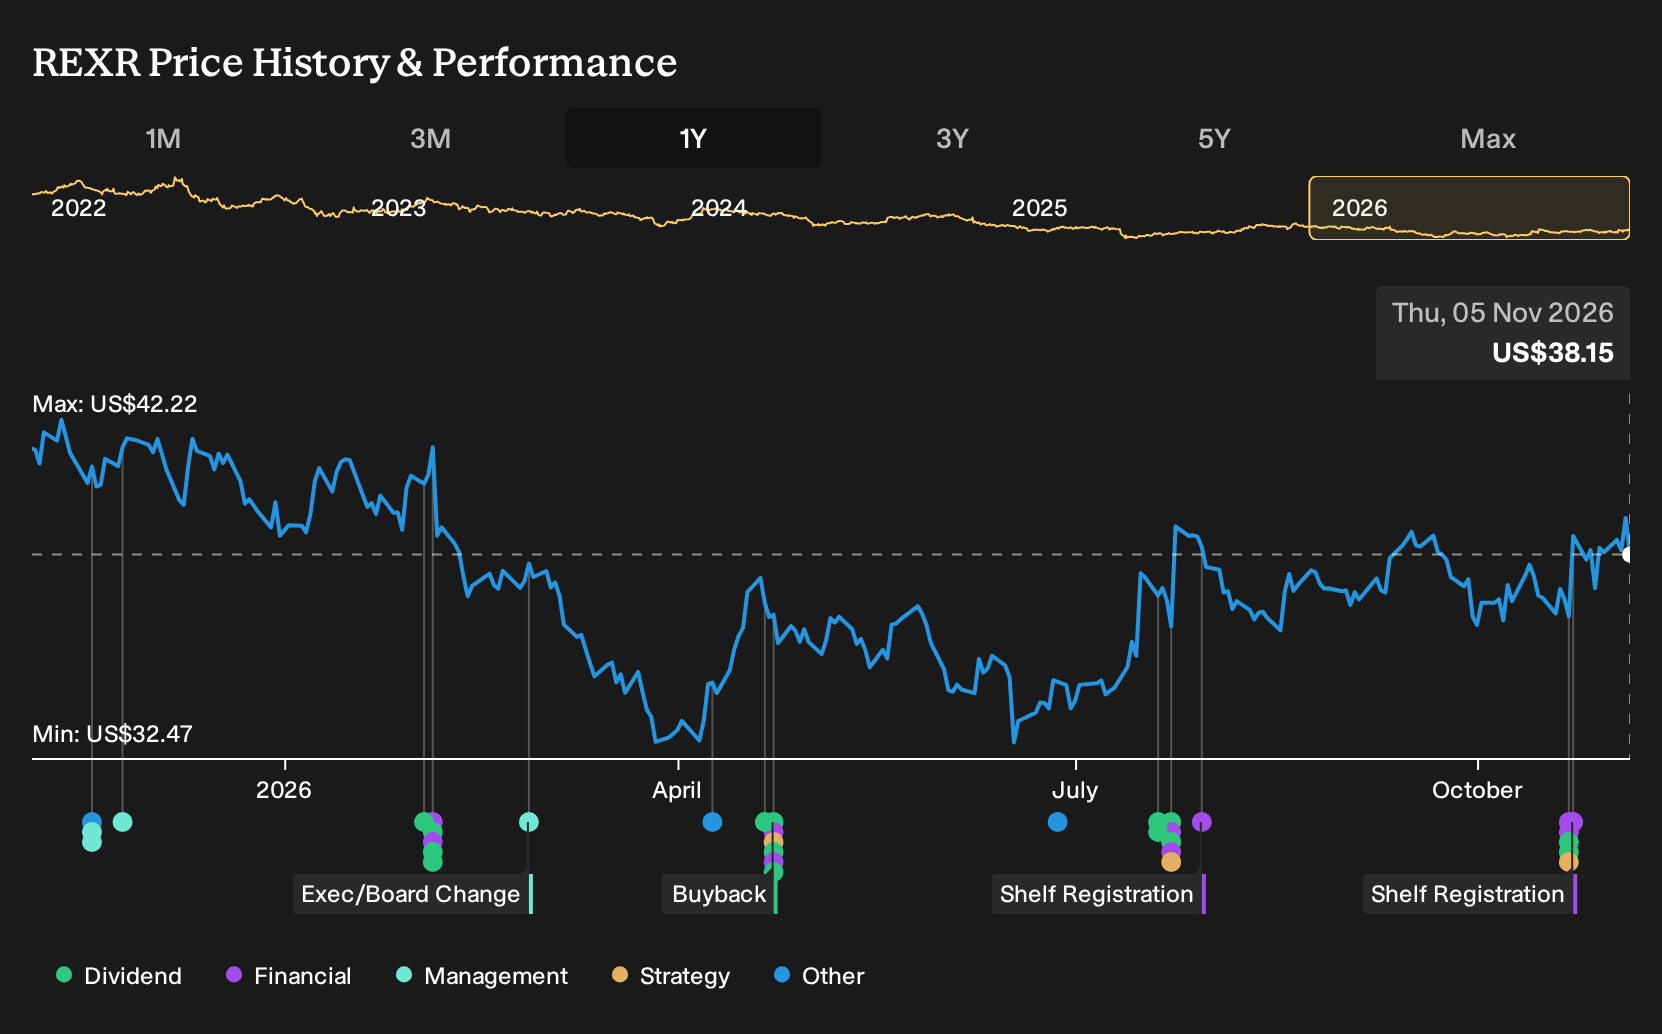
- Rexford Industrial Realty has completed repurchases of 2,801,307 shares for US$100.01 million under its April 23, 2026 buyback plan, and has also sold a US$1.2b industrial portfolio to EQT Real Estate while lifting its total 2026 asset sale target to a range of US$1.5b to US$2b.
- The combination of completed buybacks and a larger disposition program signals Rexford Industrial Realty reallocating capital away from certain properties and into what management views as higher priority uses, while institutional buyers show clear interest in Southern California industrial assets at current valuations.
- We will look at how Rexford Industrial Realty's expanded US$1.5b to US$2b asset sale plan reshapes the existing investment narrative.
Compare Rexford Industrial Realty's capital recycling moves with a curated set of industrial-focused peers by scanning list of solid balance sheet and fundamentals (24 results) for potential alternatives in the same theme.
Rexford Industrial Realty Investment Narrative Recap
For a shareholder in Rexford Industrial Realty, the thesis usually hinges on belief in infill Southern California industrial scarcity, the value of repositioning older assets, and disciplined use of the balance sheet. The recent US$1.2b portfolio sale and progress on buybacks sit on top of that. They do not change the need for leasing to absorb the 3.5 million square feet pipeline after 2026.
The near term swing factor is whether weaker cash re leasing spreads, guided to a 10% to 15% decline in 2026 with similar pressure indicated for 2027 and 2028, stabilize. The main risk is that rental headwinds and asset sales together reduce net operating income faster than Rexford Industrial Realty can replace it through redevelopment, repositioning and share count reduction.
The asset disposition program, lifted to US$1.5b to US$2b of planned sales, is the announcement that matters most for this latest news. Management has already completed or contracted about US$1.5b of those sales, at around a 5.5% stabilized yield on the properties sold, according to prior guidance.
This creates a tight execution test. Rexford Industrial Realty is leaning on higher return interior upgrades, lease up of the 3.5 million square feet pipeline that is estimated at US$50 million to US$60 million of annual NOI, and balance sheet work including planned repayment of roughly US$1b of 2027 debt and sizeable repurchases. If leasing or rent trends disappoint, the income lost on sold properties and the dividend coverage concerns could become more visible to investors.
Analysts expect Rexford Industrial Realty's revenue to trend to US$937.4 million and earnings to US$270.0 million by 2029, which assumes revenue declines of 1.9% a year and an earnings move from a loss of US$400.6 million today to a profit, a swing of about US$670.6 million.
Uncover why Rexford Industrial Realty's fair value indicates a 6% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster in a tight US$35.78 to US$40.31 range, yet your own view on Rexford Industrial Realty might shift once you factor in lease spread pressure, the large asset sale program, and the reliance on that 3.5 million square feet pipeline. Investor opinions can differ sharply, so explore several alternative viewpoints before deciding how this story fits your portfolio.
Explore another Rexford Industrial Realty fair value estimate, including one that suggests there may be up to 6% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Rexford Industrial Realty research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Rexford Industrial Realty. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rexford Industrial Realty's overall financial health at a glance.
Looking for more investment ideas beyond Rexford Industrial Realty?
If the Rexford Industrial Realty story has you thinking about portfolio balance and fresh opportunities, use the Simply Wall St Screener to explore a wider range of businesses that might fit your risk profile and income needs.
- For investors who want potential upside while still considering financial quality, review a curated set of companies with robust fundamentals through the 21 high quality undiscovered gems.
- If capital preservation and steadier profiles matter most to you, filter for businesses with lower risk scores by using the 32 resilient stocks with low risk scores.
- For those who prefer cash returns today, focus on resilient payers by checking out the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com