


EN
Is INFICON Holding (SWX:IFCN) Undervalued On Its Raised 2026 Guidance?
INFICON Holding (SWX:IFCN) recently raised its full year 2026 earnings guidance, now targeting sales of US$820 million to US$850 million and an operating income margin of 21% to 22%.
The sharper earnings outlook comes after a volatile stretch for INFICON Holding’s stock, with the share price falling 23.7% over the past month and 13.2% over 90 days, even though the year to date share price return is 45.3% and the 1 year total shareholder return is 62.9%. This points to strong longer term momentum despite recent pressure as investors reassess growth expectations and risk.
Scan how INFICON Holding compares with other potential breakout opportunities by reviewing our hand picked list of 229 high quality undervalued stocks.
INFICON Holding now trades well below its recent peak, even as management lifts its 2026 targets. Is this swing mainly about sentiment resetting, or does it flag a disconnect with what the business is actually earning?
Most Popular Narrative: 25% Undervalued
INFICON Holding last closed at CHF151.40, while the most followed narrative points to a fair value of CHF202.11, leaving a sizeable gap between price and the modelled worth of the business.
Record semiconductor orders through 2026, described by management as the steepest ramp the company has seen and supported by broad AI driven data center and memory investment, point to continued utilization of INFICON Holding sensors and software across more tools and fabs. This can underpin future revenue, operating margin leverage and cash flow.
See why 6 investors see INFICON Holding as 25% undervalued.
Result: Fair Value of CHF202.11 (UNDERVALUED)
Still, INFICON Holding’s story can change quickly if trade barriers intensify and weigh further on margins, or if semiconductor investment cools and order momentum softens.
Find out about the key risks to this INFICON Holding narrative.
Another View on INFICON Holding’s Valuation
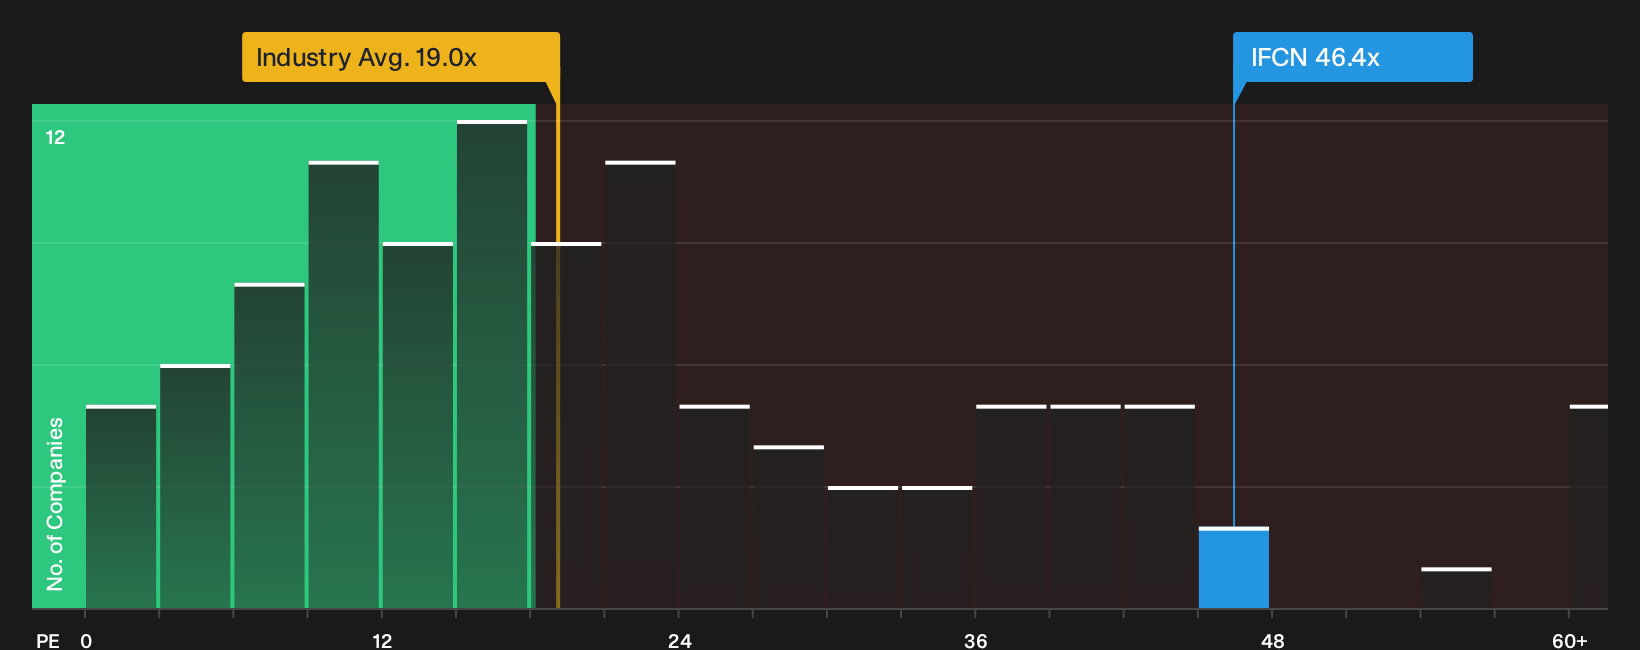
On simple earnings multiples, INFICON Holding looks expensive. The current P/E of 46.4x is higher than the European Electronic industry on 20x and above a fair ratio of 38.9x that the market could move towards. This points to valuation risk if sentiment cools or growth assumptions are revised.
That gap leaves you weighing a richer current multiple against the underpriced fair value story, and deciding which signal should matter more for your own process.See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If you are unsure whether INFICON Holding’s current situation represents an opportunity or a warning signal, consider reviewing the numbers yourself before market sentiment changes again. To assess both potential risks and possible benefits side by side, start with 3 key rewards and 1 important warning sign.
Looking for more INFICON Holding sized ideas?
Do not stop with a single stock story. Broader context across different types of companies can sharpen judgement and help you spot patterns earlier than the crowd.
- Target steady compounding by scanning a curated set of income opportunities using the 234 dividend fortresses.
- Hunt for mispriced potential where quality and valuation intersect through the 591 high quality undiscovered gems.
- Prioritise resilience and sleep better at night by checking companies screened for durability using the 213 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com