


EN
Intuitive Surgical (ISRG) Moved, What Is Catching Investors’ Attention?
Intuitive Surgical (ISRG) has been in focus after analysts raised earnings estimates and maintained a Zacks Rank #2 rating, while the board added Humana executive Aaron Martin ahead of his 2027 start.
Recent trading reflects that optimism. Intuitive Surgical’s share price has rallied, with a 7 day return of 8.45% and a 90 day share price gain of 23.68%. However, the year to date move is still down 16.63%, while the 3 year total shareholder return of 68.84% points to stronger long run momentum than the 1 year total shareholder return decline of 16.34%.
Scan for other robotics and healthcare leaders showing similar earnings momentum by comparing Intuitive Surgical with the hand-picked 89 robotics and automation stocks in this sector.
After that sharp rebound yet still weak 1 year return, the real tension around Intuitive Surgical now sits in the price tag. Is most of the upside already in the rear-view, or still ahead?
Most Popular Narrative: 26% Undervalued
On Simply Wall St, the most followed narrative pegs Intuitive Surgical’s fair value at $630.48, well above the last close of $468.52, which puts the recent rebound in a different light and raises the question of whether the market is still under-pricing the story.
I have followed ISRG since 2003 when it was brought to the investing club I had just joined. I tried to analyze ISRG with the BetterInvesting SSG methodology that I had been introduced to and I could not get it in the buy zone. Wiser heads in the club prevailed and we started a position at around $48 a share and continued to add to the position. In 2005 ISRG was trading at over $200 a share and I was getting nervous. I convinced the club to place a trailing stop on ISRG. The price continued to increase and reached $393 a share. Then ISRG stock price started to drop and it got as low as $200 a share. Our trailing stop worked like a charm and we were sold out of the club position at just above $360 a share. I tried to convince the club to reinvest in ISRG at $200 a share; they decided not to, but I did. I describe it as riding the lightning. I have bought and sold ISRG at least twice since then and watched the share price increase to over $1000 a share twice before doing a 3 for 1 stock split, first in 2017 and then again in 2021. Did I mention no debt?
See why 10 investors see Intuitive Surgical as 26% undervalued.
According to pbco, who authored this narrative, that $630.48 fair value is built on a few core pillars that matter for anyone looking at Intuitive Surgical today. The business is described as a razor blade model, where each da Vinci or Ion system in the field drives a recurring stream from instruments, accessories, and services, rather than relying only on one-off hardware sales.
Reported figures back that revenue mix up. As of 31 December 2025, 59.8% of sales came from instruments and accessories, 24.58% from systems, and 15.62% from services, according to FactSet Data Systems cited in the narrative. That pattern aligns with a recurring usage model, where installed robots create ongoing demand for proprietary tools and support.
The patent portfolio is another part of the story. The narrative notes that Intuitive Surgical has 7,015 patents globally, with 4,016 granted and more than 78% active, with the United States, Europe, and Japan as key jurisdictions. In that context, pbco argues that rivals need not just competing robots but also their own full catalog of compatible instruments and accessories, since Intuitive Surgical’s patents restrict cross-usage.
Alongside that qualitative angle, Intuitive Surgical’s own fundamentals show earnings growth of 17.5% per year over the past 5 years and current annual revenue of about $11.6b with net income of roughly $3.0b. Forecasts in the dataset point to earnings expected to grow 15.18% per year and revenue projected to increase around 11% annually, which supports the idea of a profitable, growing franchise rather than a purely speculative robotics play.
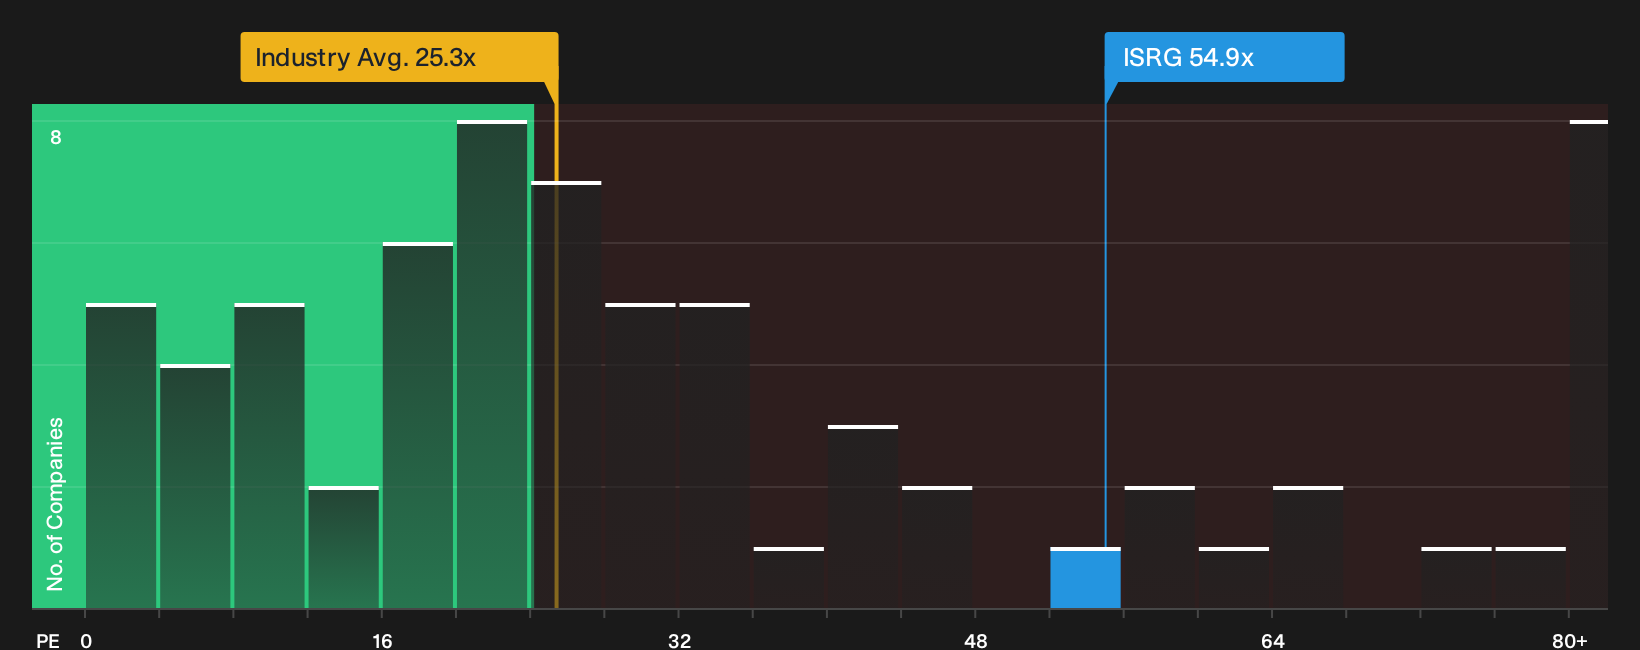
That said, the narrative’s 26% discount to fair value sits against some tougher context in the Statements Data. The stock is described as expensive on a P/E of 54.9x versus both the Medical Equipment industry average of 25.3x and a fair P/E estimate of 38.1x, while return on equity of 18.4% is labelled low under the framework used here. Earnings growth in the most recent year at 7.7% also trails the 5 year pace of 17.5% per year and the sector’s 15.1% figure, and current net profit margins of 25.5% are below last year’s 28.6%.
Investors weighing this narrative therefore have two lenses. The community storyline, built on patents, recurring usage, and a long operating history, frames Intuitive Surgical as materially undervalued versus $630.48. The metrics-based checks highlight a premium P/E, softer recent margin trends, and returns sitting below the 20% threshold used in this framework, which may help explain why the market has not fully embraced that narrative fair value.
Result: Fair Value of $630.48 (UNDERVALUED)
Still, the Intuitive Surgical story could be knocked off course if patent protections weaken or if legal and regulatory pushback around its ecosystem intensifies.
Find out about the key risks to this Intuitive Surgical narrative.
Another Look At Intuitive Surgical’s Price Tag
That $630.48 fair value from the community narrative leans on cash flows and moat. The simple P/E picture for Intuitive Surgical tells a different story. The shares trade on 54.9x earnings versus a 25.3x industry average and a 38.1x fair ratio estimate, which points to a rich valuation and less room for error if growth cools further. Which lens feels more useful for you as an investor?
To see how that kind of earnings multiple can re-rate if sentiment or results change, and what it might mean for your risk tolerance, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If all of this leaves you sensing mixed sentiment around Intuitive Surgical, treat that as a prompt to move fast and stress test the numbers yourself, starting with the 3 key rewards.
Looking for more investment ideas beyond Intuitive Surgical?
If Intuitive Surgical has sharpened your interest, do not stop here. Broader context across other quality opportunities can tighten your process and reveal fresh angles.
- Target resilient balance sheets by scanning companies on the list of solid balance sheet and fundamentals (24 results) that combine financial strength with solid fundamentals.
- Hunt for mispriced quality by reviewing the 42 high quality undervalued stocks that highlight stocks with strong fundamentals trading below their estimated worth.
- Spot early-stage potential by checking the 9 elite penny stocks with strong financials that filter for smaller companies backed by stronger financial profiles than the usual microcap universe.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com