


EN
What British American Tobacco Doubters Missed
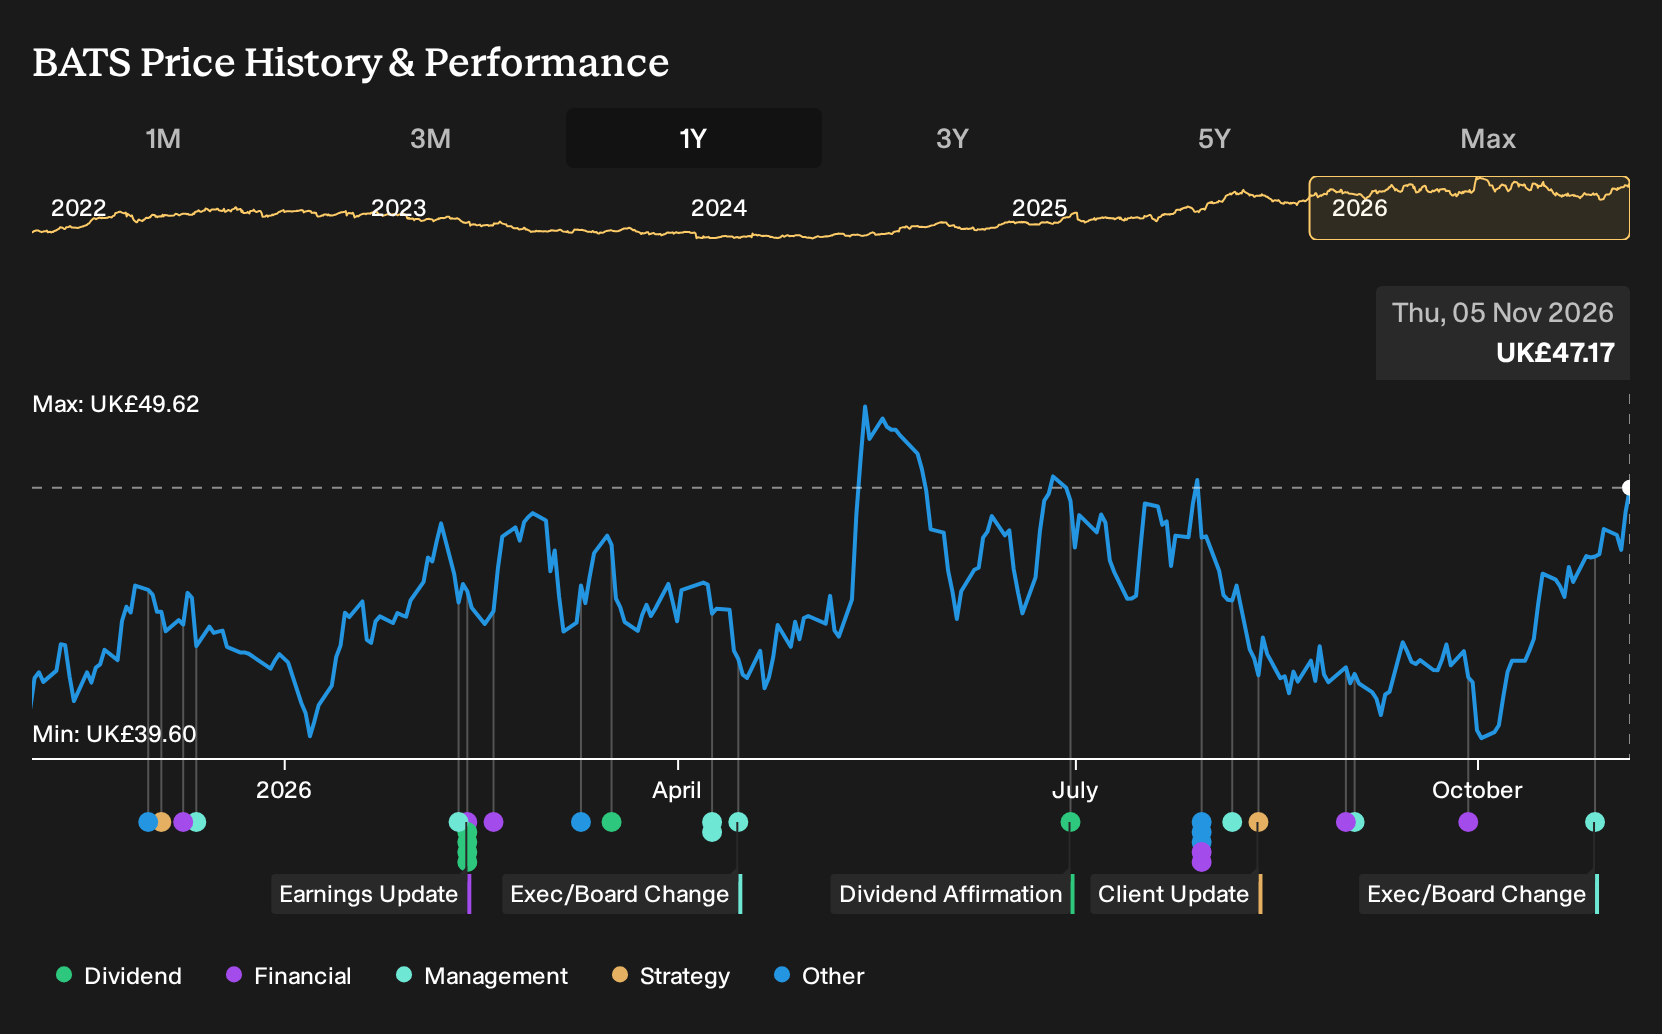
British American Tobacco spent the year in the headlines for factory closures, job cuts, and a hard push into smokeless products, yet patient holders saw a very different scoreboard. For British American Tobacco shareholders, the return over the past year was 20.0%, including dividends. If you had bought on 5 November 2025, you were stepping into a situation defined by a clash between bullish growth stories and harsh regulation. What does that gap between noisy risk and solid outcome really say about the business you were buying into?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
The easy part of this move is behind British American Tobacco. Zero in on 15 high quality undervalued stocks for companies trading below our estimates.
The Two British American Tobacco Stories Investors Had To Weigh
The shares cost £41.42 at the start of the period, and British American Tobacco sat between two sharply different narratives that both looked plausible on the available data.
On the bullish side, the fair value was £51, or 23% above the start price, built on the idea that modern oral products could more than double in two years and reshape revenue and margin potential.
The bearish view put fair value at £26.50, or 36% below the start price, and focused on accelerating global regulation and cultural pushback against nicotine as a long-run threat to cash generation.
What The Evidence Did To The British American Tobacco Argument
The clearest development was British American Tobacco’s 2026 restructuring plan that cut 5,500 jobs and outsourced 3,500 roles, aimed at cost savings and a faster tilt toward smokeless products. This supported the more optimistic efficiency story, but the reported numbers told a tougher tale. Revenue moved from £12,069m to £12,235m, while net income and net margin both fell, which supported the cautious case.
The hinge assumption was not just growth in new products but the quality of that growth. When judging another business with a similar promise, track whether higher sales arrive with falling or rising net margin in the next set of results.
What British American Tobacco’s Price Now Asks You To Believe
Today British American Tobacco trades at £47.17. The selected Narrative’s Fair Value sits below that level, reflecting a cautious view that the current quote already prices in much of the cash generation story.
The argument leans on smokeless growth and Fit2Win savings, while seeing uneven heated product performance as the key swing factor. A buyer today is effectively assuming smokeless momentum offsets cigarette volume and tax pressure. How does that square with the risk that heated weakness and cost execution problems strain margins and cash?
"While New Categories are positioned to grow revenue in the mid teens, the explicit expectation of a low double digit revenue decline in Heated Products after inventory adjustments in Japan and stronger value segment competition suggests that the smokeless transition is uneven and may weigh on group margins and cash generation rather than supporting a smooth earnings trajectory."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
British American Tobacco And A Parallel Move
Once you have unpacked British American Tobacco, it is natural to look sideways. Your watchlist does not have to stay inside nicotine.
Consumer habit is the common thread. People reach for quick refreshments as reliably as they reach for cigarettes in familiar daily moments.
Another large consumer group leans into that pattern, selling drinks and snacks that support similar routines.
It focuses on steady everyday demand and regular cash returns to holders over time.
If British American Tobacco is one way to monetise habit, this peer hints at a different flavour of the same idea.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 40% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com