


EN
Atlanta Braves Holdings (BATR.K) Stock Looks Fully Priced Despite Its 65% Run
Atlanta Braves Holdings has delivered a strong multi year share price run. The real question for anyone looking at the stock today is how well that market value lines up with the revenue the business actually generates.
- Over the past 5 years the share price has gained 65.2%, which puts more focus on whether that climb is supported by the company’s sales base.
- Recent revenue growth tied to higher attendance, postseason baseball and mixed use rental income can support a different view on how much investors are willing to pay for each dollar of sales and how stable that sales mix might be.
- There is a second opinion on Atlanta Braves Holdings worth weighing. See what analysts think Atlanta Braves Holdings's shares could be worth.
The issue now is whether the current Atlanta Braves Holdings share price is justified by its sales when set against the Fair Ratio benchmark.
If you want more context on how Atlanta Braves Holdings fits into the wider picture of balance sheet strength and underlying fundamentals, it can help to line it up against solid balance sheet and fundamentals stocks screener (24 results).
Has Atlanta Braves Holdings Run Too Far on Sales?
For a sports and entertainment business like Atlanta Braves Holdings, the P/S ratio lines up more cleanly with how investors weigh the revenue engine against the current share price.
The stock trades on a P/S of 4.2x, compared with about 1.1x for the broader Entertainment industry and roughly 3.6x across closer peers. Despite Q3 2026 revenue progress from higher attendance, postseason baseball and mixed use rental income, that gap suggests investors are already paying a richer price for each dollar of sales than both the sector backdrop and peer set. On Simply Wall St’s Fair Ratio framework, which adjusts the P/S multiple for the company’s growth profile, profitability, size and risk, the current level screens as overvalued and the model flags an especially wide premium because it heavily penalises the recent free cash flow losses.
The Fair Ratio output is better read as a warning that Atlanta Braves Holdings looks very expensive on this revenue based lens rather than as a precise target for where the P/S should land. For readers, the key question is whether the quality and durability of the ticketing, media and mixed use income streams truly justify such a marked sales multiple premium. Explore the numbers behind Atlanta Braves Holdings's P/S valuation.
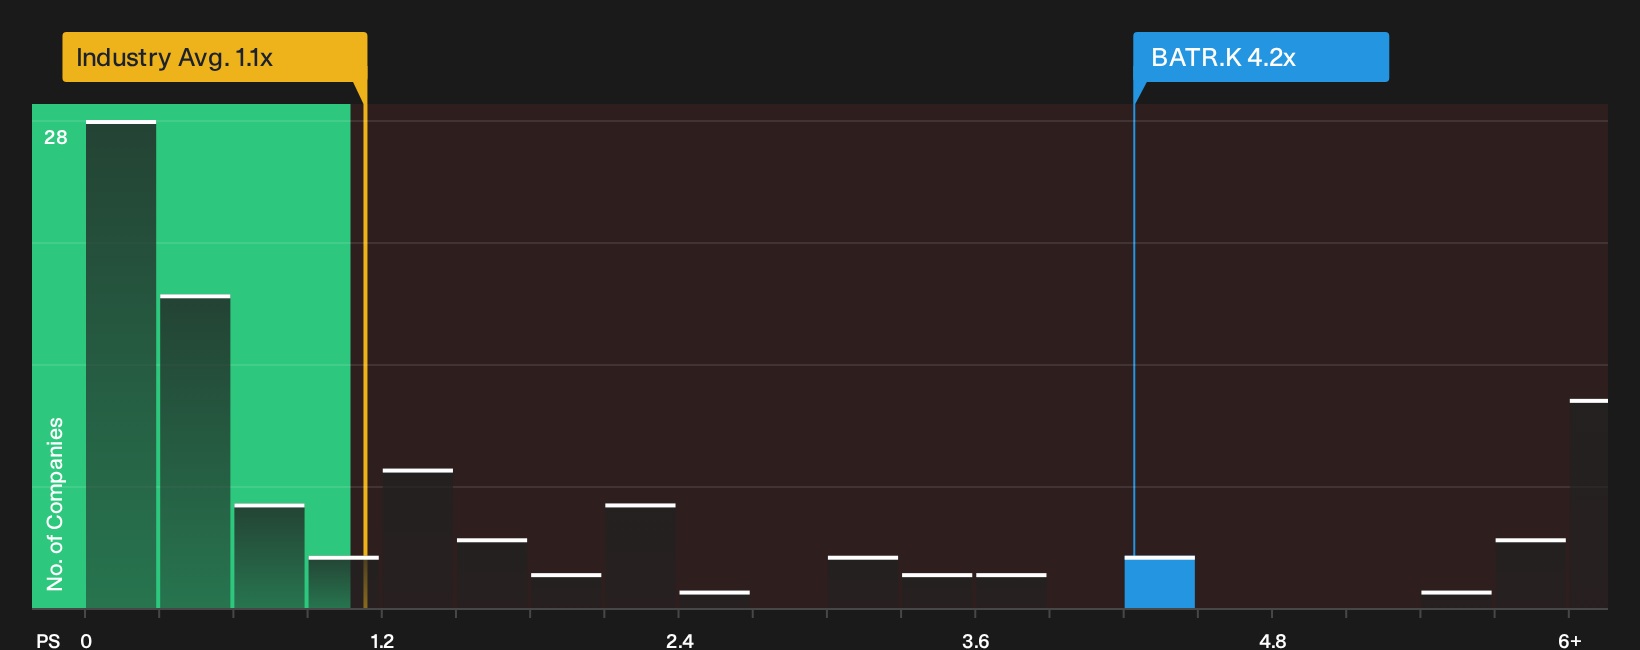
The Atlanta Braves Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Atlanta Braves Holdings valuation puzzle leaves off by spelling out which future paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than it is today on the market. Each scenario focuses on the assumptions that sit behind its view of fair value so you can later compare those signposts with the actual results as they come through.
Atlanta Braves Holdings splits opinion between investors who see more upside in the franchise and real estate mix and those who think rising costs already crowd that out.
Bull case: 21% undervalued
"The shift to BravesVision as an owned media platform, with management indicating it is on pace to meet or exceed prior local rights economics…"
Discover why this Narrative puts Atlanta Braves Holdings at 21% undervalued.
Bear case: roughly fairly valued
"The very large short interest level that has built around concerns about a potential 2027 MLB lockout, combined with already rising baseball operating and BravesVision expenses…"
Explore why this Narrative puts Atlanta Braves Holdings at roughly fairly valued.
One unresolved question for Atlanta Braves Holdings
All the valuation work on Atlanta Braves Holdings still leaves one issue hanging in the background. This is because Simply Wall St’s broader checks have flagged specific areas of concern that deserve a closer look from you. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com