


EN
Japan Airlines (TSE:9201) Lifts Its Dividend On Half Year Results, Is The Stock Still Cheap?
Japan Airlines (TSE:9201) has just put shareholder returns in focus after reporting half year results and adjusting its dividend plans, combining a slight second quarter payout lift with detailed guidance on bond type share distributions.
Recent trading has been choppy. The share price fell 5.0% over the last day, although the 7 day share price return of 5.5% and 30 day gain of 8.3% suggest buyers have been leaning back in as the dividend and half year results hit the market.
See how other travel and transport stocks are handling shareholder returns alongside earnings pressure by checking our curated 29 high quality undervalued stocks featuring companies with solid cash generation and balance sheets.
Japan Airlines now trades only slightly below its published price target after a sharp pullback and a strong month. That sets up a simple choice: step in after this wobble or wait for a wider gap to open up.
Price-to-Earnings of 13.4x: Is it justified for Japan Airlines?
Valuation on Japan Airlines now leans on a simple P/E story, with the shares at ¥3,260 trading on 13.4x earnings that screens cheaper than both domestic and wider Asian airline peers.
The P/E ratio links the current share price to earnings per share and helps you gauge how much investors are paying for each unit of profit. For a carrier like Japan Airlines, where profit cycles can be uneven and capital needs are heavy, that earnings multiple often shapes how much room the market gives management to handle volatility.
On the numbers provided, Japan Airlines is described as "trading at good value compared to peers and industry," and its 13.4x P/E sits below the Asian Airlines average of 14.1x. The same metric is also below a peer group average of 26.9x, and the estimated fair P/E of 18.9x points to a level the market could move towards if sentiment and earnings delivery line up with expectations.
Explore the SWS fair ratio for Japan Airlines.
Result: Price-to-Earnings of 13.4x (UNDERVALUED)
Still, the investment case around Japan Airlines can quickly look different if fuel expenses spike or if another external shock affects international travel demand.
Find out about the key risks to this Japan Airlines narrative.
Another View: Japan Airlines Through a Cash Flow Lens
There is a very different message when you switch from the P/E snapshot to the SWS DCF model. On that view, Japan Airlines at ¥3,260 is described as trading above an estimated future cash flow value of ¥1,437.22. That flags a possible overvaluation and raises a simple question for you: Which signal matters more, earnings or cash flow?
Look into how the SWS DCF model arrives at its fair value.
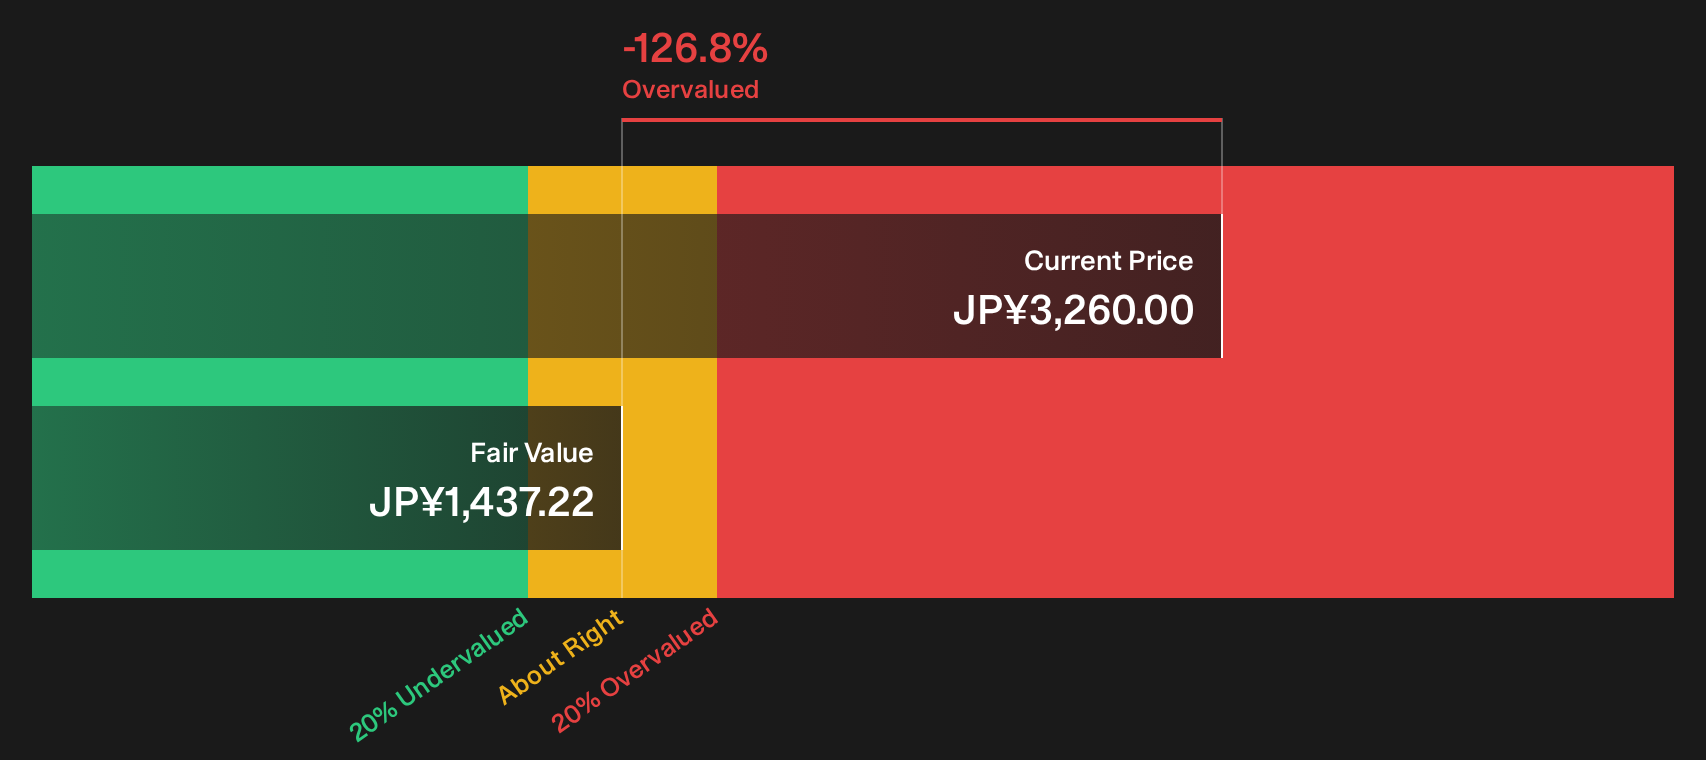
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Japan Airlines for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on value and cash flows can be hard to weigh, so move quickly, review the data for Japan Airlines yourself, and then lean on the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Japan Airlines?
If Japan Airlines has sharpened your focus on value and risk, do not stop here. Broaden your watchlist now or you will miss other clear opportunities.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (23 results) that filters for companies with stronger fundamentals and financial footing.
- Hunt for potential mispricing by reviewing a 74 high quality undiscovered gems that highlights quality businesses that many investors are still overlooking.
- Dial down volatility risk and concentrate on stability through a 21 resilient stocks with low risk scores tuned for companies with more durable risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com