


EN
Danaher (DHR) Won FDA Clearances, Is The Discount Too Cautious?
Danaher (DHR) has returned to investors’ watchlists after fresh FDA clearances for its Cepheid Xpert Hemorrhagic Fever Panel and Beckman Coulter Access MeMed BV assay reshaped the story around infectious disease and antimicrobial testing.
Recent FDA clearances and higher long term revenue guidance have arrived just as Danaher’s 90 day share price return of 10.54% and 30 day share price gain of 4.98% signal improving momentum, while the 8.23% one year total shareholder return contrasts with weaker five year total shareholder performance and suggests that sentiment has only recently started to recover.
Scan how Danaher’s diagnostics story compares with other lab and testing players by screening for list of solid balance sheet and fundamentals (24 results) that may also benefit from similar regulatory and healthcare trends.
Danaher now trades at a discount to both analyst targets and some intrinsic value estimates after a sharp recovery from the lows. Is the market fairly cautious on execution risk, or overly skeptical about the new diagnostics pipeline and long-term revenue guidance?
Most Popular Narrative: 13% Undervalued
Danaher’s most followed narrative pegs fair value at $259.90, above the last close of $226.34. This frames the recent FDA news against a longer term recovery thesis that leans on recurring diagnostics and tools demand.
The main factor that has to go right is that biologics and bioprocessing capacity investment, AI-linked life sciences demand, and advanced diagnostics growth translate into sustained core revenue expansion, despite pressures in areas such as respiratory testing and China pricing.
The current valuation and this narrative’s view that Danaher is fairly valued and bullish suggest that the share price already reflects meaningful long-term growth in high recurring revenue segments, disciplined M&A execution, and continued cash generation.
See why 82 investors see Danaher as 13% undervalued.
Result: Fair Value of $259.90 (UNDERVALUED)
Still, if respiratory testing remains weaker for longer or China pricing pressure deepens, Danaher’s recovery narrative could look more fragile than the current fair value implies.
Find out about the key risks to this Danaher narrative.
Another View: Danaher On Earnings Versus “Fair” Pricing
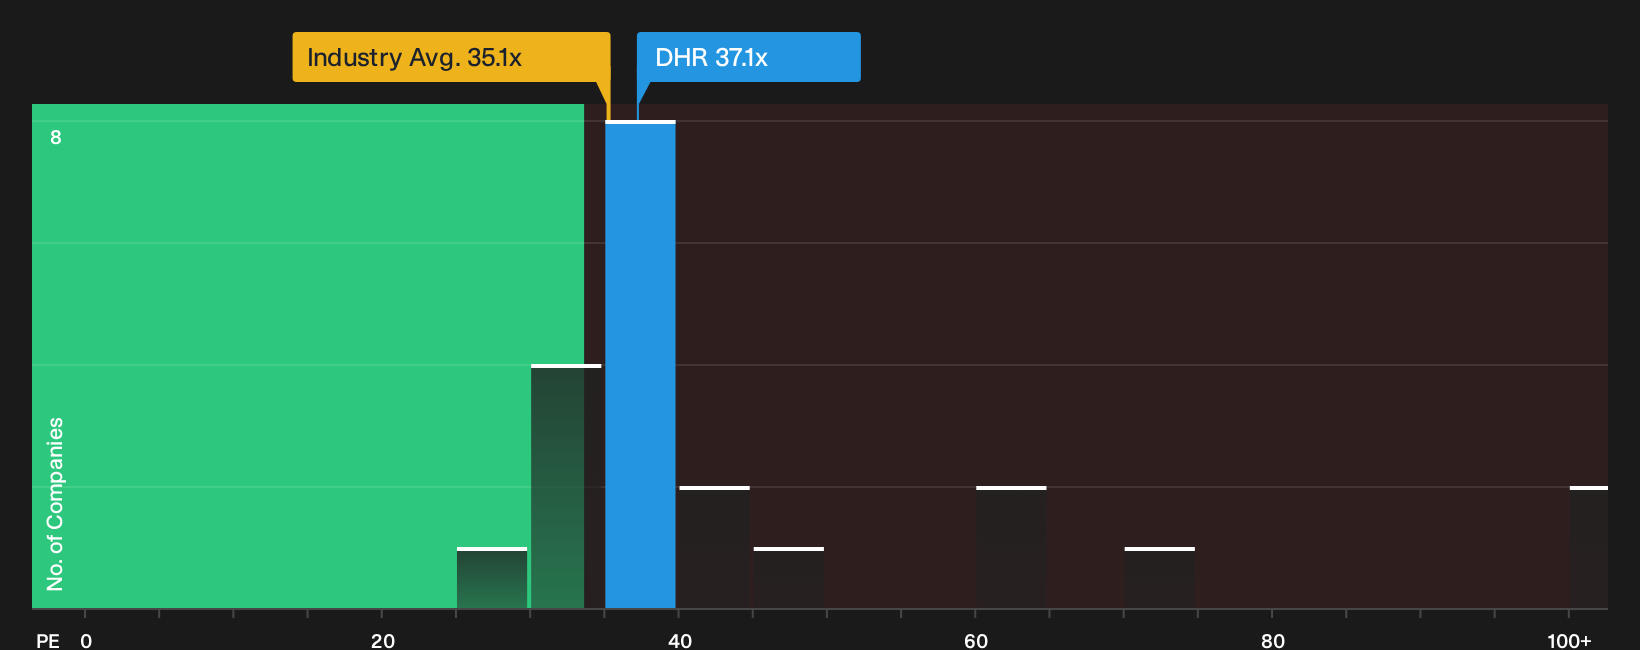
There is a different read on Danaher when you look at what investors are paying for earnings. The stock trades on a P/E of 37.1x, not only above the Global Life Sciences average of 35.1x but also above its own fair ratio of 35.2x. This points to a richer entry point and raises the question of how much execution risk you are really being paid for.
See what the numbers say about this price in more detail in our valuation breakdown, then weigh up whether Danaher’s current multiple matches your own expectations for the business. See what the numbers say about this price — find out in our valuation breakdown.
For a visual comparison of how Danaher’s valuation stacks up against peers on this earnings metric, review the latest P/E snapshot.
Next Steps
If this mix of optimism and caution around Danaher feels familiar, consider quickly stress testing the thesis against your own framework using 3 key rewards and 1 important warning sign.
Looking for more Danaher style investment ideas?
If Danaher has sharpened your thinking, do not stop with a single ticker. Use the Simply Wall Street Screener to uncover fresh ideas that fit your approach.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (24 results) that fit your quality checklist.
- Hunt for potential mispricing by reviewing the 42 high quality undervalued stocks that match your return and risk expectations.
- Prioritise income and resilience by focusing on the 6 dividend fortresses that align with your payout and stability goals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com