


EN
Millrose Properties (MRP) Stock Still Looks Undervalued On Its 14% Rebound
Millrose Properties has bounced over the past month even as its longer term share performance remains weaker, which puts fresh focus on whether the current price can still be explained by its earnings power. With recent headlines ranging from record income to a securities class action, the stock now invites a closer look at how its profits compare with what investors are paying.
- The share price has gained 14.4% over the past month. This brings up the question of whether recent momentum is supported by the level and quality of Millrose Properties’ earnings.
- Record net income alongside a new US$250m buyback program may support the view that the business can generate cash flows that matter for any earnings based valuation of the stock.
- Your read on Millrose Properties is one view; the desks covering it have another. See what analysts think Millrose Properties's shares could be worth.
The issue now is whether Millrose Properties’ current share price around US$26.50 is justified by its earnings when judged against the Fair Ratio benchmark.
If you want to test the same earnings question on a broader set of opportunities, line Millrose Properties up against 42 high quality undervalued stocks and compare the valuation story.
Is Millrose Properties Still Cheap on Earnings?
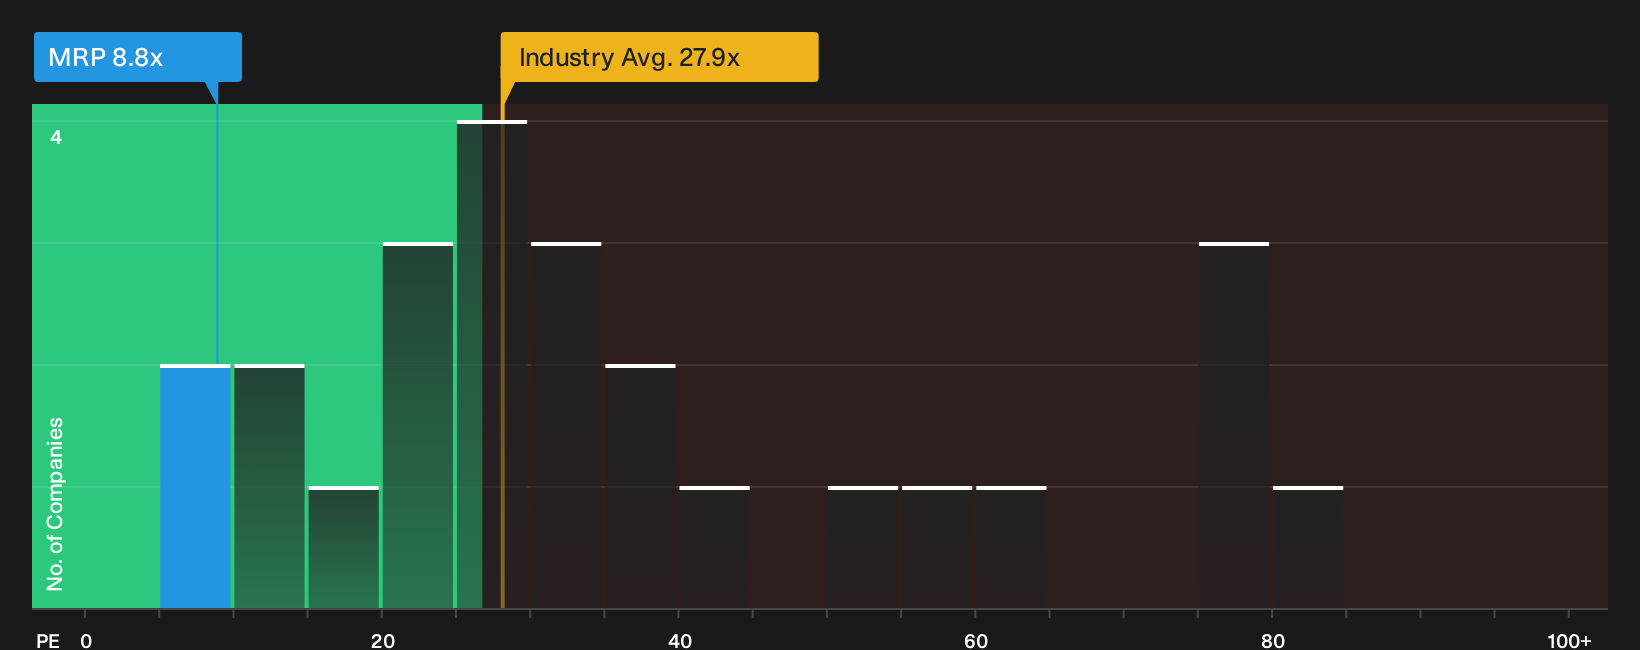
P/E suits Millrose Properties because earnings drive much of the story for a Specialized REIT. On that metric, the stock trades at about 8.8x earnings, which is well below the Specialized REITs industry average of roughly 15.6x and also under the wider peer group on roughly 18.6x. The Fair Ratio, which blends the company’s growth outlook, profitability profile, sector, size and risk, points to a higher earnings multiple than the one the market is currently assigning.
The recent securities class action over undisclosed leasing losses has clearly introduced an extra layer of perceived risk. Even so, the current P/E still values Millrose Properties at a discount to both its sector and peers on this framework. In that context, the earnings multiple screens as undervalued relative to what the Fair Ratio model suggests might be justified, which leaves room for investors to decide whether the legal and business model questions explain the gap or overshoot it. Explore the numbers behind Millrose Properties's P/E valuation.
The Millrose Properties Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Millrose Properties leaves off. Narratives spell out which combinations of future growth, margins and earnings would line up with a much higher or much lower price than today, and each one links its number to a clear view of how Millrose Properties' growth, profitability and risk profile might evolve, so you can return to those assumptions as fresh information comes through.
One of the top community narratives on Millrose Properties: 29% undervalued
"Expanding national relationships with 12 homebuilder counterparties and growing penetration of existing programs position Millrose to steadily increase option fee income…"
Discover why this Narrative puts Millrose Properties at 29% undervalued.
Millrose Properties' price is only one side of the decision
Before deciding how Millrose Properties fits into your watchlist, it helps to see where professional earnings projections line up against today’s multiples and legal questions. Explore where analysts expect Millrose Properties to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com