


EN
Is Cronos Group (TSX:CRON) Undervalued Following Its Third Quarter Earnings Beat?
Cronos Group (TSX:CRON) just posted third quarter 2026 results that beat earnings expectations, with revenue ahead of forecasts and positive net income, putting fresh attention on the stock’s recent run.
Investors have chased Cronos Group higher on the back of these results, with the share price gaining 6.09% in the last session and posting a 41.73% year-to-date share price return. Meanwhile, the 1-year total shareholder return of 50.72% and 3-year total shareholder return of 92.99% point to strong but uneven momentum when set against a 5-year total shareholder return that is still down 26.54%.
Scan how Cronos Group’s earnings surprise compares with other cannabis players by reviewing our curated list of list of solid balance sheet and fundamentals (5 results)
Bulls see Cronos Group’s earnings beat and cash rich balance sheet as support for the rally. Bears point to patchy long term returns and sector risk. Which side does the current valuation appear to favor?
Most Popular Narrative: 12% Undervalued
Cronos Group’s most followed thesis puts fair value at CA$5.93 per share, slightly above the last close at CA$5.23. This keeps valuation firmly tied to cash, capacity and earnings quality rather than just recent share price strength.
The main thing that has to go right is that Cronos Group sustains its brand leadership in categories like vapes and edibles while converting its cash-rich, debt-free balance sheet and recent acquisition in the Netherlands into durable free cash flow from Canada, Israel and other international markets, despite ongoing regulatory and pricing risks.
Using the net cash position of about US$827 million with no debt and ongoing share repurchases to selectively fund M&A, product development and international build-out, alongside six consecutive quarters of positive adjusted EBITDA and cash flow from operations, creates room for Cronos Group to keep shifting its mix toward higher margin business and potentially lift net margins and earnings.
See why 10 investors see Cronos Group as 12% undervalued.
Result: Fair Value of CA$5.93 (UNDERVALUED)
Still, the Israel anti dumping probe and any stumble at the fully planted GrowCo facility could quickly challenge the current Cronos Group undervaluation story.
Find out about the key risks to this Cronos Group narrative.
Another View on Cronos Group’s Valuation
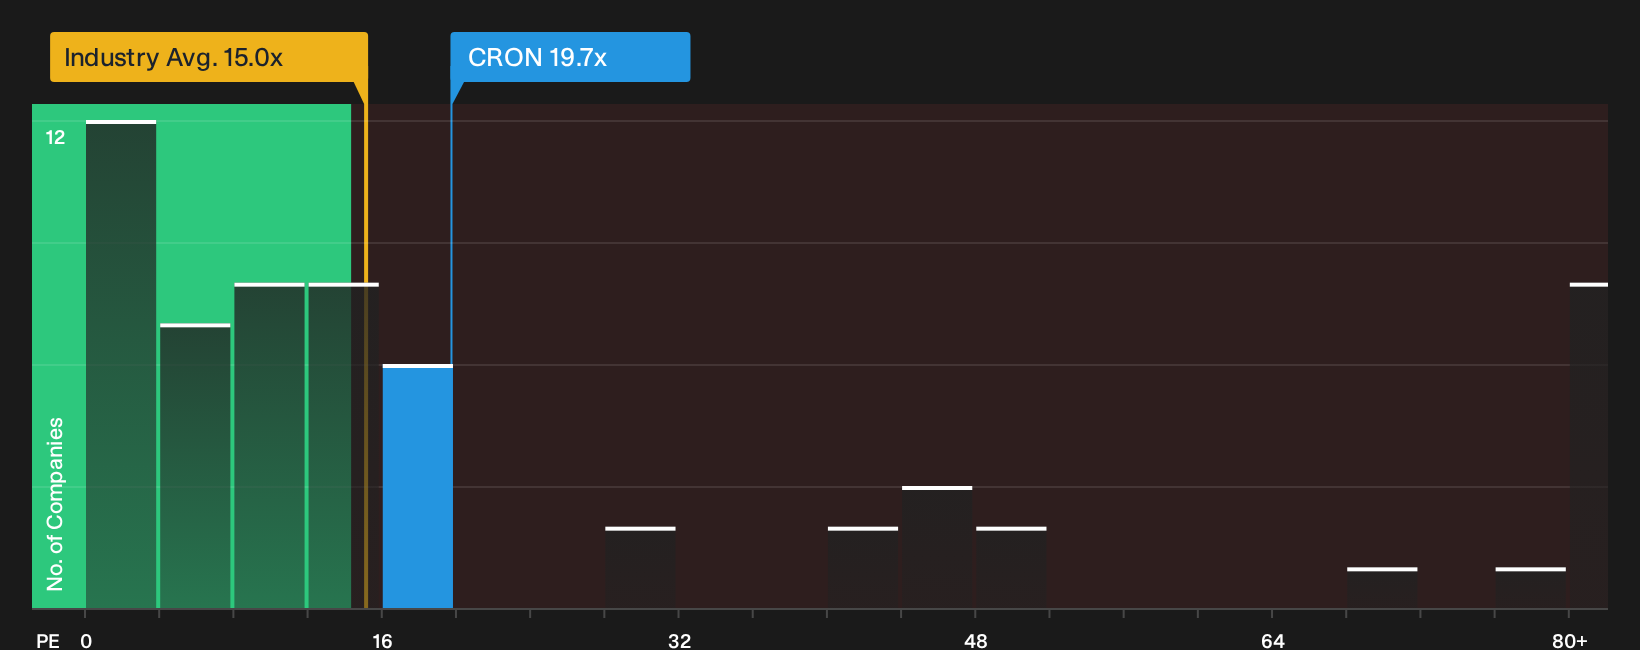
The first thesis presents Cronos Group as undervalued around a fair value of CA$5.93. The P/E picture looks more cautious. At 19.7x, the stock trades above the North American Pharmaceuticals industry on 16.1x, yet in line with its own fair ratio of 19.7x. This raises the question of whether that level is a reassuring anchor or a potential ceiling on further rerating.
For a closer look at how that earnings multiple compares in practice, and what it could indicate for valuation risk if sentiment changes, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Cronos Group is mixed, which is exactly why checking the underlying data yourself matters. If you want a quick starting point, take a look at the 3 key rewards.
Looking for more investment ideas beyond Cronos Group?
If Cronos Group has your attention, use that momentum. The right screen can surface opportunities you would not spot just scrolling tickers.
- Target resilient potential by scanning a curated set of companies with stronger balance sheets and fundamentals through the list of solid balance sheet and fundamentals (5 results).
- Hunt for pricing gaps by reviewing a focused selection of 6 high quality undervalued stocks that combine quality fundamentals with appealing valuations.
- Strengthen your income stream by checking companies in the 3 dividend fortresses that offer higher yields alongside stability metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com