


EN
Has CleanSpark (CLSK) Fallen Far Enough To Look Cheap On Sales?
CleanSpark has seen its share price fall sharply in recent months, which naturally puts the spotlight on whether the current valuation can still be explained by its sales. With the stock under pressure and sentiment swinging around recent news, the key issue for you is how much revenue the market is effectively paying for today.
- Over the past 5 years, CleanSpark shares have fallen 73.5%, which makes the price you see today heavily shaped by investors repeatedly revisiting what its sales are worth.
- Recent commentary highlights shrinking revenue alongside a sharp improvement in earnings and a net cash position of US$185.4m, a mix that can influence how much value investors are willing to assign to each dollar of sales.
- There is a second opinion on CleanSpark worth weighing. See what analysts think CleanSpark's shares could be worth.
For investors, the debate is whether the current CleanSpark share price is justified by its sales when set against the Fair Ratio benchmark.
If you are weighing whether CleanSpark’s recent slide leaves value on the table, it can help to compare that sales based story with a curated set of 42 high quality undervalued stocks.
Is CleanSpark Getting Expensive on Sales?
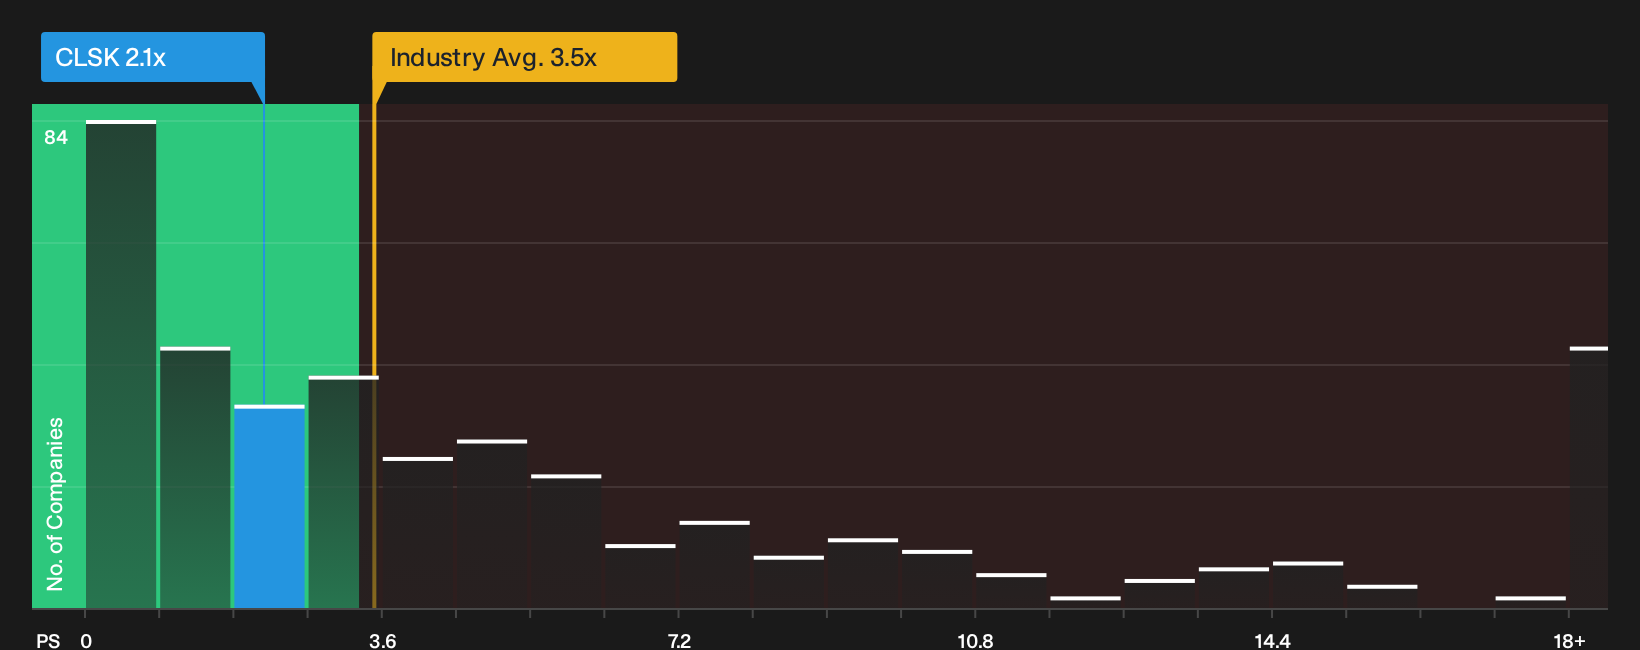
P/S is the cleanest yardstick here because CleanSpark is still being framed more by revenue than by steady free cash flow or dividends. On that measure, the stock trades on a P/S of 2.1x, compared with a Software industry average of about 3.5x and a peer group nearer 3.7x. Against the Fair Ratio benchmark, which adjusts for the firm’s growth profile, margins, size and risk, the current multiple sits on the expensive side even though it is below those broad sector markers.
Recent analyst commentary around potential regulatory hurdles in Texas has not stopped the market from keeping CleanSpark on a richer P/S than that tailored Fair Ratio would suggest. To size how much optimism is embedded in that premium and what it assumes about future revenue quality, you would need to weigh the shrinking recent sales against the sharp swing in earnings and the net cash position. Explore the numbers behind CleanSpark's P/S valuation.
The CleanSpark Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the CleanSpark valuation puzzle leaves off by spelling out which combinations of future growth, margins and earnings would need to play out for the share price to look materially higher or lower than it does today on the Community page. Each narrative treats CleanSpark's fair value as a thesis about the business that can be revisited over time rather than a one off snapshot.
One of the top community narratives on CleanSpark: 74% undervalued
"CleanSpark's fully self-operated, scalable, and power-efficient infrastructure enables it to mine Bitcoin at a significantly lower cost than the market price..."
Discover why this Narrative puts CleanSpark at 74% undervalued.
One more angle on CleanSpark that deserves a closer look
Before you decide how CleanSpark fits into your watchlist, it is worth checking the specific concerns our broader checks have picked up and weighing how they stack up against the rest of the story. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com