


EN
Learn Why The Bull Case For Silgan Holdings Stock Could Change Following Third Quarter Earnings
- Silgan Holdings reported third quarter 2026 sales of US$2,040.2 million and net income of US$105 million, and announced a US$0.21 per share quarterly dividend payable in December 2026, extending a record of 91 consecutive quarterly cash dividends since 2004.
- The combination of higher sales alongside lower net income and earnings per share, together with a long-running pattern of rising dividends, highlights how Silgan Holdings is balancing operating cost pressures with a clear commitment to shareholder cash returns.
- The next step is to examine how Silgan Holdings' latest earnings mix and continued quarterly dividend stream could reshape its broader investment narrative.
Compare Silgan Holdings' steady dividend record with other potentially resilient payers by scanning our 6 dividend fortresses for ideas that match your income focus.
Silgan Holdings Investment Narrative Recap
To own Silgan Holdings, you need to be comfortable with a packaging business that leans on steady consumer end markets while working through cost and mix friction. The short term story rests on whether higher value dispensing and closures, plus pet food containers, can support earnings quality even as reported net income and EPS soften.
The key near term risk is margin pressure from raw material costs and any volume softness in weaker regions, layered on top of already modest cash generation. The latest quarterly figures, with sales edging ahead of last year while profit and EPS declined, do not radically change that equation, but they keep execution risk in clear view.
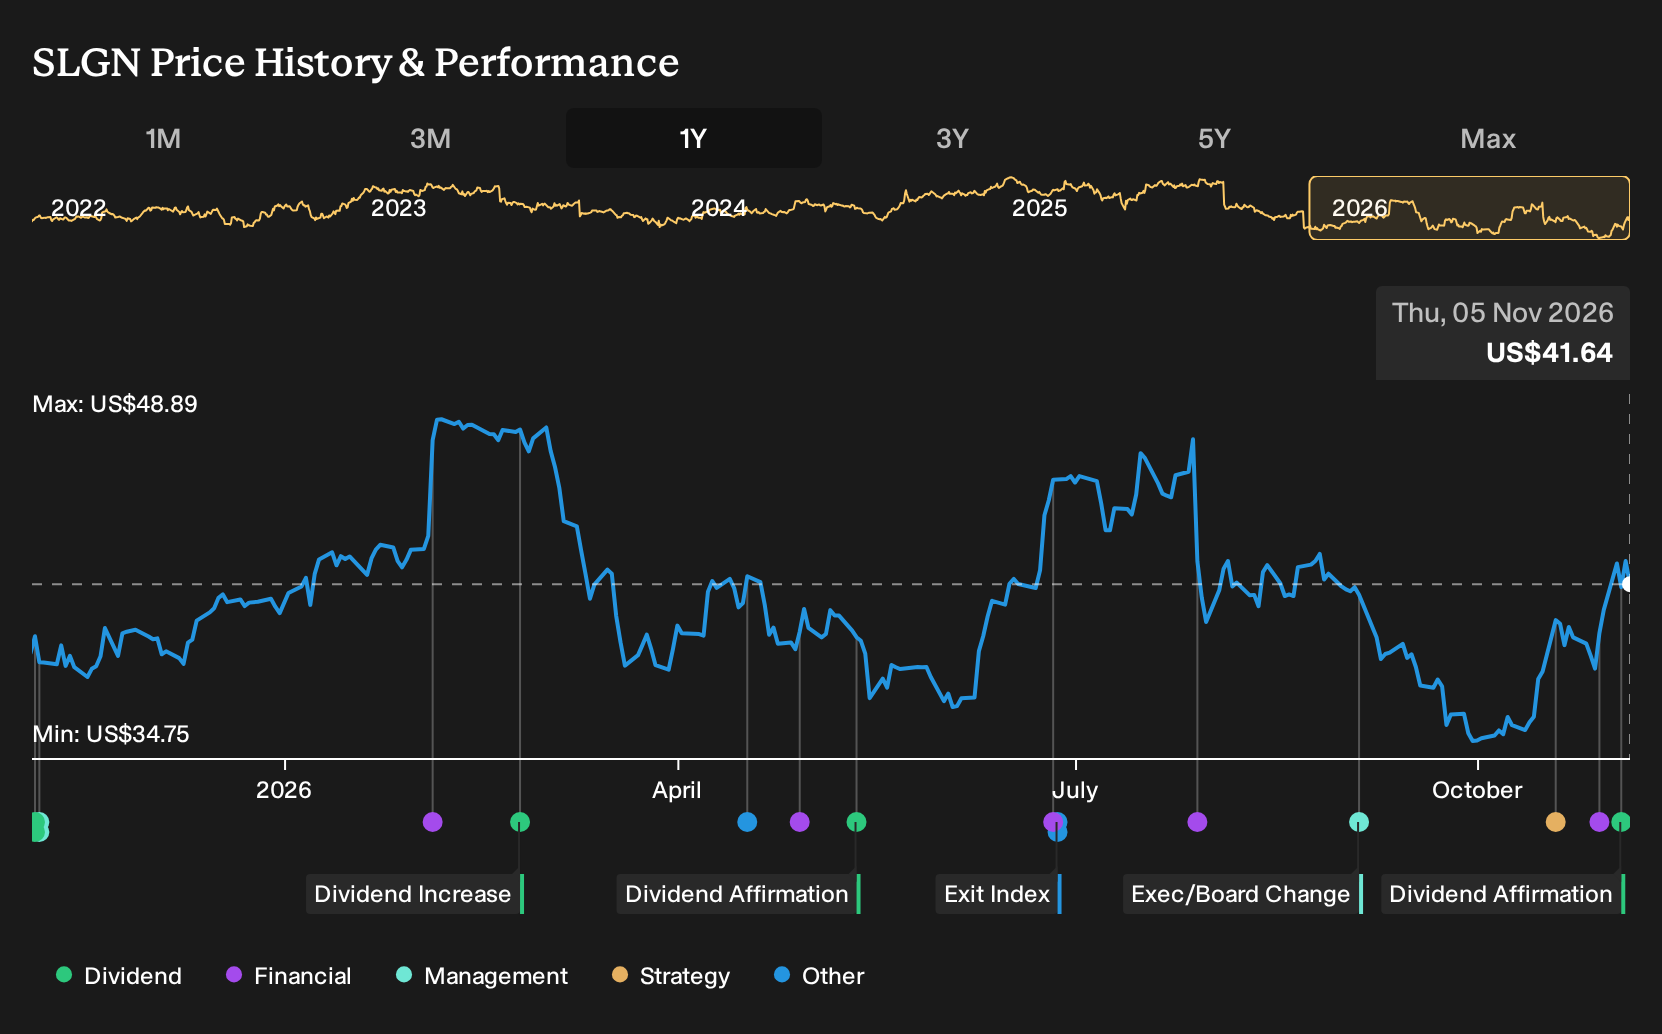
The dividend affirmation on 3 November 2026 is the clearest signal in this news run. Silgan Holdings confirmed a US$0.21 per share cash payout for December and extended a track record of quarterly dividends that has risen every year for 91 consecutive quarters since 2004.
For you as an investor, that update ties directly to the main catalyst and the main concern. There is an income stream the board has chosen to maintain, supported by current operations, while free cash flow and leverage still need watching. The decision highlights how management is prioritising consistency in shareholder returns while working through margin and earnings headwinds.
Silgan Holdings' current analyst narrative points to revenues of US$7.3b and earnings of US$460.8 million by 2029, based on an assumed 3.0% yearly revenue growth rate and a move from US$270.3 million of earnings today. This implies an earnings increase of about US$190 million by that forecast year.
Uncover why Silgan Holdings' fair value indicates a 25% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view on Silgan Holdings leans heavily on the dividend itself as the catalyst. Bullish analysts were already pencilling in about US$7.7b of revenue and US$517.7 million of earnings by 2029, materially above consensus. You can see how that more optimistic camp might read this fresh dividend affirmation very differently, and their forecasts may shift again once the latest results fully filter through.
Explore another Silgan Holdings fair value estimate, including one that suggests as much as 139% potential upside from the current price!
Decide For Yourself
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Silgan Holdings research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Silgan Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Silgan Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Silgan Holdings?
If this Silgan Holdings update has sharpened your focus on income, quality, or risk, the next move is to widen your opportunity set with a structured stock search instead of relying on headlines alone.
- If capital protection sits high on your list, start with companies that screen as more resilient by checking the 32 resilient stocks with low risk scores.
- For investors who care most about balance sheet strength and fundamentals, filter for sturdier businesses through the list of solid balance sheet and fundamentals (24 results).
- If you prefer hunting for under-the-radar opportunities, broaden your watchlist with the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com