


EN
Equinix (EQIX) AI Hub Push Puts Fair Value Debate Back In Focus
Equinix (EQIX) is back in focus after Fortinet introduced FortiAIGate on the Equinix Distributed AI Hub, tying AI-ready infrastructure directly to security, governance, cost control, and data protection concerns for enterprise customers.
Recent trading tells a mixed story. Equinix’s share price has pulled back, with a 1-day move down 5.38% and a 30-day share price return down 3.34%. However, momentum over a longer stretch remains positive, with a 1-year total shareholder return of 23.52% and a 5-year total shareholder return of 42.09%.
Scan how Equinix fits into the broader AI build out by comparing it with a hand picked group of 53 AI infrastructure stocks powering data center demand worldwide.
Equinix now trades around $997 a share after that sharp single day drop, even as its long term returns and AI positioning appear solid. Is a strong business quietly starting to look like a better deal?
Most Popular Narrative: 6% Overvalued
The most followed valuation story on Equinix pegs fair value at $938.23 against the latest close of $997.35, so the narrative leans modestly cautious while still acknowledging the data center and AI footprint described on recent calls.
Equinix’s balance sheet gets positioned, repeatedly, as the mechanism that lets the company convert industry-wide anxiety into company-specific opportunity. Leonetti tells Jefferies’ John Petersen that the company can double capacity while increasing leverage only moderately. He adds, almost as an aside, that it would be opportunistic if good opportunities presented themselves.
See why 2 investors see Equinix as 6% overvalued.
Result: Fair Value of $938.23 (OVERVALUED)
Still, the Equinix story could wobble if data center power constraints tighten further or if neocloud credit concerns begin to affect bookings and renewals.
Find out about the key risks to this Equinix narrative.
Another View: Equinix Through The Cash Flow Lens
That 6% premium to a $938.23 fair value tells only one story about Equinix. The SWS DCF model points in the opposite direction, with the stock around $997 trading about 41% below an estimated future cash flow value of $1,685.23, which implies investors are paying less for long term cash generation than that framework suggests.
It raises a blunt question. Are you more comfortable anchoring on today’s earnings multiples, or on a long range cash flow path that argues the current price builds in a wider safety buffer than the headline P/E implies?
Look into how the SWS DCF model arrives at its fair value.
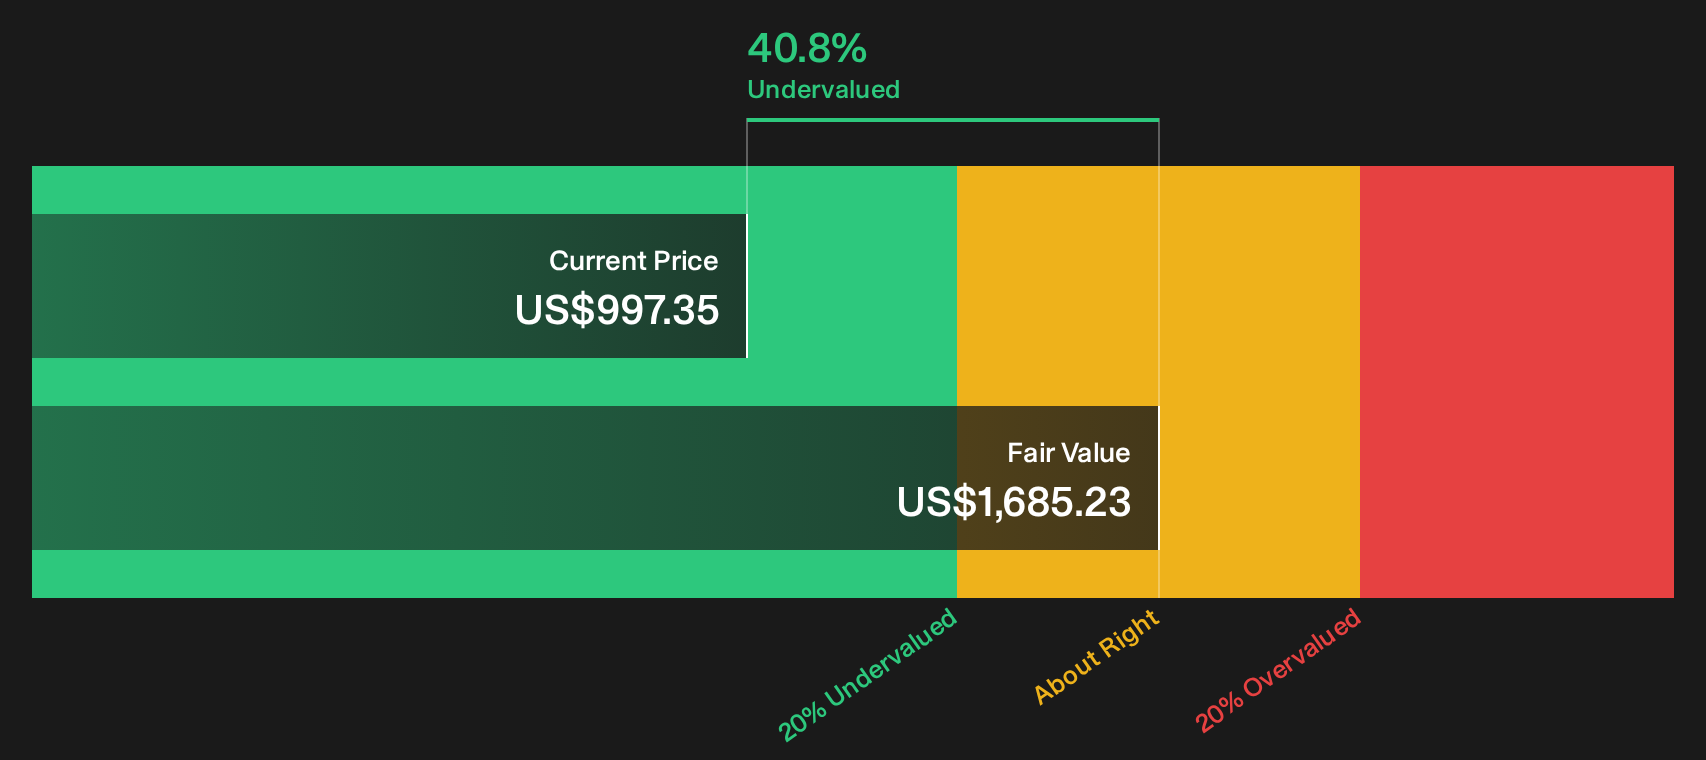
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Equinix for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of cautious valuation and stronger long term returns feels conflicted, treat it as your cue to dig into the full picture yourself, including the 5 key rewards and 1 important warning sign.
Want More Ideas Beyond Equinix?
If Equinix has you thinking harder about where your cash works hardest, do not stop here. Broader opportunities often sit just one smart filter away.
- Target potential upside by scanning a 42 high quality undervalued stocks that screens for quality businesses trading at what could be discounted prices.
- Strengthen income potential by reviewing a 6 dividend fortresses that focuses on companies offering higher yields with an emphasis on resilience.
- Protect your downside by filtering for a 32 resilient stocks with low risk scores that highlights businesses with more durable fundamentals and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com