


EN
Everpure (P) Dropped, So What Is Drawing Attention Now?
Everpure (P) heads into its upcoming Q3 fiscal 2027 earnings report with attention centered on whether projected 37% to 38% revenue growth, driven by data storage and AI demand, matches investor expectations.
The recent pullback, with the share price down 36.5% over the past month and 31.9% over the last week to US$93.44, contrasts with Everpure’s 35.4% year to date share price return and a five year total shareholder return of 229.1%. This suggests strong long term momentum even as short term sentiment cools ahead of earnings.
Scan beyond Everpure and line up other potential beneficiaries of AI infrastructure and data storage demand with our curated list of 53 AI infrastructure stocks today.
Everpure now trades at a steep discount to both analyst targets and some intrinsic estimates after that sharp slide. The key call is whether that gap reflects mispricing or a sober reassessment of risk.
Most Popular Narrative: 48.1% Undervalued
Everpure’s most followed narrative pegs fair value at $180.00, almost double the last close at $93.44, which puts a lot of focus on whether the market is underestimating its role in AI infrastructure.
The market is pricing Everpure as an enterprise storage company. That is the wrong category. Once two or three analysts figure out what is actually happening inside this business, the multiple closes toward AI infrastructure peers, and the stock moves $70 to $80 from here without a single change in fundamentals. Let me walk through why.
See why 48 investors see Everpure as 48% undervalued.
Result: Fair Value of $180.00 (UNDERVALUED)
Still, Everpure’s thesis leans heavily on hyperscale customer adoption and AI storage positioning, so slower hyperscale traction or tougher competition could quickly puncture this re-rating story.
Find out about the key risks to this Everpure narrative.
Another View: Everpure Looks Expensive On Earnings
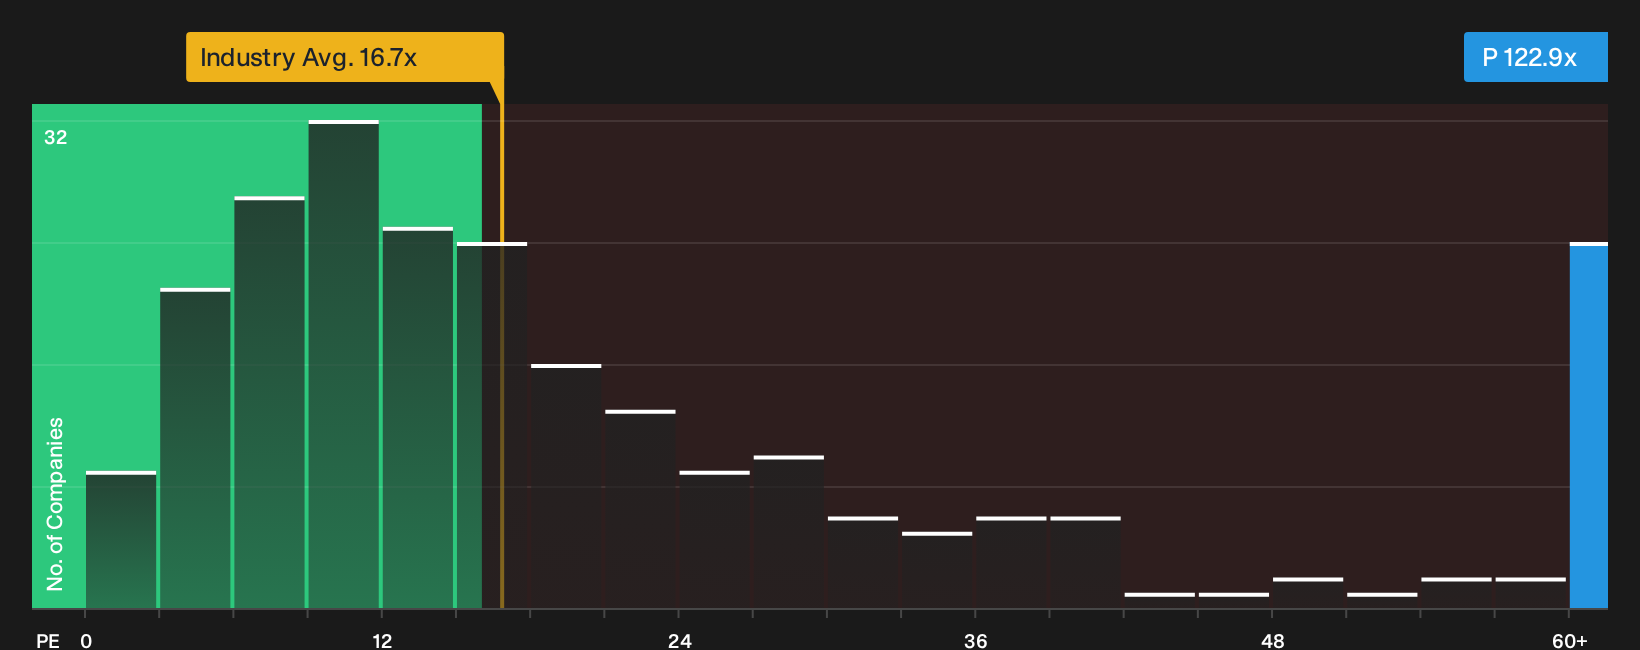
DCF based narratives for Everpure point to a wide gap between price and intrinsic value. The P/E story is very different. The stock trades on 122.9x earnings, while the fair ratio is 46.6x and both global tech peers and the broader tech industry sit near 16.6x to 16.7x. That kind of premium piles a lot of valuation risk onto a growth story. The real question is which yardstick you trust more when sentiment swings.
See what the numbers say about this price, find out in our valuation breakdown. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals around Everpure leave you undecided, act quickly, review the full context, and weigh both sides through our 3 key rewards and 2 important warning signs
Looking for more ideas beyond Everpure?
Do not stop with one stock. Broaden your watchlist with focused stock ideas that match your goals, so you are not relying on a single Everpure style story.
- Target potential mispricing by scanning a curated pool of quality companies through the 42 high quality undervalued stocks.
- Strengthen your income stream by finding companies in the 6 dividend fortresses that offer higher yields with supporting fundamentals.
- Dial back portfolio risk by filtering for sturdier businesses using the 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com