


EN
Does Earnings And Dividend Update Change The Bull Case For Bladex Stock?
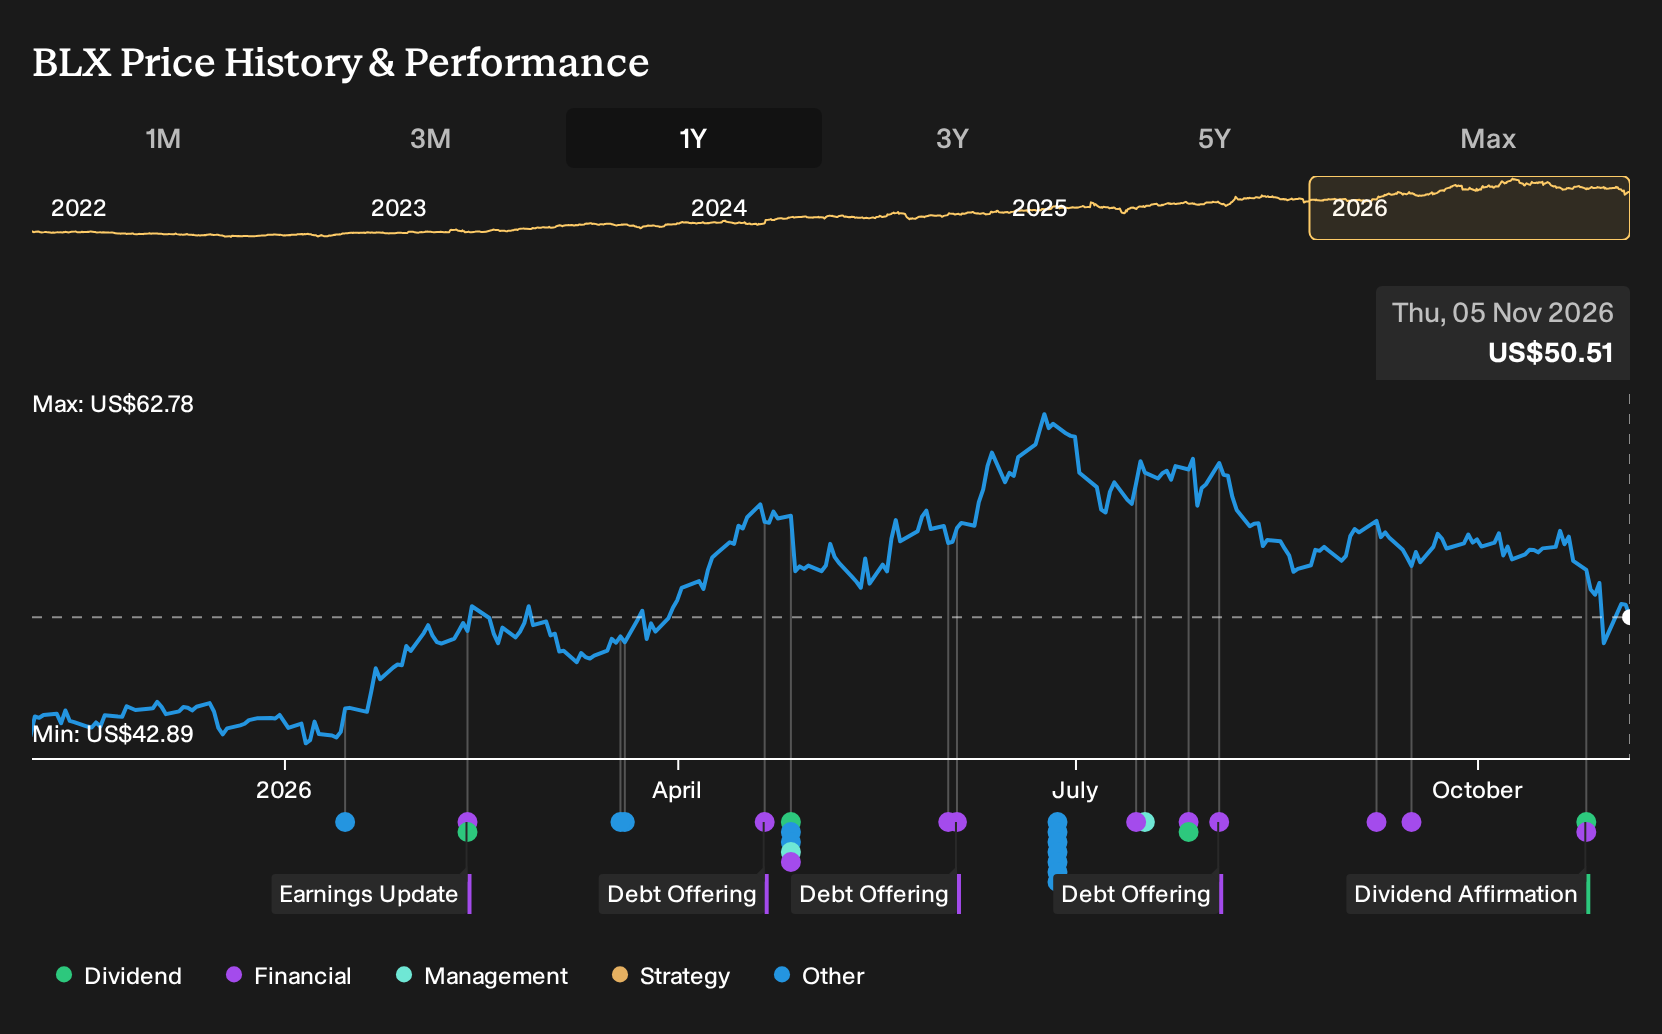
- Bladex reported third quarter 2026 net interest income of US$79.8 million and net income of US$63.2 million, alongside a Board approved quarterly dividend of US$0.6875 per share payable on November 24, 2026.
- The combination of higher net interest income and net income over both the quarter and first nine months of 2026 shows how Bladex is currently converting its lending book into earnings while still returning cash to shareholders through a consistent dividend.
- We will now look at how Bladex's higher third quarter 2026 net income could shape the broader investment narrative that surrounds the bank.
Scan for other banks converting interest income into cash returns like Bladex by jumping into a curated list of 6 dividend fortresses.
Bladex Investment Narrative Recap
To own Bladex, you need to be comfortable with a Latin America focused trade finance bank that leans heavily on short tenor lending, fee income from syndications, and deposit funding. The third quarter print, with net interest income of US$79.8 million and net income of US$63.2 million, supports that operating story but does not dramatically change it in the near term.
The key short term swing factor still looks like net interest margin resilience as competition for short term loans and funding costs move around. The main risk remains a thinner pipeline of large fee deals or higher credit provisions if regional conditions worsen, which could pressure earnings even if core volumes stay broadly intact.
The most relevant element in the recent updates is the Board affirming a quarterly dividend of US$0.6875 per share for the third quarter of 2026, payable on November 24 to holders on the November 6 record date. That decision is set against a history flagged as having an unstable dividend track record, so income focused holders will likely watch consistency closely.
For you as a potential or current shareholder, that payout ties directly into the current catalysts around earnings quality and capital strength. Bladex is using its commercial portfolio, fee businesses and deposit funding to generate cash that can support distributions, while the risk remains that higher competition, fewer syndications or rising provisions could make sustaining that balance harder over time.
Bladex's narrative projects US$487.4 million revenue and US$313.1 million earnings by 2029. This implies 14.1% yearly revenue growth and an earnings increase of about US$86.8 million from US$226.3 million today.
Uncover why Bladex's fair value indicates a 30% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the lowest ranked analysts see Bladex through a very different lens, focusing on pressure on lending spreads rather than the latest dividend and earnings print. They had been working off revenue near US$490.9 million and earnings of about US$300.4 million by 2029. That is a more cautious story than consensus. Use these contrasts as a starting point to explore several viewpoints rather than a single “right” answer, especially now that fresh results may eventually push forecasts in new directions.
Explore 3 other Bladex fair value estimates, including one that suggests it could be worth just $65.90!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Bladex research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bladex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bladex's overall financial health at a glance.
Looking for more investment ideas beyond Bladex?
If the Bladex story has sharpened your thinking, use that momentum to scan a broader field of opportunities with the Simply Wall St Screener. You can filter for the traits that matter most to you and quickly build a watchlist that fits your own risk and income preferences.
- For readers who care most about stability, consider companies highlighted in our 32 resilient stocks with low risk scores that may suit a more cautious approach.
- If you want to focus on businesses with balance sheets that can potentially weather tougher periods, look through the curated list of solid balance sheet and fundamentals (24 results) to see which ones match your criteria.
- Income focused investors can scan for more consistent cash distributors by reviewing a hand picked 6 dividend fortresses and comparing their payout profiles to Bladex.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com