


EN
Earnings Beat Could Be A Key Test For Allstate Stock (ALL)
- Allstate reported third quarter 2026 revenue of US$17.35b and net income of US$2.08b, with adjusted earnings per share of US$9.76 that exceeded analyst expectations despite catastrophe related pressure on reported profit.
- The insurer combined stronger property and casualty underwriting and higher investment income with continued buybacks, retiring 4.55% of its share count under the 2026 repurchase program.
- We will now look at how Allstate's stronger than expected adjusted earnings could influence the longer term investment narrative.
Scan other insurers that show similar underwriting resilience and earnings surprises to Allstate in our hand picked list of 32 resilient stocks with low risk scores.
Allstate Investment Narrative Recap
To own Allstate, you need to be comfortable with an insurance group that leans heavily on underwriting discipline, data and AI tools to manage volatility from weather and legal risk. The latest quarter showed adjusted earnings per share of US$9.76 and solid underwriting metrics, even as reported net income of US$2.08b stayed sensitive to catastrophe losses.
The key near term swing factor remains catastrophe activity and how it flows through combined ratios and earnings stability. The biggest risk is that severe weather and regulatory pushback on pricing keep loss ratios choppy. This quarter’s upside surprise helps the near term story but does not remove that fundamental uncertainty.
The most relevant update for this backdrop is Allstate’s completion of its 2026 buyback program, retiring 11,667,742 shares for US$2.65b, or 4.55% of the share count. That capital return sits alongside the latest quarter’s profit and signals that management is still using excess capital to shrink equity.
For you as an investor, that means per share figures like earnings and book value are more leveraged to operating execution, both good and bad. If underwriting, pricing and Protection Services keep performing, the smaller share base can amplify those outcomes. If catastrophe costs or regulatory outcomes worsen, the same effect works in reverse.
What The Current Forecasts Assume For Allstate
Allstate's narrative projects US$76.0b revenue and US$3.9b earnings by 2029, based on analyst estimates. This implies 2.7% yearly revenue growth and an earnings decrease of US$9.3b from US$13.2b today.
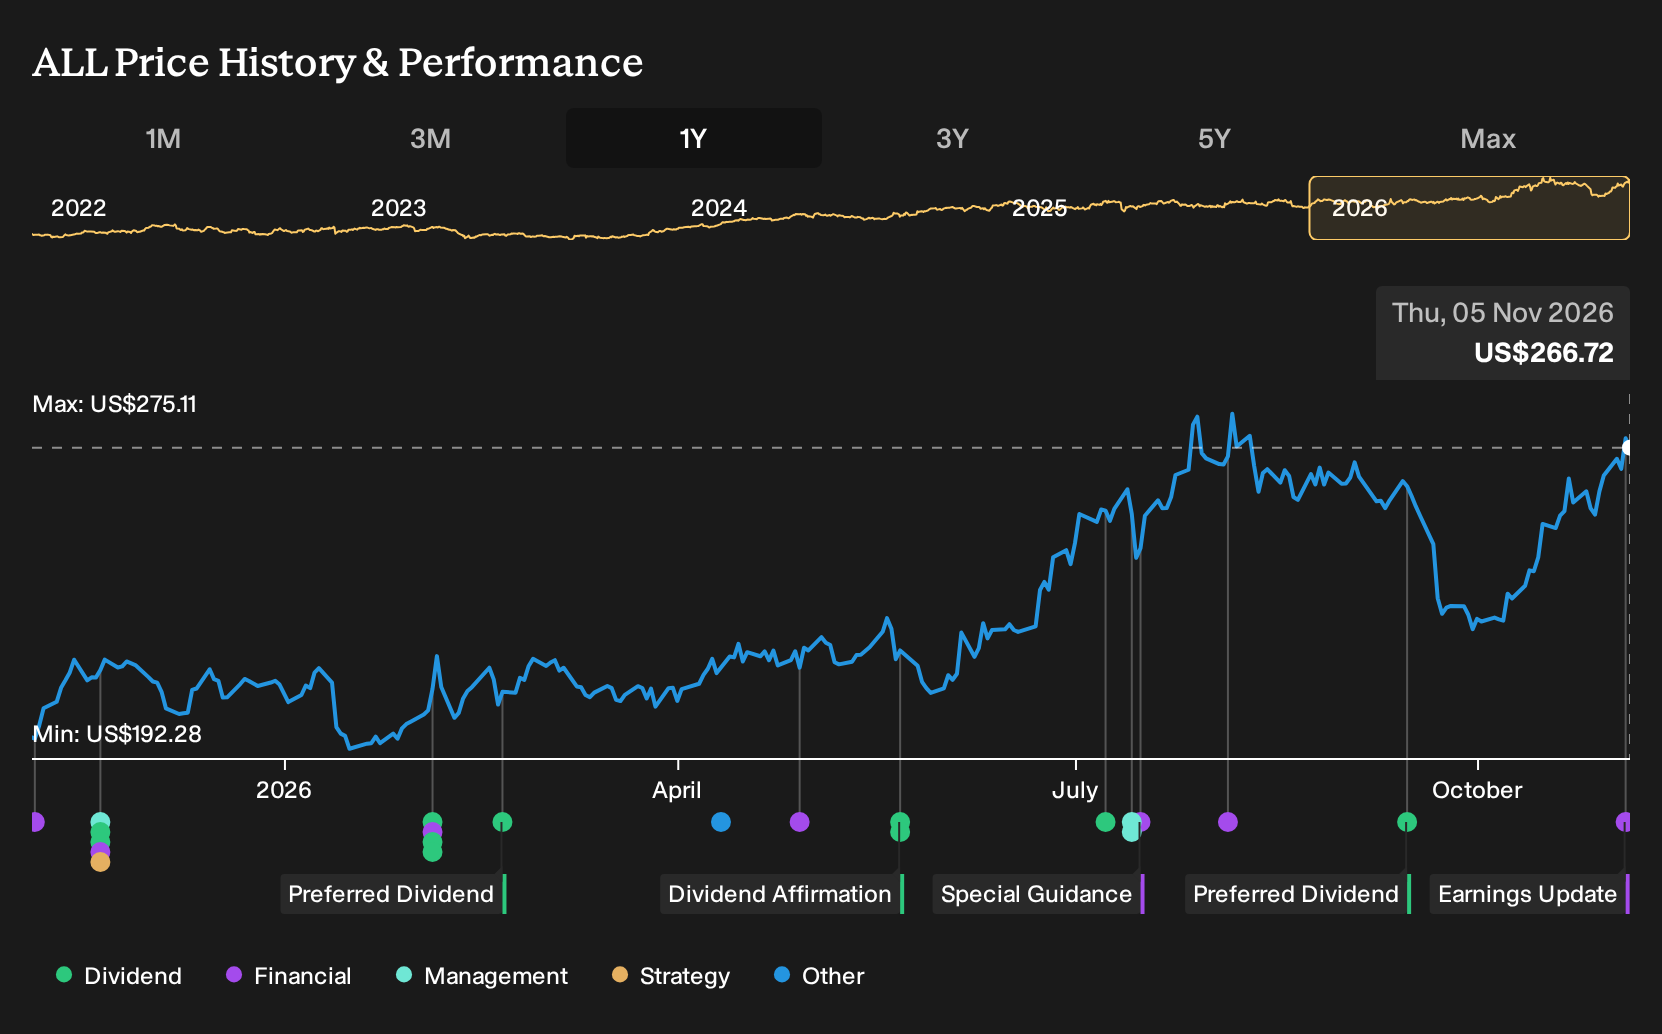
Discover how Allstate's fair value indicates a 3% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view focuses on a potential squeeze on Allstate’s long term auto premiums as vehicle safety tech improves. The most cautious analysts were only penciling in about US$72.7b of revenue and US$3.9b of earnings by 2029 before this quarter, which is a far gloomier story. Opinions clearly vary, so explore several competing forecasts before deciding how this latest earnings and buyback news might reshape expectations.
Explore 5 other Allstate fair value estimates, including one that suggests as much as 27% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Allstate research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Allstate. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Allstate's overall financial health at a glance.
Looking For More Investment Ideas Beyond Allstate?
Once you have formed a view on Allstate, it can help to line that up beside other opportunities that share similar traits or offer very different risk and income profiles. The Simply Wall St Screener lets you do that quickly by filtering for balance sheet strength, quality, payout, or potential mispricing.
- If you want income to do more of the heavy lifting in your portfolio, consider high yield candidates by scanning 6 dividend fortresses that pair substantial payouts with underlying business resilience.
- For investors who care most about capital preservation and steady fundamentals, check out a list of solid balance sheet and fundamentals (24 results) to compare against Allstate’s risk profile.
- If you prefer opportunities that may be flying under the radar, run through 21 high quality undiscovered gems that combine quality metrics with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com