


EN
Is Cadre Holdings (CDRE) A Bargain As Earnings Beat And Buyback Lift The Outlook?
Why Cadre Holdings Stock Is Back on Investors’ Radar
Cadre Holdings (CDRE) just delivered third quarter results that topped analyst revenue and EPS forecasts, raised its 2026 sales outlook, and rolled out a new US$100 million share repurchase plan.
The latest earnings beat, higher 2026 sales outlook, and fresh US$100 million buyback arrive after a choppy stretch for Cadre Holdings. The share price is up 26.55% over the past month but down 21.52% on a year-to-date share price return, and the 1-year total shareholder return has declined 24.81%, even as the 5-year total shareholder return of 73.69% points to momentum that has built over a longer window.
Compare Cadre Holdings’ rebound with a hand-picked group of defense and safety peers by checking out the 32 resilient stocks with low risk scores that have kept volatility in check while markets shifted.
After a sharp bounce and a weak year-to-date return, Cadre Holdings now sits at a crossroads. Do the current valuation and buyback terms still tilt the risk reward in favour of new buyers, or not?
Most Popular Narrative: 32% Undervalued
Cadre Holdings last closed at $32.27 while the most followed narrative pegs fair value at $47.50, so the current price sits well below that narrative anchor and puts the focus on whether its contracts and acquisitions can carry earnings higher.
The main factor that has to go right is Cadre's ability to turn its acquisition program, including TYR Tactical and Alien Gear, and its record multi-year contract wins into sustained high-margin earnings progress after recent margin pressure and EPS declines.
The current valuation implies the share price reflects recent earnings pressure and a 29.5% stock price drop more than the guidance for higher 2026 revenue and EBITDA and the record backlog, which this narrative presents as suggesting Cadre Holdings is undervalued and that the outlook is positive.
See why 11 investors see Cadre Holdings as 32% undervalued.
Result: Fair Value of $47.50 (UNDERVALUED)
Still, if contract execution slips or if margin pressure seen in earlier quarters reappears, the Cadre Holdings narrative that leans on backlog strength could quickly weaken.
Find out about the key risks to this Cadre Holdings narrative.
Another View: What Multiples Say About Cadre Holdings
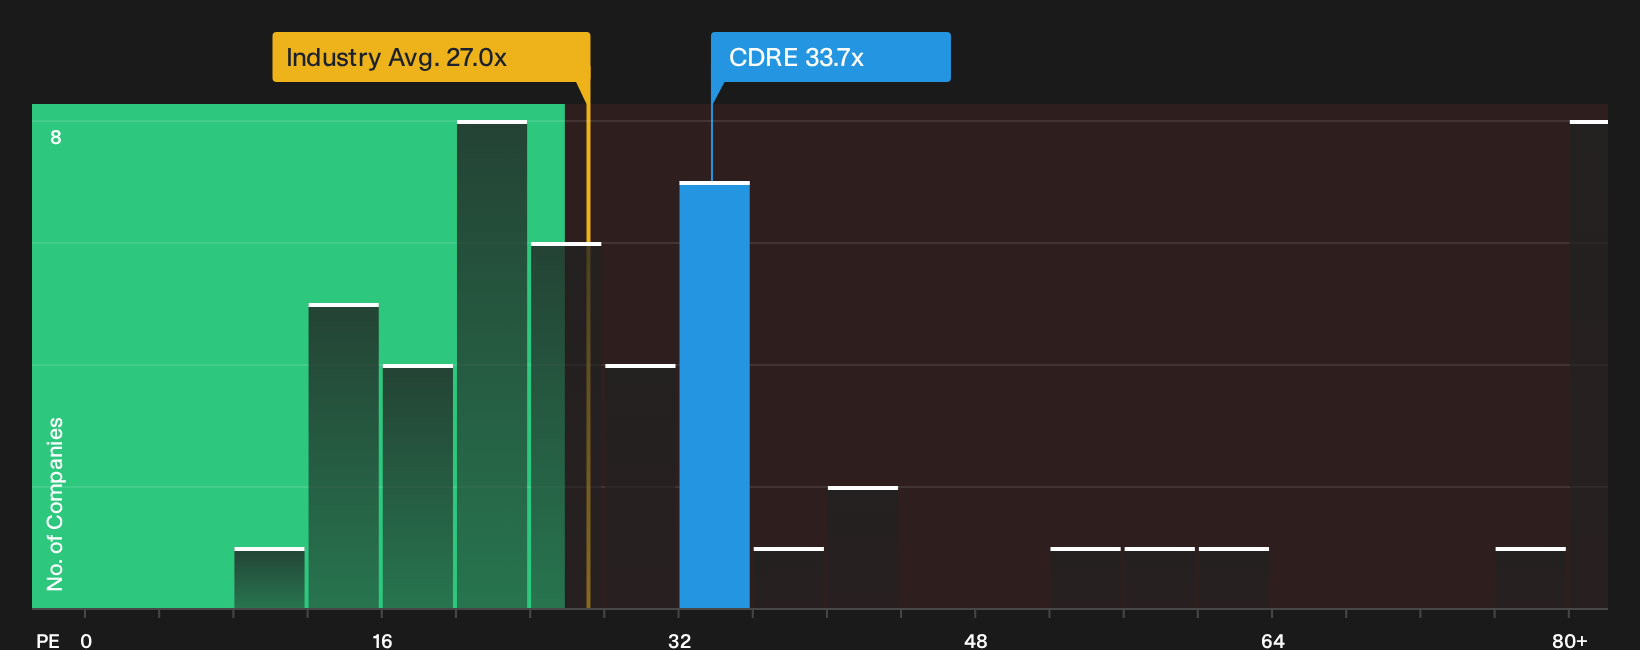
There is a catch. On simple P/E maths, Cadre Holdings trades at 33.7x earnings, which is richer than the US Aerospace & Defense sector on 29.7x and above a fair ratio of 28.3x, as well as peers at 24.7x. That premium raises the question of how much valuation risk you are really willing to carry if the story stumbles.
See what the numbers say about this price in the fuller context of earnings quality, sector benchmarks and the fair ratio in our valuation breakdown. Then decide how much weight to give the relative valuation view versus the cash flow view See what the numbers say about this price — find out in our valuation breakdown.
This side by side look at Cadre Holdings' current P/E against the wider industry can help you judge whether the recent rebound has already baked in a lot of optimism
Next Steps
Mixed signals around Cadre Holdings can feel confusing, so move quickly from opinion to evidence by weighing both the caution and the upside yourself using the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Cadre Holdings?
You have weighed Cadre Holdings. Now give yourself an edge by lining up a few fresh watchlist candidates that fit clear, disciplined criteria.
- Target resilient balance sheets and steady fundamentals by scanning a list of solid balance sheet and fundamentals (24 results) that cuts through weaker financial structures.
- Hunt for quality at a sensible entry point using a curated 42 high quality undervalued stocks that filters for fundamentals first, hype second.
- Build a cash flow stream on your terms by reviewing a focused 6 dividend fortresses designed for investors who want income with substance.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com