


EN
Canadian Natural Resources (TSX:CNQ) Stock Looks Below Fair Value As Its 234% Run Cools
Canadian Natural Resources has delivered a powerful share price run over the past several years, yet the recent pullback puts fresh attention on whether the current tag is well supported by its earnings. With the business now emphasizing shareholder returns after hitting its net debt target, the question for you is how much of that earnings power is already reflected in the valuation.
- Over the past 5 years the share price has gained 234.1%, which puts a lot of weight on the idea that the company’s earnings profile can justify a higher bar than in the past.
- Recent results highlighted strong production and a plan to direct all free cash flow to shareholder returns, which can shape how investors value each dollar of current and future profit.
- There is a second opinion on Canadian Natural Resources worth weighing. See what analysts think Canadian Natural Resources's shares could be worth.
The issue now is whether Canadian Natural Resources' current share price around C$68.48 is justified by the level and quality of its earnings.
If you want more ideas beyond Canadian Natural Resources while you weigh whether its earnings back up the recent run, a focused stock screen of 6 high quality undervalued stocks can be a useful next step.
Does Canadian Natural Resources Look Undervalued on Earnings?
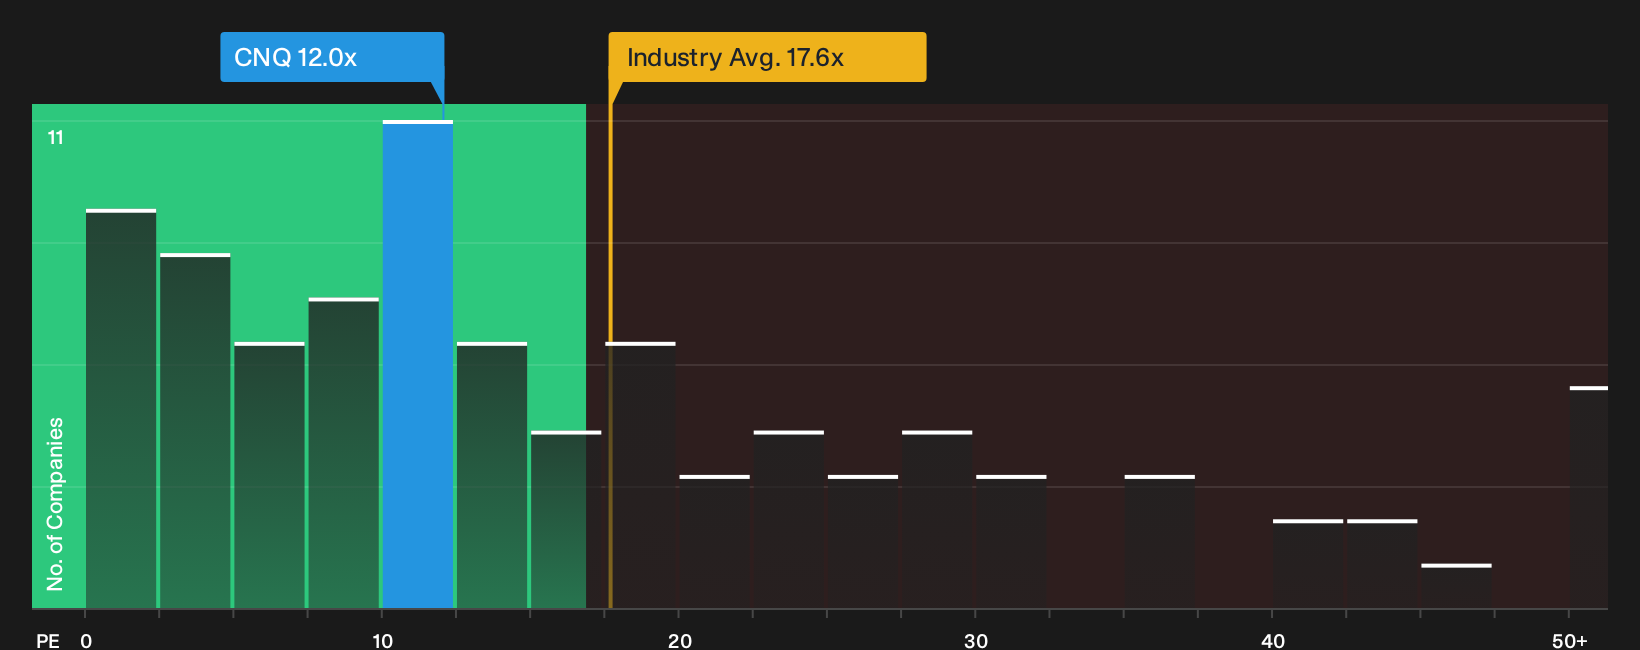
The P/E ratio suits Canadian Natural Resources because earnings are a key focus for investors in large, established oil and gas producers. At around 12.0x earnings, the stock trades below the Oil and Gas industry average of about 17.6x and also below a broader peer group near 22.2x. That gap indicates the market currently prices each dollar of Canadian Natural Resources earnings more conservatively than many comparable producers.
Because the recent results highlighted record production and a plan to send all free cash flow to shareholder returns, this lower P/E versus a tailored fair level suggests the shares screen as undervalued on this earnings yardstick. Despite the strong third quarter update and the shift to 100% of free cash flow being directed to investors, the valuation still points to a discount relative to what the company-specific profile could justify. Explore the numbers behind Canadian Natural Resources's P/E valuation.
The Canadian Natural Resources Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation question for Canadian Natural Resources' stock leaves off by spelling out which paths for future growth, profitability and earnings would need to play out for the current price to look materially too high or too low. Each narrative then ties a specific fair value estimate to a distinct storyline about catalysts and risks, so you can track over time which version of Canadian Natural Resources' future is actually taking shape on the Community page.
Community views on Canadian Natural Resources split between those who see more support from long life reserves and cash returns and those who worry policy and cost risks are not fully reflected.
Bull case: 9% undervalued
"The large inventory of long-life, low- or zero-decline oil sands reserves, including mining and synthetic crude oil assets with multi decade reserve life indices…"
Discover why this Narrative puts Canadian Natural Resources at 9% undervalued.
Bear case: 10% overvalued
"Heavy reliance on long life, zero or low decline Oil Sands mining and upgrading assets means future tightening of carbon pricing and methane rules could increase per barrel costs…"
Explore why this Narrative puts Canadian Natural Resources at 10% overvalued.
One more piece of the Canadian Natural Resources story to check
Canadian Natural Resources has appealing valuation talking points, yet the research checks also flag specific concerns that deserve a closer look before you get comfortable with the full risk picture. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com