


EN
Intuitive Machines (LUNR) Stock Looks Above Fair Value As 202% Three Year Gain Continues
Intuitive Machines has given investors a wild ride, with the share price still up very sharply over three years despite steep recent declines. With that kind of swing, the immediate question is whether the current US$8.62 price is supported by the sales the business is generating today.
- Over the past three years, Intuitive Machines has returned about 202.5%, which puts its current valuation firmly under the microscope when you line it up against its revenue base.
- The recent NASA FALCON-RADAR Earth science mission award may support expectations for future spacecraft platform sales and longer term contract revenue, which can influence how much investors are prepared to pay for each dollar of current turnover.
- There is a second opinion on Intuitive Machines worth weighing. See what analysts think Intuitive Machines's shares could be worth.
The stock's next move may depend on whether that recent price level looks sensible when set against Intuitive Machines' sales and the Fair Ratio benchmark.
If you want a quick sense check on Intuitive Machines' swingy track record and NASA-driven story, compare it with other our screener containing 21 high quality undiscovered gems.
Has Intuitive Machines Run Too Far on Sales?
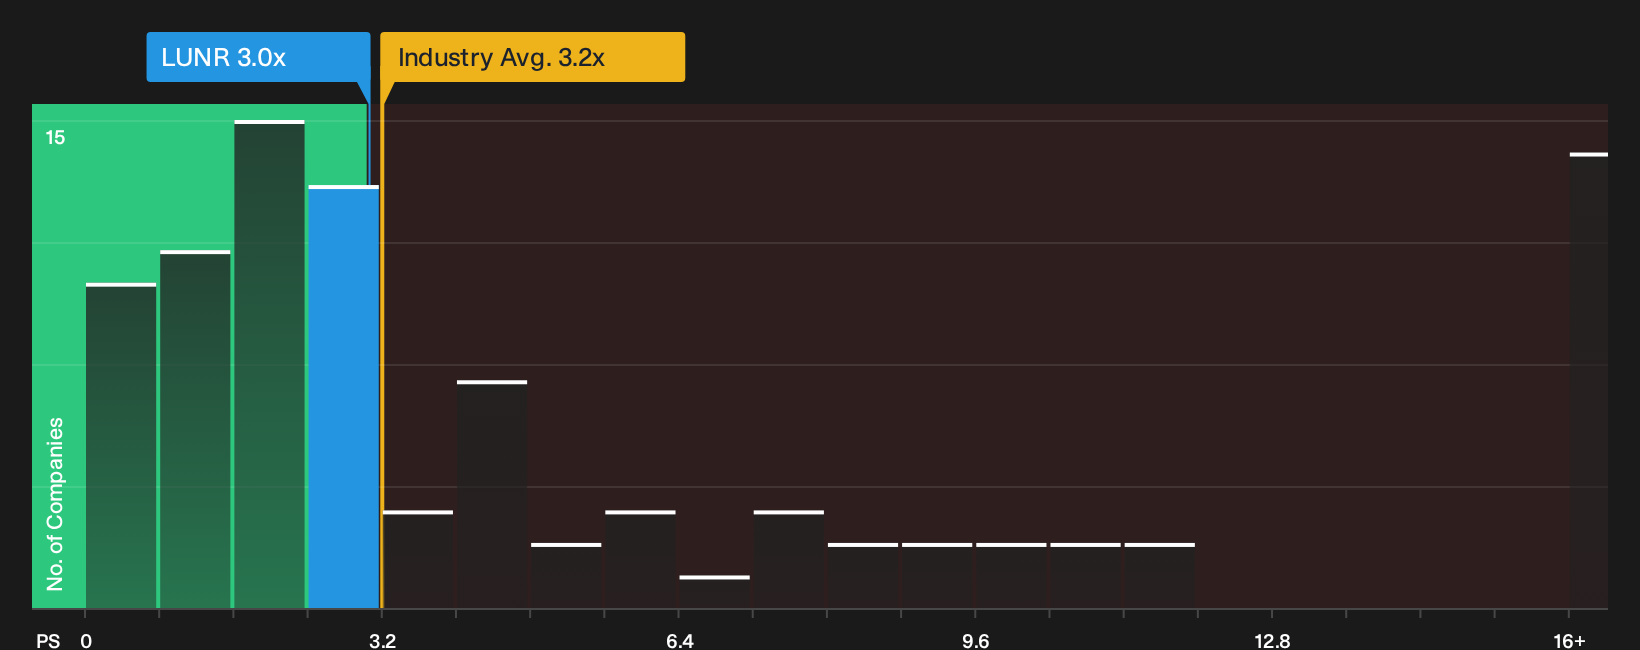
P/S is useful for Intuitive Machines because revenue is more relevant than current earnings for a space contractor still investing heavily in missions. On this yardstick, the stock trades on a P/S of 3.0x, which is slightly below the Aerospace & Defense industry average of 3.2x but above the peer group on about 2.3x. Compared with the tailored Fair Ratio benchmark, which blends Intuitive Machines' growth profile, margins, size and risk, the current sales multiple screens as overvalued.
The recent NASA FALCON-RADAR contract adds weight to the story. However, the 3.0x sales tag already reflects a richer valuation than the model implies. That gap suggests investors are paying a premium per dollar of current revenue, which puts more pressure on future contract execution and mission delivery to justify the price. Explore the numbers behind Intuitive Machines's P/S valuation.
The Intuitive Machines Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Intuitive Machines pick up where the valuation puzzle leaves off. Each one makes clear which revenue, margin and earnings paths would need to play out for Intuitive Machines' stock to be worth materially more or less than today, and treats fair value as a thesis about how the business might develop that you can keep tracking over time. These are available on Simply Wall St's Community page.
One of the top community narratives on Intuitive Machines: 63% undervalued
"Intuitive Machines (LUNR) has successfully shifted from a high-risk startup to a Lunar Infrastructure Prime, backed by a $943M backlog and a strategic pivot toward high-margin data services via the Lanteris acquisition."
Discover why this Narrative puts Intuitive Machines at 63% undervalued.
One more Intuitive Machines check that belongs beside the price tag
Before you treat Intuitive Machines as just a story about contracts and sales multiples, it is worth asking who is steering the spacecraft and how their rewards line up with your interests. See who runs Intuitive Machines and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com