


EN
Did Stable Credit Outlook Just Shift Ally Financial (ALLY) Stock?
- Ally Financial recently updated its outlook, indicating retail auto net charge-offs are tracking near the midpoint of prior guidance while margin expectations reflect higher-yielding auto and corporate finance loans and the runoff of lower-yielding mortgage assets.
- Lease losses tied to recalled Stellantis vehicles are currently weighing on returns, but management expects this drag to steadily fade and no longer affect results by the second half of 2027. This changes how you might think about the timing of earnings pressure.
- We will now look at how Ally Financial's investment narrative could shift as lease loss pressures are expected to gradually recede.
Compare Ally Financial's setup with a curated group of lenders built to handle credit swings in auto and consumer cycles by scanning our 32 resilient stocks with low risk scores.
Ally Financial Investment Narrative Recap
To own Ally Financial, you need to be comfortable with a story built around auto credit, digital deposits, and a gradual remix into higher yielding loans. The recent update that retail auto net charge offs are tracking near the midpoint of guidance suggests the near term credit picture is holding roughly in line with expectations rather than shifting the thesis.
The key short term swing factor is still how quickly higher yielding auto and corporate finance assets offset funding costs and lease headwinds. The biggest current risk remains lease residual losses from recalled Stellantis vehicles and any spillover into other partners, which could cap progress on net interest margin if pressures broaden or linger longer than expected.
The most relevant disclosure for this update is management flagging that Stellantis related lease losses are pressuring returns today but are expected to fade and no longer affect results by the second half of 2027. That timing guide matters because it frames how you think about the duration of earnings drag from residual values.
For catalysts, the expected easing of these lease losses intersects directly with Ally Financial’s push into higher yielding retail auto and corporate finance loans. If credit performance stays close to guided ranges while recalled vehicle exposure runs off as indicated, the remix into those assets and the benefit from prior risk transfer deals could become more visible in reported profitability and capital flexibility over the next few years.
How Ally Financial's Lease Drag Lines Up With Analyst Forecasts
Ally Financial's narrative projects US$9.9b revenue and US$1.7b earnings by 2029. This implies 7.4% yearly revenue growth and an earnings increase of about US$300m from US$1.4b today.
Uncover why Ally Financial's fair value indicates a 22% potential upside to its current price, which could narrow quickly.
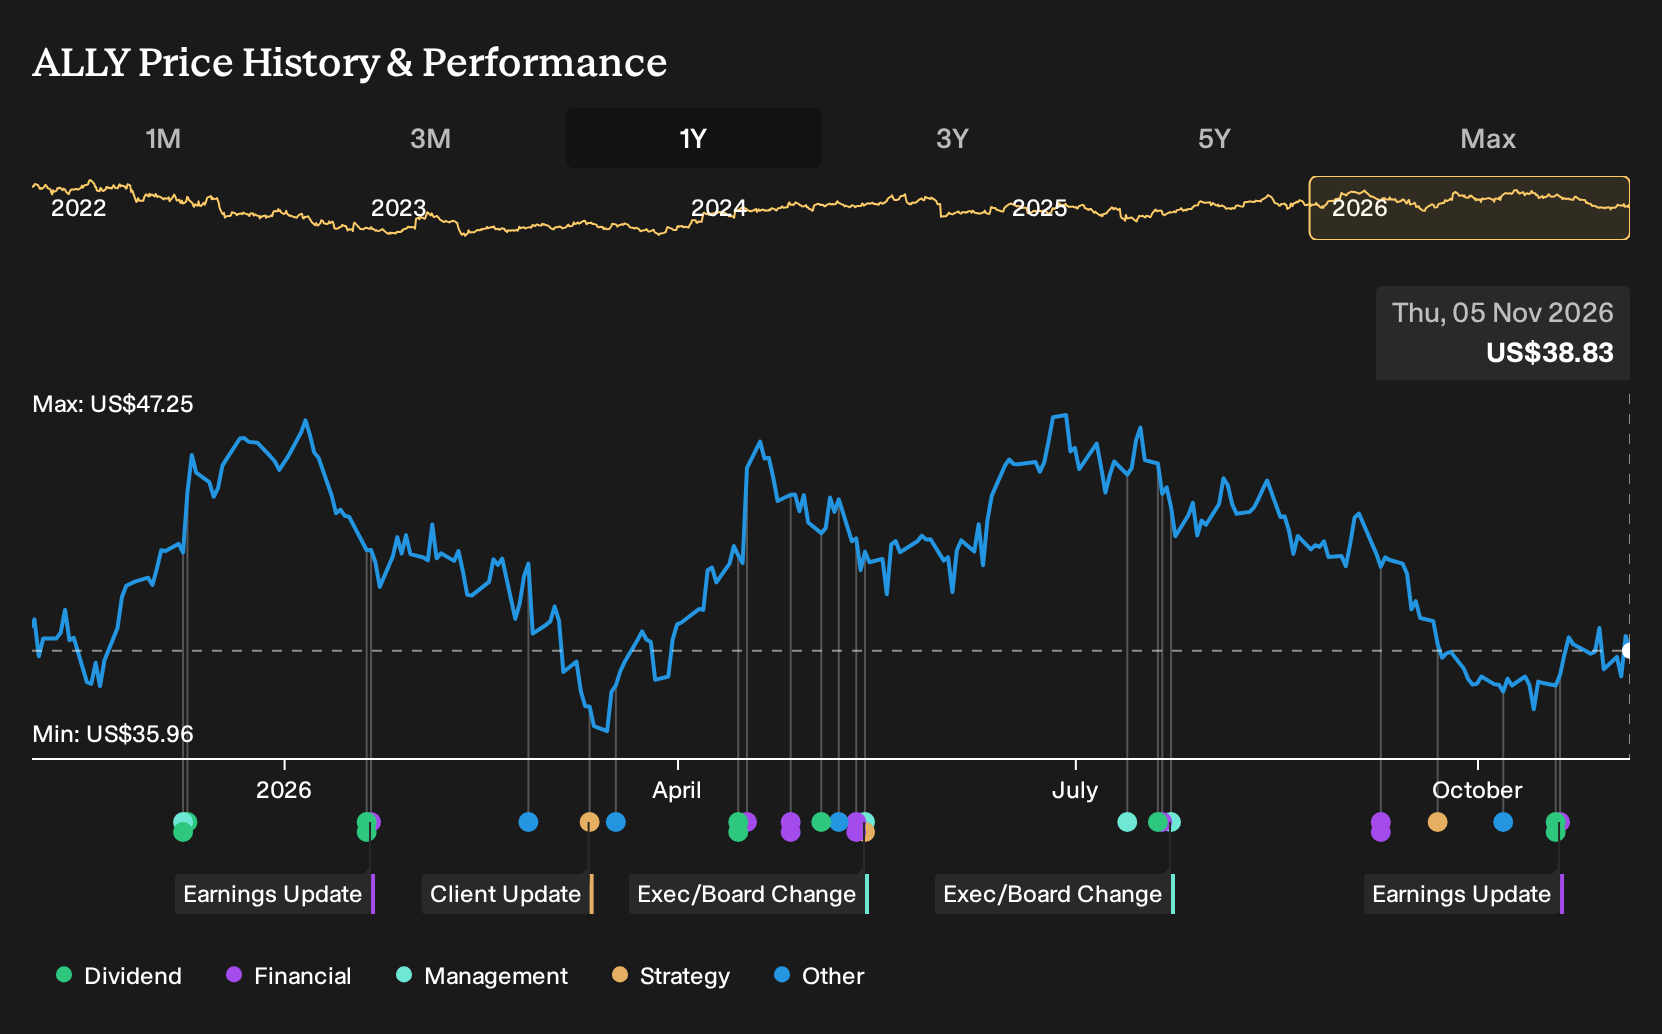
Exploring Other Perspectives
Some of the most optimistic analysts focus less on lease risk and more on Ally Financial’s Corporate Finance engine. Those forecasts, built before this Stellantis update, were looking for revenue of about US$10.7b and earnings of roughly US$2.2b by 2029. That is a far brighter story than consensus, and it might shift again as this news settles in.
Explore 4 other Ally Financial fair value estimates, including one that suggests as much as 44% potential increase from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ally Financial research is our analysis highlighting 6 key rewards that could impact your investment decision.
- See our latest analysis for Ally Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ally Financial's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ally Financial?
Once you have a handle on Ally Financial, it can help to line it up against other opportunities that fit different risk and income profiles using the Simply Wall St Screener.
- If you want potential mispricing with quality in mind, scan a curated set of companies highlighted as 42 high quality undervalued stocks and see which ones warrant a spot on your watchlist.
- For investors who care most about income resilience, focus on payout strength and consistency by reviewing a group of high yield opportunities sorted as 6 dividend fortresses that may suit a more cash focused approach.
- When balance sheet strength is your starting filter, narrow the field quickly by working through a list of solid balance sheet and fundamentals (24 results) that can help you compare financial footing at a glance.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com