


EN
FTI Consulting (FCN), Why Is Fresh Attention Building Around It?
FTI Consulting (FCN) has been busy reshaping its senior ranks, adding experienced leaders in legal, transactions, forensic work, tax and cybersecurity to deepen its advisory bench across complex global matters.
Investors have reacted quickly to this hiring spree. Despite a 1-day share price decline of 1.17% to US$195.99, FTI Consulting has a 30-day share price return of 42.42% and a 1-year total shareholder return of 19.52%. However, the 3-year total shareholder return is down 9.38%, which indicates stronger recent performance following a weaker medium-term period.
Scan how FTI Consulting’s leadership-driven story compares with other high quality businesses showing strong fundamentals and financial resilience using our curated 32 resilient stocks with low risk scores today.
For FTI Consulting, a 42.42% move in 30 days alongside softer three year returns raises a simple tension: Are investors now paying up for resilient fundamentals, or just chasing a sharp rebound in sentiment before valuation runs ahead of itself?
Most Popular Narrative: 27% Overvalued
FTI Consulting last closed at $195.99, while the most followed narrative pegs fair value closer to $154.50. This puts the recent rally against a more cautious long term earnings and cash flow framework built on an 8.0% discount rate.
The consulting industry trend toward consolidation and pressure on weaker competitors intersects with FTI Consulting's low leverage balance sheet, enlarged US$1.5b revolving credit facility and ongoing share repurchases of hundreds of millions of dollars a year. Together these factors create scope for continued capital returns and potential earnings per share growth even if headline revenue trends remain mixed.
See why 2 investors see FTI Consulting as 27% overvalued.
Result: Fair Value of $154.50 (OVERVALUED)
Still, the narrative could be knocked off course if Economic Consulting remains an earnings drag or if legal and overhead costs stay higher for longer.
Find out about the key risks to this FTI Consulting narrative.
Another View on FTI Consulting’s Valuation
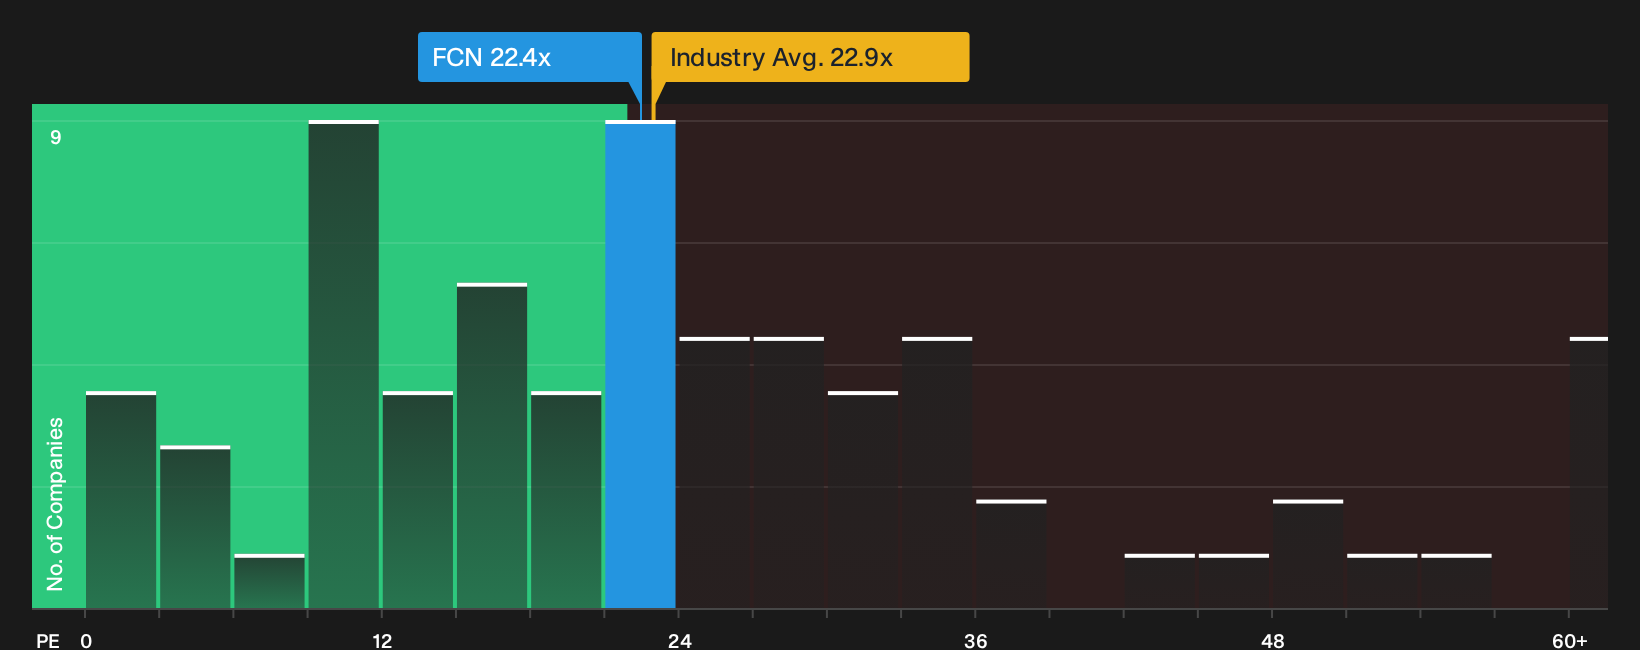
The overvaluation narrative pins FTI Consulting at a fair value of $154.50, yet the stock trades at a P/E of 22.4x compared with a fair ratio of 24.3x. Against peers on 27.8x and a US Professional Services average of 23.1x, that gap suggests less froth than the headline 27% premium implies.
For investors, that split picture is the real question. Is the crowd leaning too heavily on one fair value story when relative pricing points a little lower on valuation risk and a little higher on potential resilience, or is this exactly where a quality advisory stock should trade in late 2026?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the FTI Consulting story so far. If you want to move quickly and judge the balance of risk and upside for yourself, start with the 3 key rewards and 1 important warning sign.
Looking for more FTI Consulting style investment ideas?
If FTI Consulting has sharpened your focus on quality, you can broaden your watchlist now with a few targeted stock ideas built from clear, rules-based screeners.
- Chase value that still looks disciplined by scanning companies on our 42 high quality undervalued stocks that pair attractive pricing with measured fundamentals.
- Strengthen the defensive side of your portfolio by running through the list of solid balance sheet and fundamentals (24 results) and focusing on businesses with sturdier financial footing.
- Look for emerging stories at an earlier stage by checking the 21 high quality undiscovered gems before pricing reflects broader market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com