


EN
Earnings Beat Could Be A Game Changer For First Commonwealth Financial Stock (FCF)
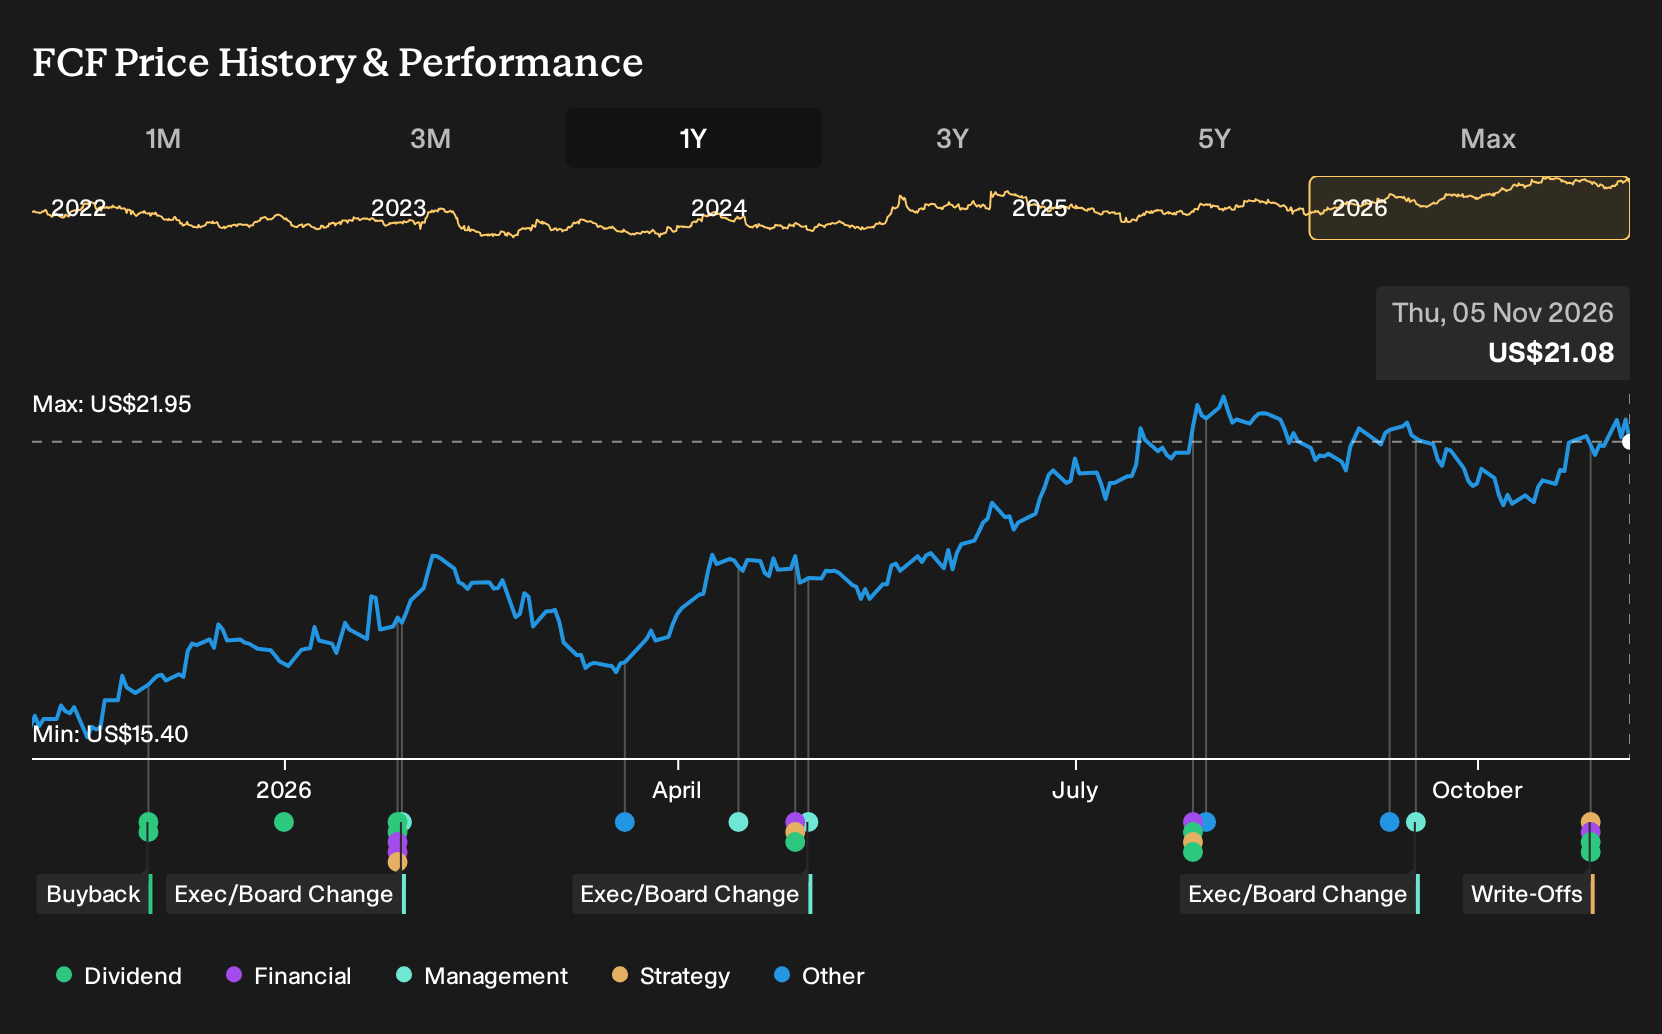
- First Commonwealth Financial reported third quarter 2026 net income of US$44.94 million on net interest income of US$116.32 million, with net charge offs of US$4.581 million, an increased quarterly dividend of US$0.14 per share, and a larger US$100 million buyback authorization that has already funded share repurchases in the period.
- The combination of higher net interest income, lower net charge offs than a year earlier, a larger dividend, and completed repurchases of 4.76% of shares reflects active capital deployment alongside credit cost control in First Commonwealth Financial's current business profile.
- We will now examine how First Commonwealth Financial's higher dividend and expanded buyback authorization could influence its existing investment narrative.
Compare First Commonwealth Financial’s dividend and buyback moves with other banks that pair income with balance-sheet discipline by scanning our hand picked list of solid balance sheet and fundamentals (24 results) today.
First Commonwealth Financial Investment Narrative Recap
To own First Commonwealth Financial, you need to be comfortable with a regional bank story built around a relatively firm net interest margin, a granular loan mix, and fee income that takes some pressure off lending. The third quarter update mostly reinforces that script, with net interest income of US$116.32 million and net income of US$44.94 million supporting that earnings profile.
The most important near term swing factor remains how funding costs and deposit competition intersect with loan yields. Lower net charge offs of US$4.581 million versus US$12.247 million a year earlier help the near term picture, while the main risk still sits in deposit pricing pressure and potential loan runoff from large commercial payoffs.
The dividend increase to US$0.14 per share is a clear signal in this batch of announcements. This is a 3.7% step up from the third quarter of 2025, backed by year to date net income of US$127.08 million and a history of using capital returns as part of the First Commonwealth Financial story.
On potential catalysts, the higher payout works together with the enlarged US$100 million buyback. Combined, they concentrate more of whatever earnings the bank generates into each remaining share. The key execution focus is whether credit losses and deposit costs remain contained enough for those capital returns to be comfortably supported by ongoing operations.
First Commonwealth Financial's current analyst narrative points to forecast revenue of US$661.2 million and earnings of US$224.9 million by 2029. These projections are built on an assumed 9.2% yearly revenue growth rate and an earnings increase of about US$56.6 million from US$168.3 million today.
Uncover how First Commonwealth Financial's fair value indicates a 14% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
The Simply Wall St Community only includes two fair value views for First Commonwealth Financial so far, yet they already span roughly US$24 to just over US$40 per share. That gap shows how far opinions can stretch before factoring in the latest earnings, dividend lift and buyback activity, so you may want to compare several contrasting estimates yourself.
Explore another First Commonwealth Financial fair value estimate, including one that suggests it could be worth just $24.07.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your First Commonwealth Financial research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for First Commonwealth Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Commonwealth Financial's overall financial health at a glance.
Looking for more investment ideas beyond First Commonwealth Financial?
Once you have a view on First Commonwealth Financial, it can help to widen the lens and compare it with other companies that match your preferred balance of return potential and resilience. The Simply Wall St Screener lets you filter for exactly the traits you care about so you can line up a broader watchlist that fits your approach.
- If you care most about limiting downside risk and prioritizing resilience, start with a curated set of companies that score well on stability through the 32 resilient stocks with low risk scores.
- For investors who want income at the forefront of their approach, focus on companies with robust payout profiles by scanning a hand picked group of 6 dividend fortresses.
- If you are hunting for opportunities that the market may not be fully focused on yet, broaden your research with a carefully filtered pool of 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com