


EN
Cinemark Holdings (CNK) Record Q3 Keeps Valuation In Focus After The Rally
Cinemark Holdings (CNK) just delivered third quarter earnings that set new company records, with worldwide revenue around US$1.1b and adjusted EBITDA reaching a third quarter high, according to management disclosures.
The share price reaction has been cooler than the earnings headlines suggest, with Cinemark Holdings slipping 0.8% on the day of the release even as the 30 day share price return sits at 13.5% and the year to date share price gain reaches 70.2%.
Scan beyond Cinemark Holdings and see how other theatre and media operators stack up on our curated list of 42 high quality undervalued stocks.
Cinemark Holdings has just run hard on record earnings, yet the latest move only nudged the share price. Does that set up a reasonable entry today, or a case for waiting until the next pullback before committing fresh capital?
Most Popular Narrative: 4% Undervalued
Cinemark Holdings last closed at $40.04 while the most followed narrative pegs fair value closer to $41.82. This puts the current price only slightly below that estimate and makes the underlying thesis more about how those future assumptions get earned than about a simple discount gap.
Execution of Cinemark Holdings capital allocation framework, including high return capex into premium amenities and future shareholder return programs funded by sizeable free cash flow, can influence earnings per share outcomes and support higher valuation multiples on the company’s cash generation.
See why 9 investors see Cinemark Holdings as 4% undervalued.
Result: Fair Value of $41.82 (UNDERVALUED)
Still, two pressure points could unsettle the Cinemark Holdings story if recent record results prove tied to an unusually strong film slate, and if higher fixed and premium format costs squeeze future margins.
Find out about the key risks to this Cinemark Holdings narrative.
Another View on Cinemark Holdings: Cash Flows Say Something Different
The fair value narrative for Cinemark Holdings leans on earnings forecasts and target P/E multiples, yet the Simply Wall St DCF model tells a cooler story. On that cash flow view, an estimated value of about $35.80 sits below the current $40.04 share price, which points to an overvalued reading rather than a mild 4% discount.
Two competing signals, one from earnings based fair value and one from projected cash flows, leave a simple question for you as an investor: Which set of assumptions feels closer to how Cinemark Holdings will actually convert its box office performance into long run cash generation?
For a closer look at how this cash flow view is built step by step, Look into how the SWS DCF model arrives at its fair value.
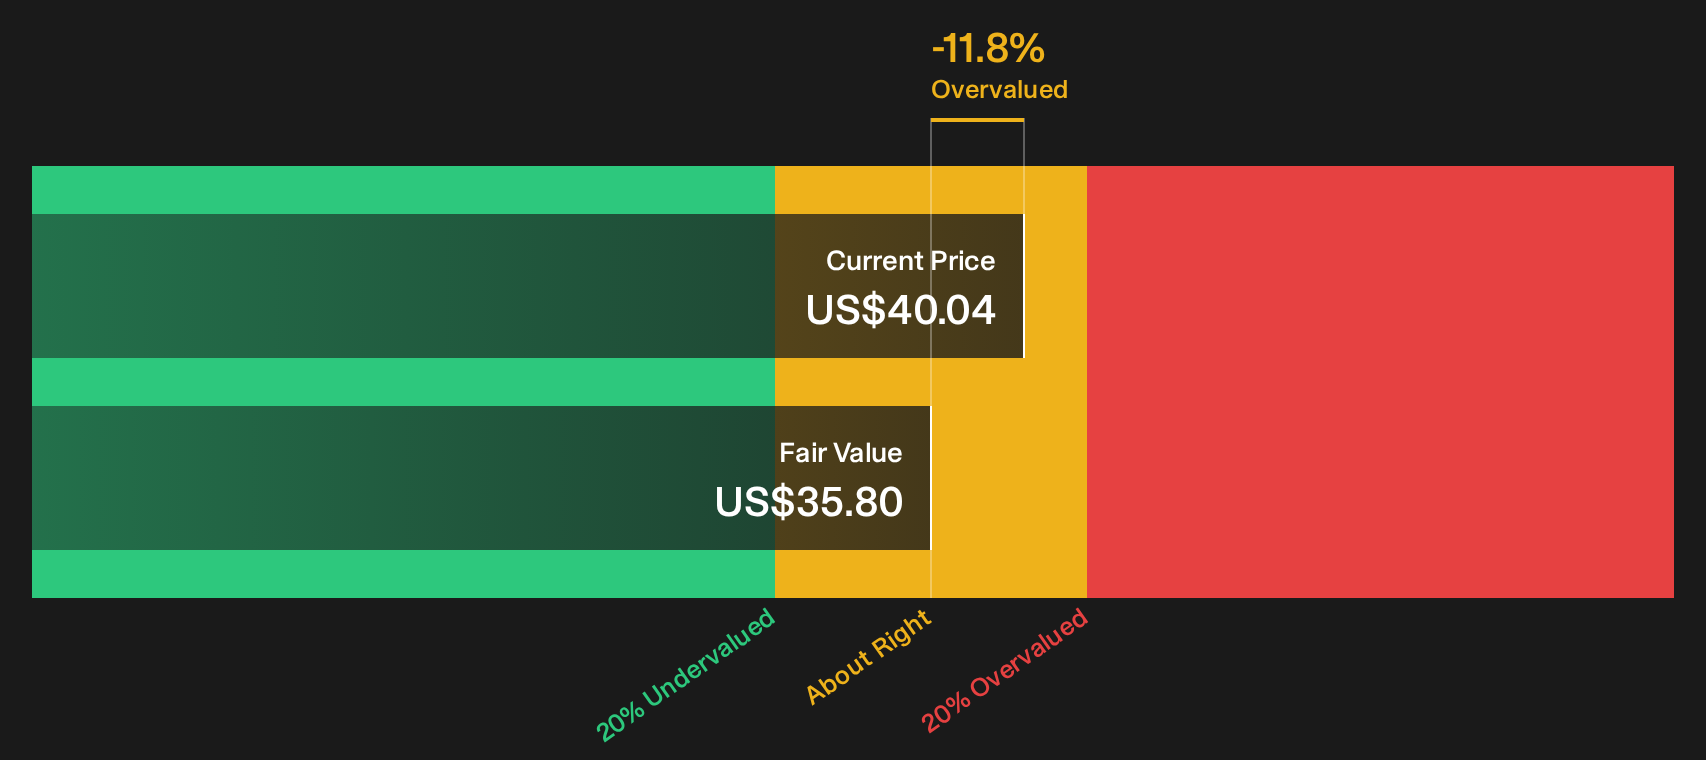
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Cinemark Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and concern around Cinemark Holdings leaves you on the fence, move quickly to check the underlying data and stress test your own stance against the 3 key rewards and 1 important warning sign.
Looking for more Cinemark Holdings sized opportunities?
You have a strong view on Cinemark Holdings now, so do not stop there. Broaden your opportunity set with fresh ideas uncovered by the Simply Wall St Screener.
- Target resilience first by reviewing companies with cleaner finances and fewer balance sheet red flags through our 32 resilient stocks with low risk scores.
- Hunt for quality on sale by scanning businesses that pair solid fundamentals with attractive pricing in the 21 high quality undiscovered gems.
- Anchor your watchlist with financially disciplined operators drawn from a list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com