


EN
Will Higher Revenue And Wider Loss Change Castle Biosciences (CSTL) Narrative
- Castle Biosciences reported third quarter 2026 sales of US$102.89 million, compared with US$83.04 million a year earlier, with a quarterly net loss of US$4.1 million and basic loss per share from continuing operations of US$0.13.
- Across the first nine months of 2026, Castle Biosciences recorded sales of US$290.12 million and reduced its net loss to US$20.68 million, highlighting a business that is adding revenue while still working through cost and profitability pressures.
- We will now look at how Castle Biosciences' higher third quarter sales but wider quarterly loss could reshape its investment narrative.
Compare Castle Biosciences' path to profitability with other healthcare stocks that pair revenue traction with tighter loss profiles by screening for list of solid balance sheet and fundamentals (24 results).
Castle Biosciences Investment Narrative Recap
To own Castle Biosciences, you need to believe its growing test volumes and wider menu in dermatology and gastroenterology can eventually support consistent profits. The latest quarter fits that story on the top line with higher sales, but a wider quarterly loss keeps the focus on cost discipline and reimbursement progress as the near term hurdle.
The key near term catalyst still sits with payer coverage and pricing for assays like AdvanceAD Tx and DecisionDx SCC, because that shapes how much of today’s volume turns into durable cash flow. The biggest risk remains reimbursement setbacks or structurally lower gross margins, and this earnings release does not resolve either issue.
The earnings announcement for the third quarter to 30 September 2026 is the most relevant event here, because it gives you fresh data on how Castle Biosciences is balancing growth and losses. Sales reached US$102.89 million for the quarter and US$290.12 million year to date, while losses persisted, which keeps the conversation firmly on execution.
Those figures tie directly into the existing catalysts. Evidence generation, CMS decisions on AdvanceAD Tx pricing, and ongoing reconsideration for DecisionDx SCC all matter more when the business is already producing hundreds of millions in annual revenue but not yet consistent profits. Higher revenue with a larger quarterly loss simply raises the bar for future reimbursement and margin decisions to move the story forward.
Castle Biosciences' current earnings sit at a loss of US$19.4 million, while analysts project earnings of US$4.3 million by 2029, which implies an earnings increase of about US$23.7 million. Those same forecasts call for revenue growth of 10.3% per year and point to 2029 revenue of US$479.6 million.
Uncover why Castle Biosciences' fair value indicates a 32% potential upside to its current price, which could narrow quickly.
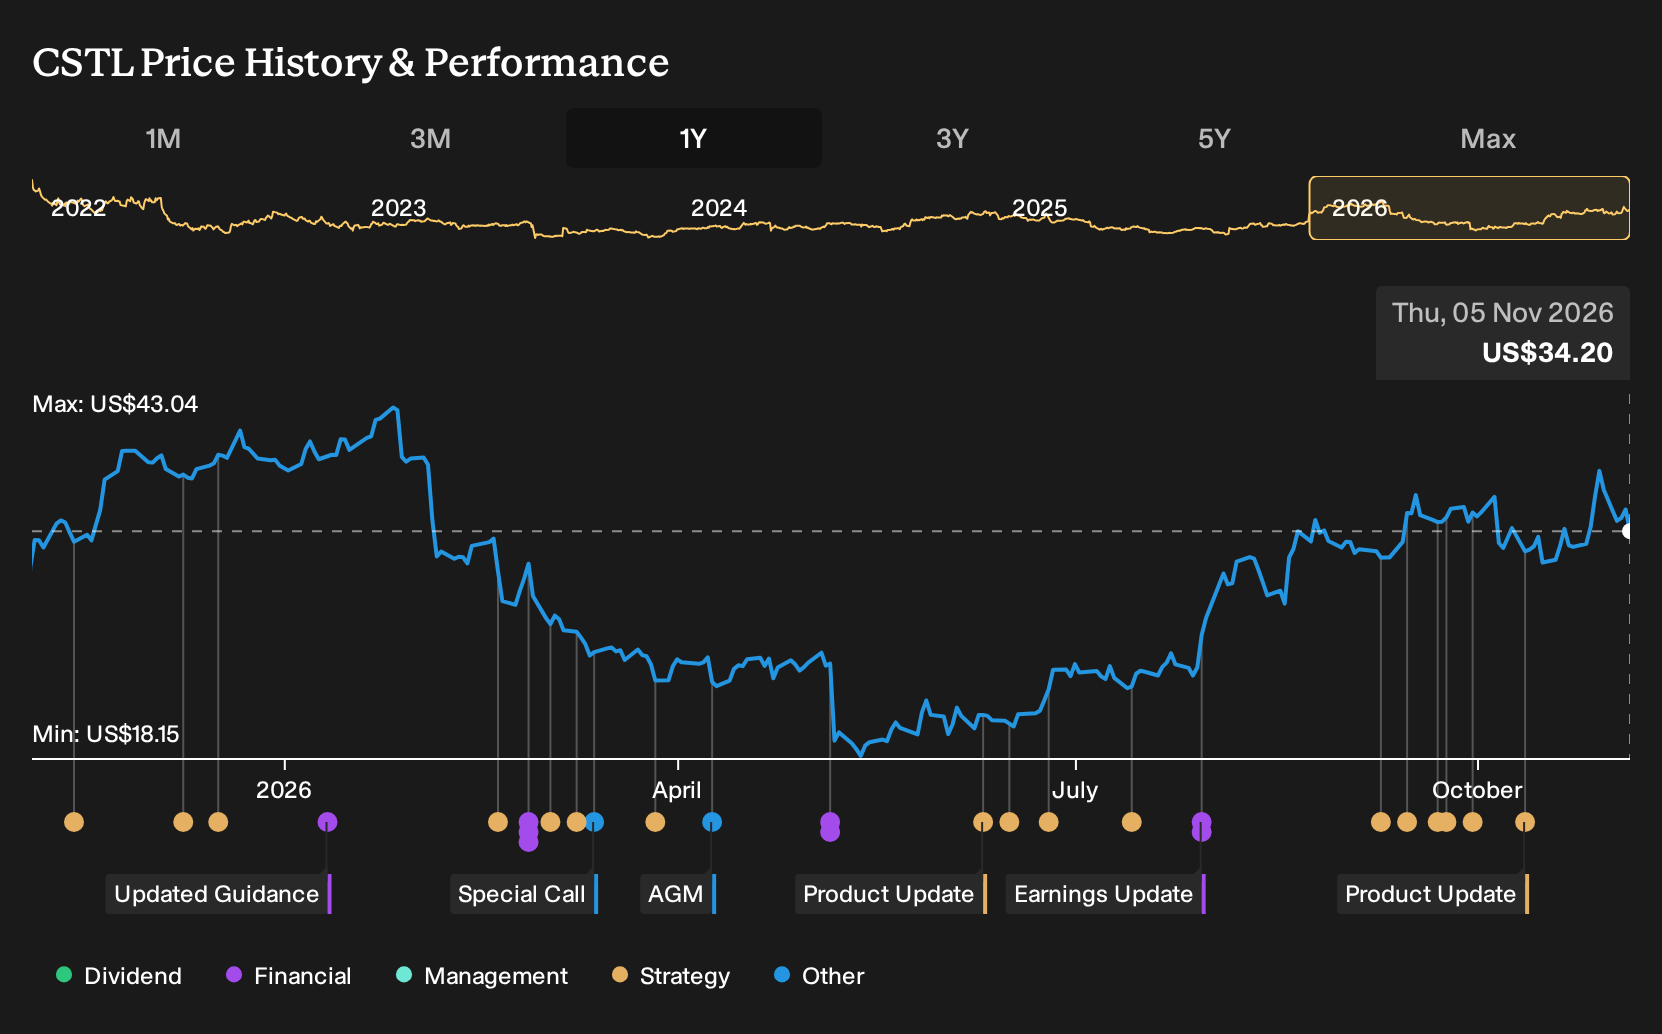
Exploring Other Perspectives
One alternate angle on Castle Biosciences focuses less on reimbursement risk and more on bullish volume and earnings potential. Before this latest report, the most optimistic analysts were modeling annual revenue growth of 12.9% and earnings of about US$4.5 million by 2029. That is far more upbeat than the bears who saw potential earnings falling to about US$27.9 million in losses. These views have not been refreshed for the third quarter numbers yet, so treat them as starting points and explore which version of the story you find more convincing.
Explore 3 other Castle Biosciences fair value estimates, including one that suggests as much as 204% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Castle Biosciences research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Castle Biosciences. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Castle Biosciences' overall financial health at a glance.
Looking For More Investment Ideas Beyond Castle Biosciences?
If this update on Castle Biosciences has sharpened your thinking, use that momentum to widen your opportunity set. The Simply Wall St Screener lets you quickly focus on groups of companies that match the risk, quality, or income profile you care about, instead of scrolling through tickers one by one.
- For investors hunting for underappreciated quality, start with a curated pool of 42 high quality undervalued stocks that combine fundamentals with potential mispricing.
- If stability and capital preservation sit higher on your checklist, narrow your search to 32 resilient stocks with low risk scores that score well on resilience and financial strength.
- Prefer to get in early on quieter stories, before they attract wider attention, by filtering for 21 high quality undiscovered gems with stronger metrics than their profile suggests.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com