


EN
Entergy (ETR) Could Be 8% Below Fair Value Following Strong Q3 Results
Entergy (ETR) is back in focus after reporting third quarter 2026 results on November 2, with higher sales, revenue, and net income compared with the same period a year earlier.
At a share price of US$110.30, Entergy has logged a 17.52% year to date share price return and an 18.13% total shareholder return over the past year. The 5 year total shareholder return of 154.79% points to momentum that has been building rather than fading as investors respond to the stronger earnings print and the recent dividend increase.
Spot similar momentum and income stories to Entergy by scanning our hand picked 6 dividend fortresses, built for investors who care about both price performance and payouts.After a sharp run on upbeat earnings and a higher dividend, Entergy now poses a simple question to potential buyers: pay up for the momentum, or wait and hope for a pullback that the valuation does not justify.
Most Popular Narrative: 8% Undervalued
Entergy is trading at $110.30 against a narrative fair value of $119.93. This frames the recent rally as still short of consensus upside when that valuation is discounted back at 7.24%.
Substantial long term electricity demand growth from industrial development, population migration to the Gulf South, and large scale data center expansions in Entergy’s service territory now includes approximately 7 to 12 GW of hyperscale data center potential, 3 to 5 GW of traditional industrial demand, and signed agreements with AWS and Meta that together support the updated outlook for roughly 8.5% to 9% annual retail sales growth, which could lift regulated revenue and earnings over time.
See why 29 investors see Entergy as 8% undervalued.
Result: Fair Value of $119.93 (UNDERVALUED)
Still, the thesis can slip if Entergy faces tougher regulatory pushback on big projects or if its larger capital plan needs additional, more expensive funding.
Find out about the key risks to this Entergy narrative.
Another View: Entergy On Earnings Multiples
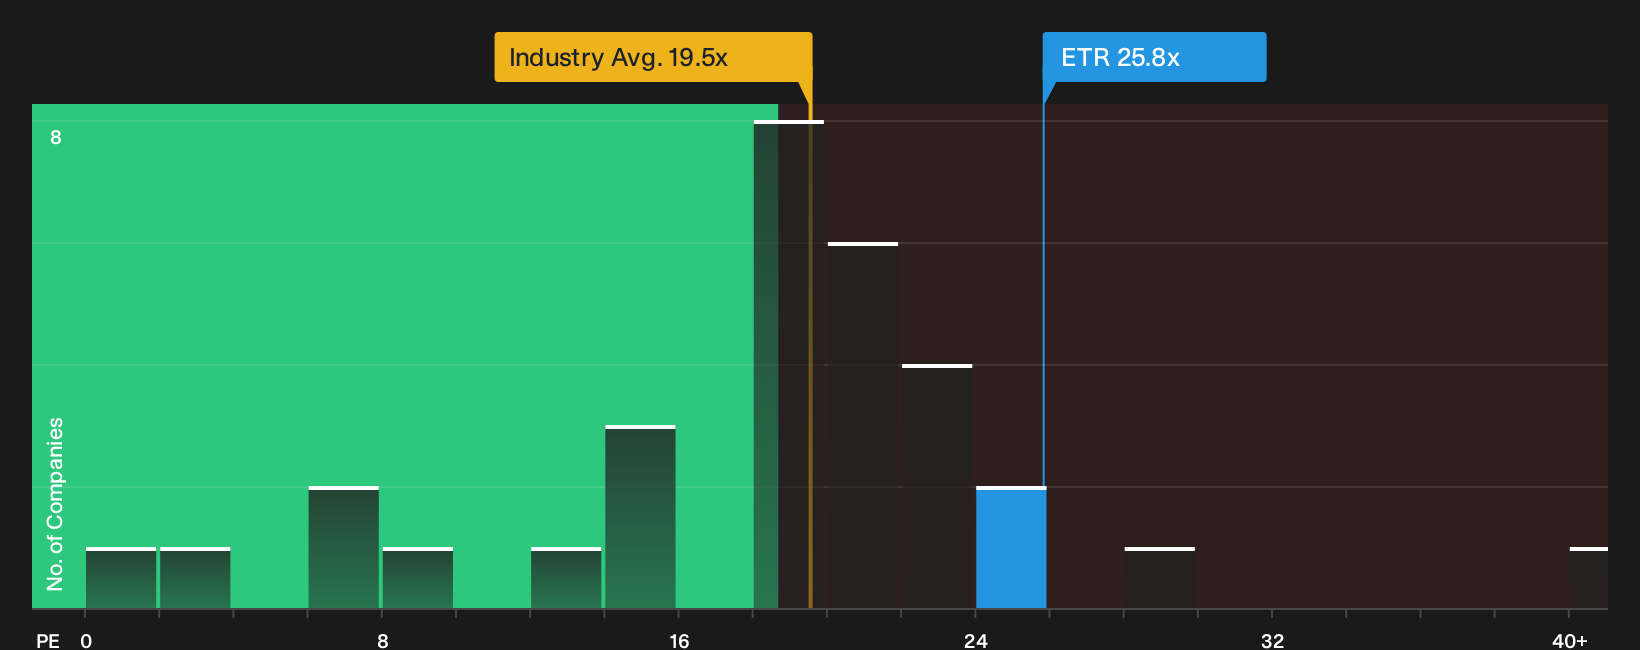
That 8% upside story runs into a very different signal once you look at Entergy through its current P/E. The stock trades on 25.8x earnings, while peers sit closer to 17x and the fair ratio sits at 25.2x, which points to limited room for error if sentiment cools.
For an investor weighing fresh capital today, the question becomes simple. Is paying a premium P/E for Entergy’s growth profile worth the valuation risk if sector expectations reset, or is patience the better ally here?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Entergy so far. If you want to move quickly yet stay grounded in your own work, consider both sides of the story with 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Entergy?
If Entergy has you thinking harder about where to put fresh money to work, do not stop at a single ticker. Scan broader opportunities with targeted screeners that match your priorities.
- Target quality at a discount by reviewing the 42 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect their underlying strengths.
- Prioritize resilience and sleep better at night by focusing on the 32 resilient stocks with low risk scores that aim to limit unpleasant surprises when markets get choppy.
- Get ahead of the crowd by checking the 21 high quality undiscovered gems that combine robust data with businesses that many investors may still be overlooking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com