


EN
Supermicro Stock Has The Bull Case Changed After Earnings Beat
- Super Micro Computer reported first quarter fiscal 2027 sales of US$19.95b and net income of US$1.59b, and then lifted its full year revenue outlook to a range of US$72b to US$82b on strong AI data center demand.
- Management paired this guidance hike with new AI infrastructure collaborations, including racks built with SambaNova SN50 RDU chips alongside NVIDIA GPUs, as well as expanded enterprise focused partnerships.
- We will now look at how Super Micro Computer's upgraded fiscal 2027 revenue outlook reshapes the existing investment narrative around AI infrastructure.
Super Micro Computer Investment Narrative Recap
To own Super Micro Computer, you need to believe its AI focused server and full rack model can stay relevant as customers scale out data centers, and that higher value Data Center Building Block Solutions keep gaining traction. The raised fiscal 2027 revenue outlook suggests management sees strong demand visibility, but also raises the execution bar on capacity, supply chain and delivery.
The key near term swing factor is whether large AI data center projects continue converting to shipments without major delays while working capital intensity improves from today’s extended cash cycle. The biggest risk remains concentrated multibillion dollar orders plus thinner priced AI deals that could pressure gross margin and leave free cash flow tight even when sales are strong.
The SambaNova SN50 collaboration that Super Micro Computer just highlighted is closely tied to this AI infrastructure story. Management plans to build disaggregated inference racks that combine SN50 RDU chips with NVIDIA GPUs, with Super Micro integrating, testing and servicing full systems across NeoClouds, sovereign clouds and on premises enterprise deployments.
This matters because the most important catalyst is still ramping full rack AI factories, not just selling individual servers. If these SambaNova based racks see steady uptake, they could deepen Super Micro’s role in inference workloads and broaden the customer base. They also add execution complexity around multi vendor integration, on site support and potential margin pressure on very large projects.
What The New Super Micro Computer Forecasts Assume
Super Micro Computer's analyst narrative points to forecast revenues of US$93.1b and expected earnings of US$3.7b by 2029. That outlook is based on an assumed 33.6% yearly revenue growth rate and an increase in earnings of about US$1.5b from US$2.2b today.
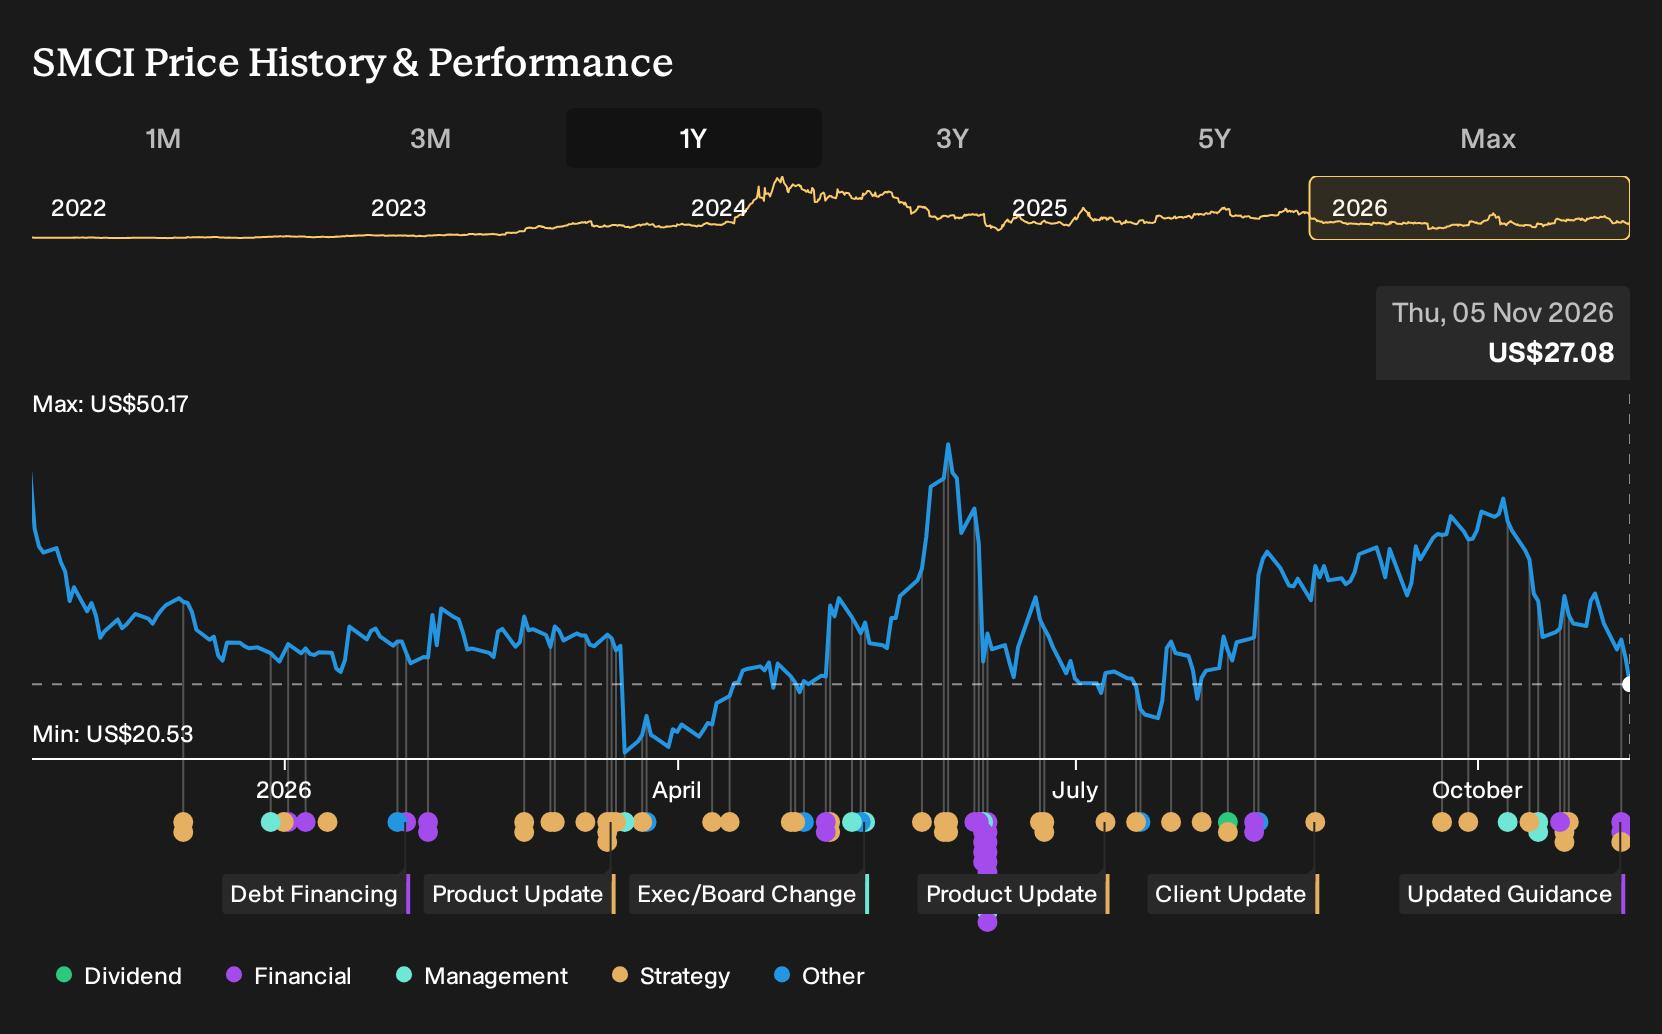
Uncover why Super Micro Computer's fair value indicates a 60% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view puts cash flow front and center. The most cautious Super Micro Computer analysts were working off revenue of about US$83.4b and earnings near US$3.0b by 2029, yet still set a low price target. That gap shows how sharply opinions differ. Use this earnings surprise to reassess which story you find more convincing.
Explore 9 other Super Micro Computer fair value estimates, including one that suggests up to 10% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Super Micro Computer research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Super Micro Computer. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Super Micro Computer's overall financial health at a glance.
Looking for more Super Micro Computer style investment ideas?
If the Super Micro Computer story has sharpened your thinking about AI infrastructure, you can use that same lens to scout other opportunities with the Simply Wall St Screener.
- If you want resilient businesses that may help balance out higher risk positions like AI infrastructure plays, consider checking a set of 32 resilient stocks with low risk scores that can add more defensive exposure to your watchlist.
- If income is a priority alongside growth, investors often look for companies with strong cash generation supporting payouts. In that case, a group of 6 dividend fortresses can be a useful hunting ground.
- If you are hunting for mispriced opportunities with solid fundamentals, use a curated 42 high quality undervalued stocks to quickly spot candidates that might warrant a deeper look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com