


EN
Fortuna Mining (TSX:FVI) Stock Trades At A Discount To Earnings
Fortuna Mining has delivered a powerful 220.5% share price return over the past three years, which naturally puts the spotlight on whether the current valuation is still grounded in its earnings power. With the stock now around $13.30 and fresh project milestones on the table, the question is how much of that future profit story is already reflected in the price.
- A roughly 220.5% gain over three years raises the stakes for holders, who now need the company’s earnings profile to justify a much higher entry point than before.
- Recent progress at the Bambadji and Diamba Sud projects, alongside solid operating cash generation, can shape expectations for future profit levels and the timing of cash flows that matter for earnings based valuation.
- There is a second opinion on Fortuna Mining worth weighing. See what analysts think Fortuna Mining's shares could be worth.
The issue now is whether Fortuna Mining's recent share price, after such a strong multi year run and a string of project advances, is adequately supported by its earnings compared with the industry average.
If you are weighing Fortuna Mining against other gold producers, a simple way to get context is to compare it with 33 elite gold producer stocks.
Does Fortuna Mining Look Undervalued on Earnings?
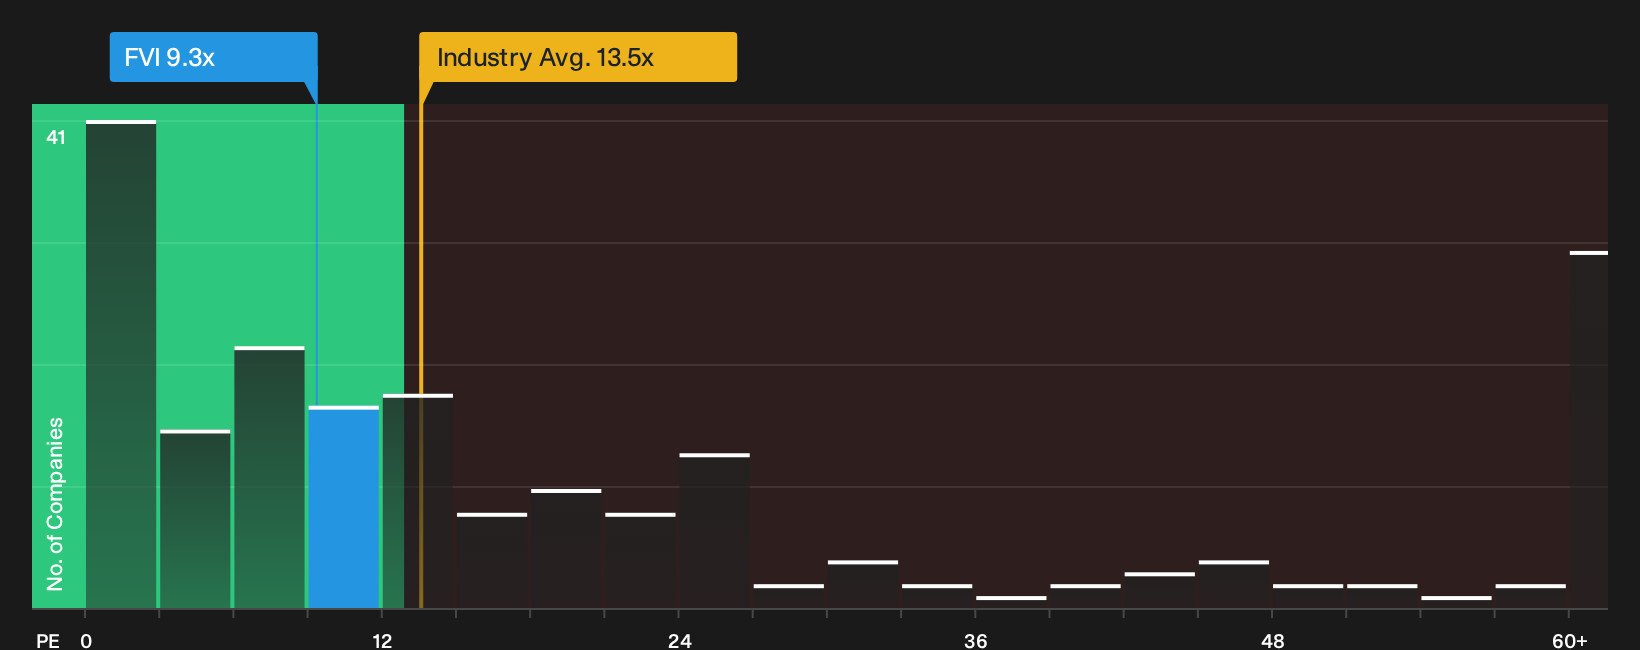
The P/E ratio is a useful lens for Fortuna Mining because profits and cash generation are central to how investors are framing the new projects. On this measure, the stock trades at about 9.3x earnings, which is below the Metals and Mining industry average of roughly 13.5x and well under the peer group closer to 34.4x.
Because Fortuna has recently reported strong Q3 2026 free cash flow and advanced Bambadji and Diamba Sud, the current discount on the P/E multiple points to an undervalued profile relative to the wider gold and metals producers. That gap suggests the market is still applying a cautious label to the expansion and permitting risks, even as the earnings multiple prices the shares below sector norms. Explore the numbers behind Fortuna Mining's P/E valuation.
The Fortuna Mining Narrative: What Would Justify Today's Price?
Narratives for Fortuna Mining pick up where the valuation puzzle leaves off, spelling out what kind of future growth, margins and earnings profile would need to unfold for the current P/E discount to either narrow or widen. Each scenario on the Community page ties a fair value estimate to a specific mix of project catalysts and risks, so you can track over time which broad version of Fortuna Mining's story is actually playing out.
One of the top community narratives on Fortuna Mining: 32% undervalued
"Expansion projects and exploration in West Africa and Latin America position Fortuna to boost production, access new revenue streams, and support long-term growth..."
Discover why this Narrative puts Fortuna Mining at 32% undervalued.
One more Fortuna Mining check that belongs beside the earnings multiple
Price ratios and project stories tell you where Fortuna Mining is today, but professional models looking a few years ahead offer a different reference point for what might be baked into the current tag. Explore where analysts expect Fortuna Mining to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com