


EN
How Investors Are Reacting To Acadia Pharmaceuticals (ACAD) Raised Revenue Guidance
- Acadia Pharmaceuticals reported third quarter 2026 revenue of US$342.29 million and net income of US$53.52 million, then lifted full year revenue guidance to a range of US$1.265b to US$1.295b after stronger than expected contributions from DAYBUE and NUPLAZID.
- The earnings beat came alongside a new U.S. patent allowance for DAYBUE and progress for remlifanserin, which together indicate a longer commercial runway and a more developed pipeline than headline quarterly numbers alone might suggest.
- We will now look at how Acadia Pharmaceuticals' higher full year revenue guidance could influence the broader investment narrative around the business.
Scan how Acadia Pharmaceuticals fits into the broader hunt for CNS and rare disease opportunities by reviewing our curated list of 21 high quality undiscovered gems, which may still be flying under most investors' radar.
Acadia Pharmaceuticals Investment Narrative Recap
To own Acadia Pharmaceuticals, you need to be comfortable with a story that leans heavily on DAYBUE and NUPLAZID continuing to support the P&L while the pipeline matures. The higher full year revenue guidance points to solid commercial execution in the near term, but Q3 data also show net income and EPS below last year, which keeps cost discipline and product mix squarely in focus.
The key near term catalyst is clear progress on remlifanserin in dementia related psychosis, since confidence around that program influences how investors think about the long term opportunity. The biggest current risk is that expectations for DAYBUE and NUPLAZID prove too optimistic on duration of therapy, pricing, or competition, which could cap operating leverage even if guidance edges higher.
The raised 2026 revenue outlook to US$1.265b to US$1.295b is the announcement that ties closest to the latest results. It signals management sees enough momentum in DAYBUE and NUPLAZID to tighten the range, even though Q3 net income of US$53.52 million and EPS of US$0.31 sit below the prior year period.
For investors, that guidance tweak matters because it frames how much breathing room Acadia Pharmaceuticals has to keep funding remlifanserin and earlier programs after trimming R&D expectations. If future quarters echo this mix of solid top line and pressured earnings, the valuation debate is likely to hinge less on a single quarter and more on how convincingly management executes the remlifanserin phase III plan and supports DAYBUE growth.
Acadia Pharmaceuticals' outlook points to projected revenue of US$1.7b and earnings of US$329.3 million by 2029. This corresponds to 13.5% annual revenue growth and a US$51.2 million decline in earnings from US$380.5 million today.
Uncover why Acadia Pharmaceuticals' fair value indicates a 44% potential upside to its current price, which could narrow quickly.
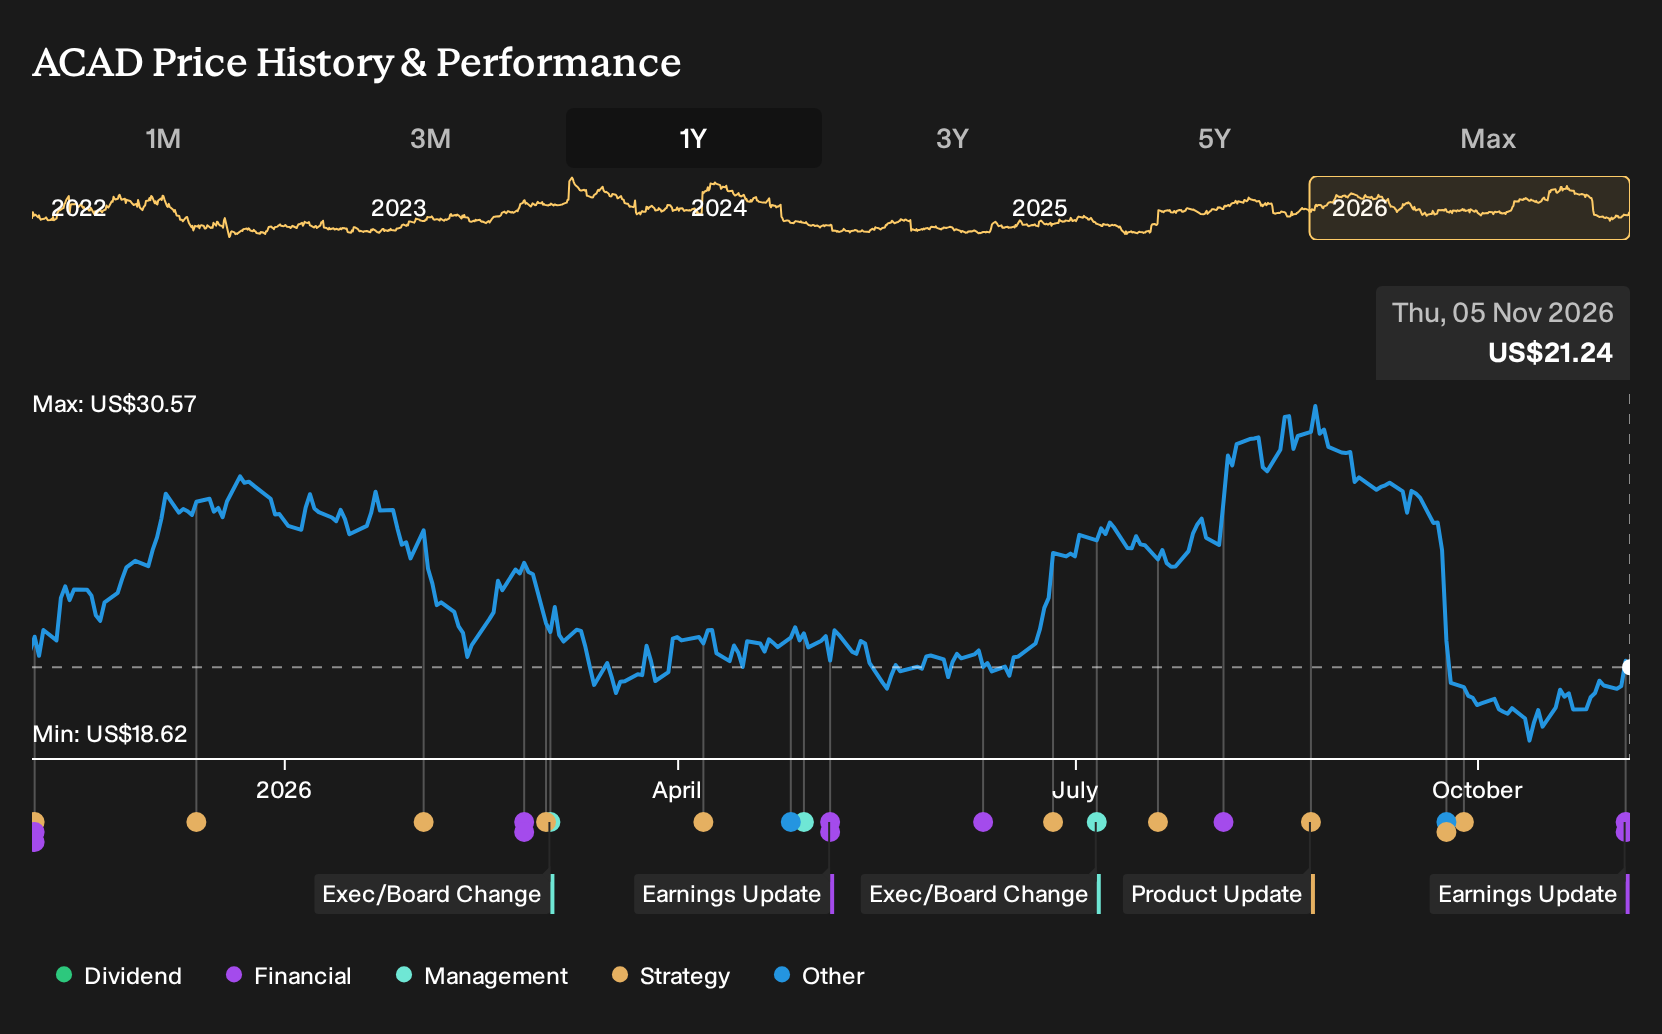
Exploring Other Perspectives
One alternate view fixates on dilution risk. The most pessimistic analysts were modeling revenue of about US$1.6b and earnings near US$169.4 million by 2029, assuming ongoing equity issuance would hold back per share progress even if Acadia Pharmaceuticals hits guidance. Q3’s raised outlook could push that story to evolve.
Explore 5 other Acadia Pharmaceuticals fair value estimates, including one that suggests as much as 9% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Acadia Pharmaceuticals research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Acadia Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Acadia Pharmaceuticals' overall financial health at a glance.
Looking for more investment ideas beyond Acadia Pharmaceuticals?
If Acadia Pharmaceuticals has you thinking about where to deploy your next dollar, it can help to scan a wider field of opportunities that match your risk tolerance and income goals.
- If capital preservation comes first for you, filter for steadier candidates through our 32 resilient stocks with low risk scores and keep the focus on resilience.
- If you care about balance sheet strength and business quality, start with a list of solid balance sheet and fundamentals (24 results) and narrow in on companies with cleaner fundamentals.
- If you want to go hunting for potential mispricings, use our 42 high quality undervalued stocks and zero in on stocks where quality and price may still be out of sync.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com