


EN
Is Magnolia Oil & Gas (MGY) Below Fair Value After Its Dividend Update?
Magnolia Oil & Gas has delivered a 29.9% total return over the past 5 years, yet the recent pullback leaves investors asking whether the current share price still lines up with what its earnings can justify. With the stock closing at US$23.52 and fresh company updates on capital returns, the key issue is how much of those profits the market may already be pricing in.
- A 29.9% gain over 5 years places real weight on the question of whether Magnolia Oil & Gas earnings are strong enough to support today’s valuation.
- The combination of a regular cash dividend and an expanded share repurchase plan can change how much of the firm’s earnings ultimately accrue to each share over time.
- Your read on Magnolia Oil & Gas is one view; the desks covering it have another. See what analysts think Magnolia Oil & Gas's shares could be worth.
The issue now is whether Magnolia Oil & Gas current market value is adequately supported by the profits it generates today and what investors expect from those earnings over time.
If you are weighing Magnolia Oil & Gas against other opportunities that focus squarely on earnings support and valuation, it can help to compare it with 42 high quality undervalued stocks.
Is Magnolia Oil & Gas Still Cheap on Earnings?
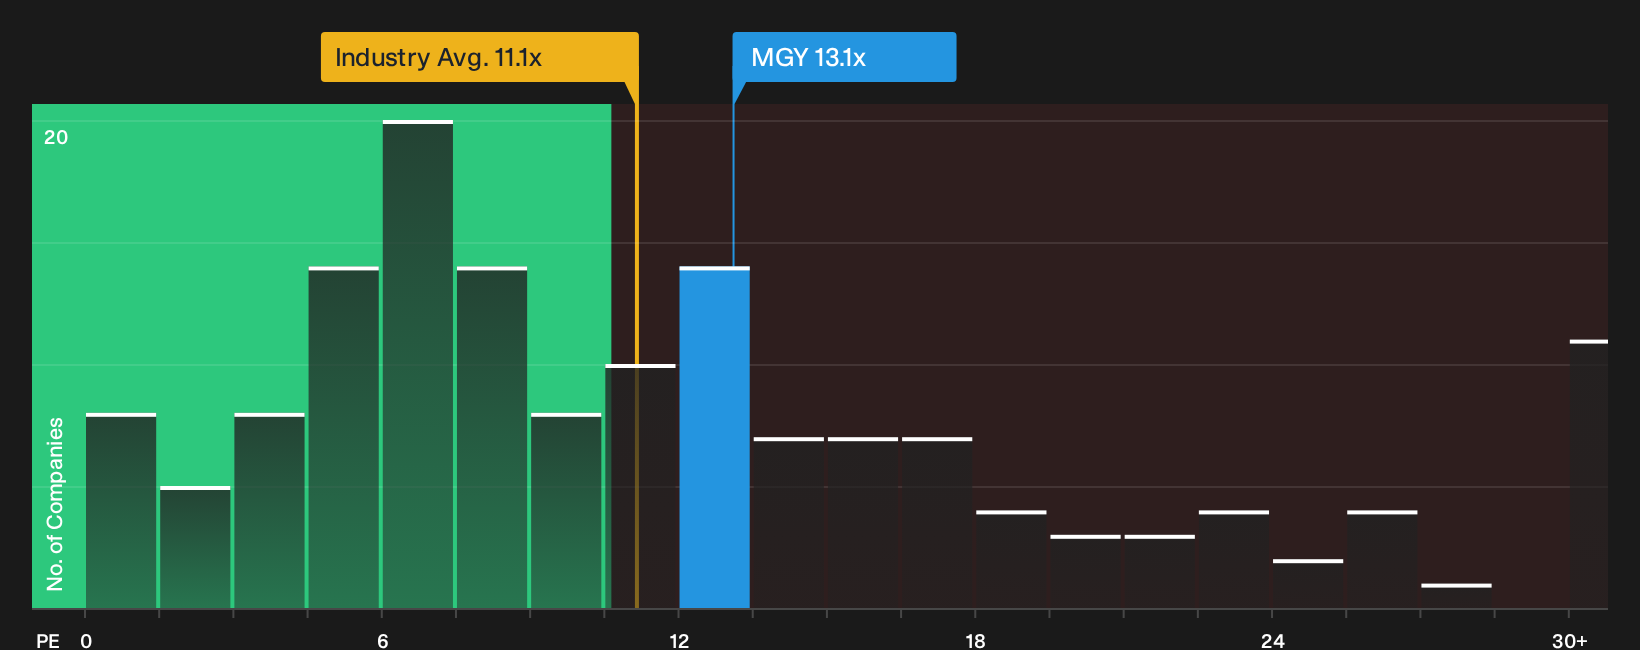
The P/E ratio lines up cleanly with Magnolia Oil & Gas because earnings remain the key anchor for how this producer is valued. At a P/E of 13.1x, the stock trades below the broader Oil and Gas sector average of 11.1x, so the market is paying a somewhat higher earnings multiple than it does for the typical peer in the industry. Against a peer group closer to 25.2x, that same P/E looks far more restrained, which suggests investors are not pricing Magnolia as aggressively as some comparable stocks.
The tailored fair multiple model, which factors in Magnolia Oil & Gas specific growth profile, profitability and risk, points to a higher P/E than where the shares change hands today, so the current valuation screens as undervalued on this framework. Because the recent dividend declaration and extended buyback plan return more capital directly to holders, the earnings yield implied by a 13.1x P/E can matter more for anyone weighing what they are paying for each dollar of profit. To see how large that potential gap is in numerical terms and how it compares across the sector, use. Explore the numbers behind Magnolia Oil & Gas's P/E valuation.
The Magnolia Oil & Gas Narrative: What Would Justify Today's Price?
Narratives pick up where Magnolia Oil & Gas' P/E discussion leaves off, since they spell out the earnings, margin and growth paths that would need to play out for the stock to trade meaningfully higher or lower than it does today. Instead of one static figure from a ratio or model, they lay out the future that figure leans on so you can watch over time whether that story actually holds. Narratives for Magnolia Oil & Gas live on Simply Wall St's Community page and provide that context in a structured way.
One of the top community narratives on Magnolia Oil & Gas: 28% undervalued
"The main thing that has to go right is that Magnolia Oil & Gas executes on integrating WildFire and the 2026 bolt-ons to capture the targeted cost savings..."
Discover why this Narrative puts Magnolia Oil & Gas at 28% undervalued.
One more Magnolia Oil & Gas angle worth checking before you move on
Everything so far has focused on what Magnolia Oil & Gas looks like today, but professional coverage also maps out where the business may sit a few years from now. This can frame how you read the current valuation. Explore where analysts expect Magnolia Oil & Gas to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com