


EN
Far exceeding expectations of 165,000 non-farm payrolls, rekindling the US economy's “soft landing” narrative? Machinery sales pressure is difficult to stop the momentum of AI and technology repair after the sharp decline
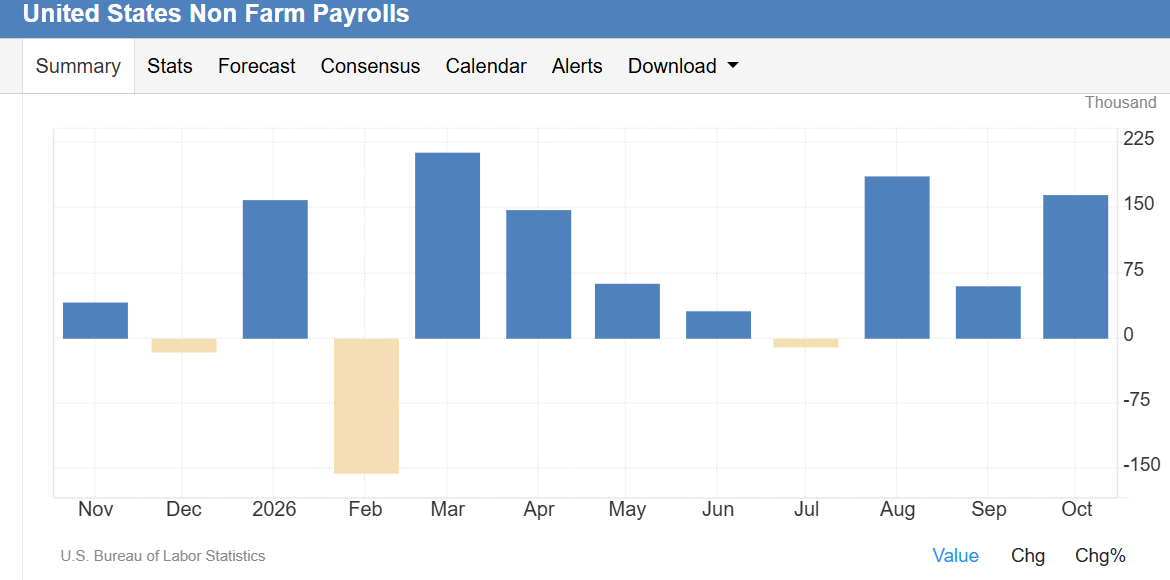
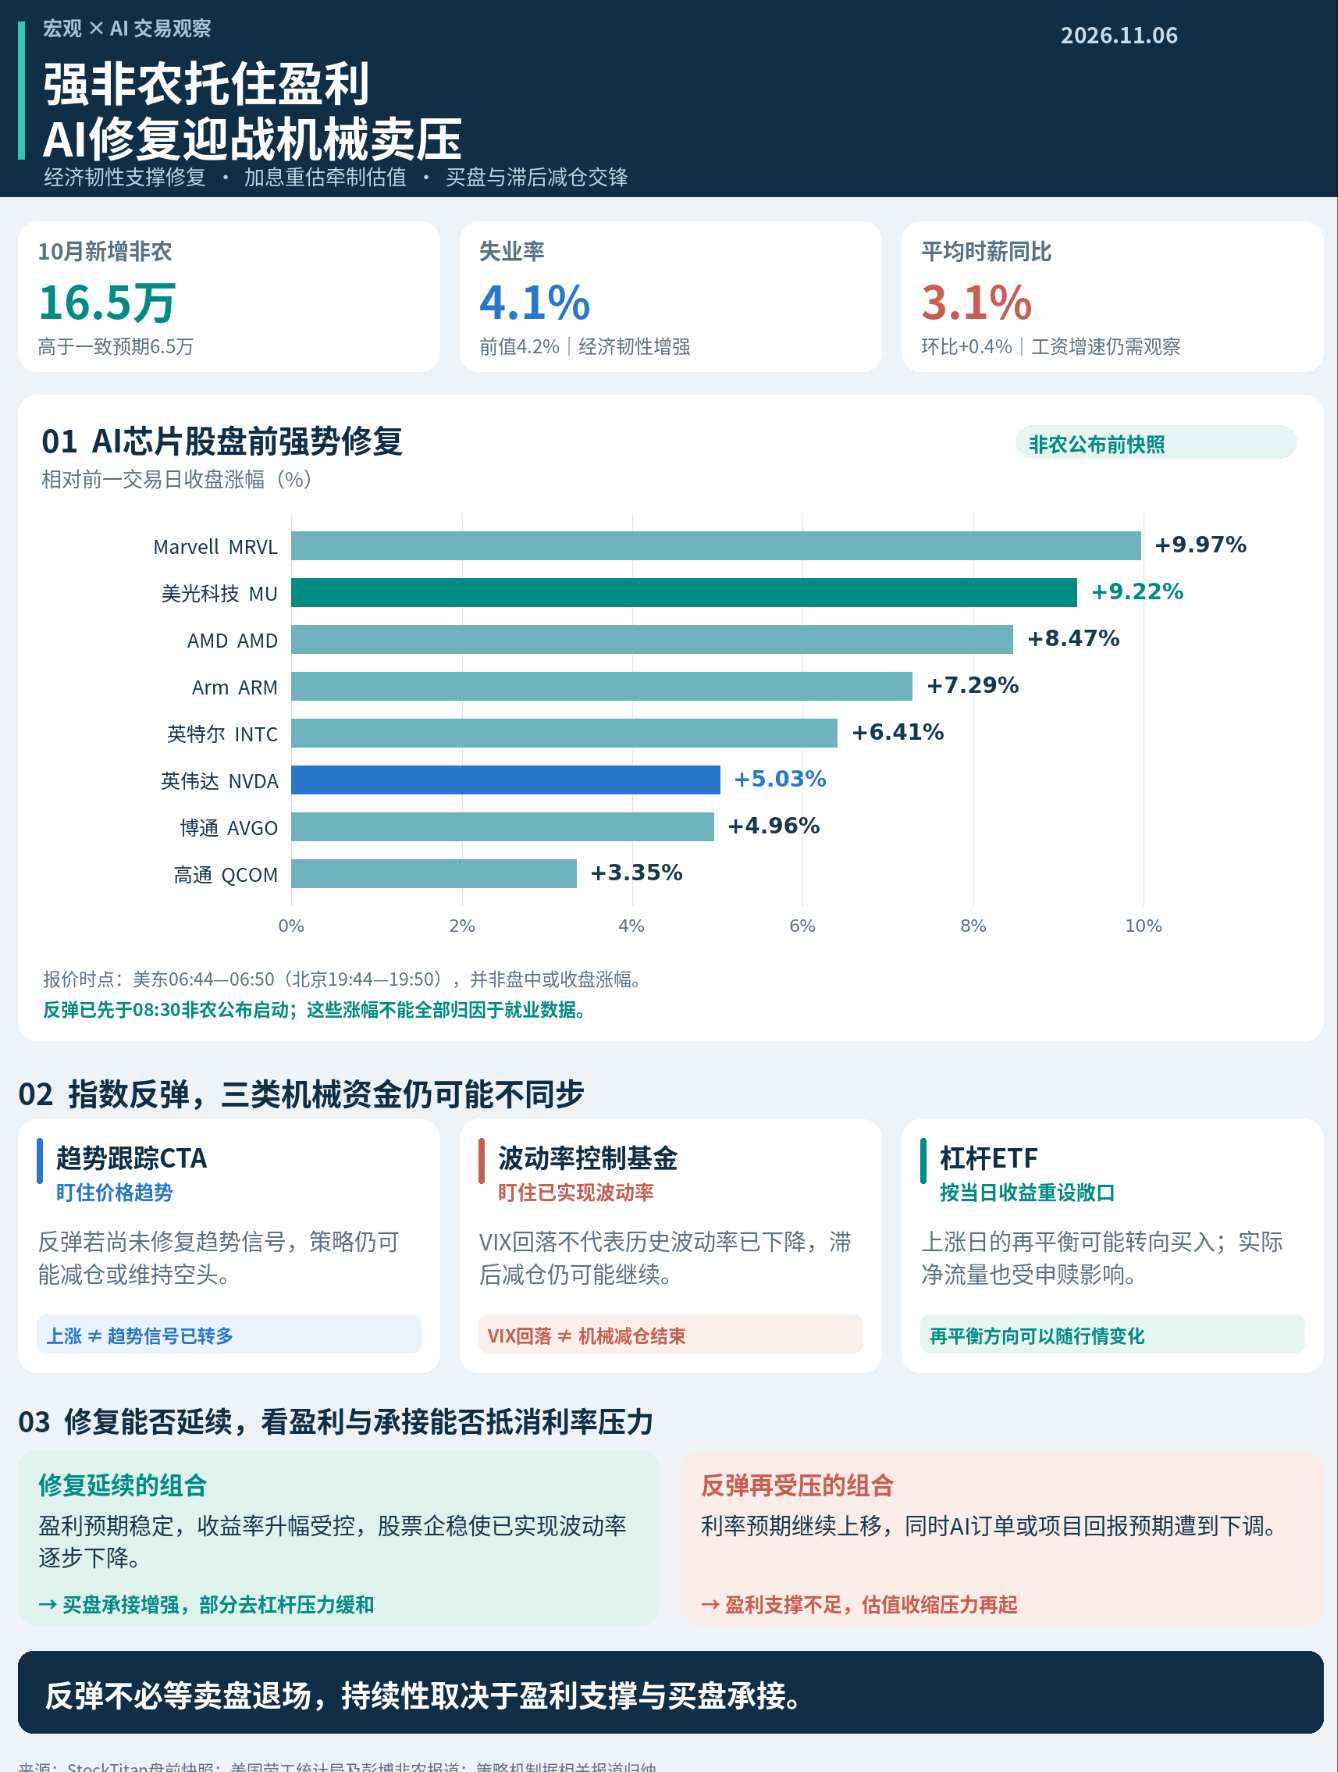
The Zhitong Finance App learned that the October labor market data report just released by the US government shows that the US non-farm payrolls market added 165,000 jobs on a large scale in October, far exceeding the median market forecast of 65,000 people. The unemployment rate fell to 4.1%. The total employment data for the first two months rose by 84,000 people, providing the US stock market, which experienced intense sell-off of AI computing power and semiconductors, and even broader technology stock themes on Thursday and Friday, and risk asset sectors such as the global stock market support.
At the same time, another important piece of information for financial markets revealed by the non-farm payrolls report is that non-farm payroll growth covers many industries, and the year-on-year wage growth rate is still low in recent years. To a large extent, this means that a strong economy can not only improve corporate profit expectations, but also give the Federal Reserve more confidence to continue dealing with inflation; a rebound in technology stocks, rising US bond yields, and pressure on gold can occur simultaneously, and the market is simultaneously absorbing the growth benefits brought about by the expansion of AI investment in the US and the rising pressure on interest rate expectations.
The US added 165,000 new non-farm payrolls in October, which can be described as far exceeding the consensus expectations of 65,000 economists. Combined with a total increase of 84,000% in the previous two months, it once again strengthened the judgment that residents' income, consumer demand, and corporate profits can maintain resilience.
The non-farm payrolls report showed a 3.1% year-on-year increase. Although higher than previously predicted, they are still low in recent years, leaving room for a soft landing narrative; at the same time, strong employment also gave the Fed more confidence to focus on inflation. After the data was released, the market's bet on the December interest rate hike rose from about 70% to 78%, and US bond yields and the US dollar rose accordingly.
This repricing did not immediately interrupt the pre-market rebound initiated by technology stocks: NASDAQ futures are still up about 1.4%, indicating that post-decline carrying capacity is playing against higher capital costs. Against the backdrop of Barclays estimating that the volatility target strategy for the next 24-48 hours may release pressure to reduce positions by about $135 billion, whether the rebound can continue depends on active buying and whether possible short compensation can absorb the lagging selling pressure. What the market is trading is whether the strong resilience outlook for the US economy, which has been dominated by the AI super-bull market over the years and trillion-dollar AI investments and expectations of AI-driven productivity changes, can provide profit support for technology stocks experiencing reduced valuations, and the rise itself may gradually improve trends and volatility conditions, creating room for subsequent recovery.
Employment exceeds expectations and wages are still moderate: the soft landing is supported, and the Fed is encouraged to raise interest rates further
Prior to the announcement of Non-Agriculture in October, the median value of the Reuters and Bloomberg surveys all pointed to 65,000 new jobs, and the unemployment rate remained at 4.2%. Among the major institutions, Goldman Sachs, Bank of America, and J.P. Morgan Chase all forecast 75,000 people, Morgan Stanley predicts 60,000 people, Deutsche Bank predicts 55,000 people, and Barclays forecast 50,000 people. As a result, the actual results of 165,000 people were not only 100,000 more than the consensus, but also clearly surpassed the relatively optimistic judgments of several large banks. What the market originally expected was a moderate recovery from the September low, but what was actually obtained was a report of a marked increase in recruitment efforts.
What is more significant is that employment improvements are continuous and broad: new jobs were raised from 133,000 to 186,000 in August, 29,000 to 60,000 in September, and an average of about 137,000 new people added in the last three months after the revision. In October, professional and commercial services increased by 70,000, healthcare by 42,000, transportation and warehousing by 25,000, and manufacturing by 19,000.
The above series of recently published data weakens the judgment that “a sharp drop in recruitment indicates that the economy is about to stall,” and provides a more solid foundation for the growth of residents' income, consumer demand, and corporate income. In particular, for technology companies closely linked to the AI computing power and AI smart device frenzy, corporate customer budgets and terminal demand are supported, helping to mitigate market concerns that the risk of AI capital expenditure will be further extrapolated to an overall profit decline.
Wage data needs to look at both expected differences and historical positions. The average hourly wage increased 0.4% month-on-month and 3.1% year-on-year, higher than previous expectations of 0.3% and 2.9%; however, according to Bloomberg's comparison, 3.1% is still the same as the lowest year-on-year growth rate since 2021. Therefore, the newly released overall non-farm payroll report cannot be directly described as wage inflation getting out of control again, nor can we ignore its relatively strong side of expectations. It reinforces the judgment that “the economy can withstand further austerity” rather than proving that the Federal Reserve must continue to raise interest rates sharply. Resilience in employment gives policymakers more room to focus on inflation. Whether the soft landing can finally be realized will still depend on the subsequent combination of wages, productivity, energy prices, and overall prices.
The rebound in technology goes hand in hand with the fall in bonds: the market re-weighs profit support and capital costs
This report comes at a time when positions are highly vulnerable. After the Democratic Party gained control of both houses of Congress, market concerns about data center approval, construction pace, and return on investment heated up. On Thursday, the Nasdaq 100 fell 6.36%, the biggest one-day decline since March 2020; the S&P 500 fell 4.36%, the Philadelphia Semiconductor Index fell 12.25%, and VIX surged about 70% to around 28.
Asian trading continued the overnight shock on Friday: South Korea's KOSPI closed down 6.02%, falling below 5,000 points and triggering a meltdown, closing back to 5059.69 points; Nikkei 225 fell 5.96%, and Taiwan's weighted index fell 4.51%. It should be noted that these Asian closures occurred before the announcement of the non-agricultural sector, reflecting the risk reduction of AI transactions, rather than a reaction to strong employment data.
After such a sharp decline, chip stocks were accepted before the market. Jefferies stock strategist Jane Gibbons attributed Thursday's sell-off to a concentrated collision of AI spending, policies, and inflation concerns, believing that the market reaction did not mean that corporate fundamentals had been completely reset. At 8:31 EST, or at 13:31 Beijing time, NASDAQ 100 futures still rose 1.37%, S&P 500 futures rose 0.11%, and Dow futures fell 0.96%; Lu Transparency did point out that S&P futures narrowed their gains after the data was released. The trading clue that can be deduced from this is that the trading state at the time was that technology stocks continued to fall and then recovered, and at the same time were constrained by interest rate hikes and repricing. It cannot yet be summed up as strong Feinong driving the overall rise in US stocks.
The underlying logic behind this is that stocks also reflect future profits, discount rates, and risk premiums. Strong employment can reduce concerns about the recession and increase the credibility of profit delivery; even if treasury bond yields rise, as long as this support is sufficient to offset valuation pressure, stocks may rise. In other words, technology stocks can continue to rebound when US bond yields rise because stock prices are simultaneously affected by profit expectations, risk-free interest rates, and stock risk premiums. Strong employment mitigates concerns about economic recession and enhances corporate profit expectations; as long as profit support and the benefits brought by lower risk premiums are sufficient to offset the valuation pressure of rising interest rates, stock prices may still rise.
Bonds, on the other hand, are more directly affected by rising policy interest rate expectations: in the early days of data release, the 10-year US Treasury yield rose to about 4.898%, up more than 6 basis points, and spot gold was reported at about 4041.89 US dollars/ounce, falling more than 1%. Interest rate hikes are expected to support the advantage of US dollar spreads and raise the opportunity cost of holding interest-free gold. However, the October employment data reflects the economic situation before the election, and does not automatically eliminate the pressure to approve and finance future data center projects; for developers with highly leveraged computing power, financing costs are still another independent constraint.
The current bond retracement is also testing the true position of the US debt bulls before. Prior to the announcement of Fei Nong, the 10-year yield on some options transactions fell further to 4.7% or even 4.35%, but not all of the debt buying logic was based on weak employment.
Jamie Patton, TCW's co-head of global interest rates, said earlier that even with strong data, they are more likely to take advantage of falling bonds to increase their holdings; in the BMO survey, 48% of investors are preparing to buy in the bond pullback caused by non-agricultural farmers, which is higher than the six-month average of 43%. These top institutional investors are also concerned about falling oil prices, falling inflation expectations, and safe-haven needs. Therefore, a short-term rebound in yield does not mean that bond bulls have fully accepted losses. Whether continuous acceptance can occur in the future will directly affect the discount rate pressure faced by technology stocks.
“Anticipate Your Predictions” continues to play: the rebound doesn't have to wait for the institutional forces dominated by “fast money” to all exit the market
The reason for the sharp decline on Thursday is that after the Democratic Party controlled the majority of seats in both houses of the Senate and the House of Representatives, market concerns about the Democratic Party's strict policies related to AI data center construction triggered a fundamental reassessment, while broken trends, rising volatility, and leverage adjustments further amplified selling pressure. J.P. Morgan estimates that leveraged ETFs cut their stock exposure by more than 60 billion US dollars at the end of the day, with about 90% concentrated on technology-related products; for subsequent volatility target strategies, J.P. Morgan estimates that it will be about 50 billion US dollars in the next few days, while Barclays estimates that it may reach 135 billion US dollars in the next 24 to 48 hours.
This round of collapse in technology stocks that has swept the world seems to show an increasingly clear reversal chain: investors are concerned about the accelerated penetration of energy inflation and the blocking of AI computing power infrastructure expansion after the Democratic Party took control of the US Senate and House of Representatives. The price breakdown triggered large-scale capital cuts in “fast money” type quantitative strategies such as CTAs and volatility strategies. Active capital also traded these predictable sales prices in the global stock market in advance.
Volatility target strategies and trend-tracking CTAs to reduce positions after the price falls below the signal threshold are mechanical sales orders in fast money; active traders sell early and then bet on buying back at a lower price, which is a “rush” against mechanical sales.
The key to the recent sharp decline logic of “predicting your predictions” is that active traders will trade these estimable rebalancing requirements in advance: sell or open short positions first, and wait to buy back after the machine is sold off. When buying is delayed, the rush action further depresses the price, triggering more trend signals and risk control to reduce positions; however, if the price stabilizes, previously established bears may also strengthen their rebound through compensation.
Strong Feinong can provide a basis for economic resilience for active buying, but it won't immediately change all systemic strategy instructions: trend tracking CTAs focus on price trends, volatility control funds focus on achieved volatility, and leveraged ETFs reset exposure based on the rise and fall of the day. Therefore, even if the index rises and VIX falls, some volatility-controlled funds may continue to reduce their positions; at the same time, the rebalance of leveraged ETFs on the same day may shift to buying.
Currently, it is more in line with market trends and the predictive view of global institutional investors investing in real money trading — “economic resilience supports technological recovery, interest rate hikes and revaluation limits room for rebound, and active buying clashes with lagging machinery sales at the same time.”
In other words, the market does not need to wait until all mechanical sales are exhausted to begin to rebound, and the price increase itself may gradually reduce some of the deleveraging pressure. If bond trading on dips limits yield increases, corporate profit expectations remain stable, and stocks stabilize and gradually reduce the volatility achieved, strong employment is more likely to be transformed into a foundation for continuous recovery; if interest rate expectations rise further and AI orders and project returns are lowered at the same time, profit support may not be enough to cover the contraction in valuation. What really determines the next phase of the market is whether additional profit support can offset the rise in capital costs, and whether the market's carrying capacity can absorb the demand for position reduction that is still being implemented.
Although the Nasdaq 100 index recorded its worst decline since March 2020 on Thursday, Wall Street's overall attitude has not changed and is still bullish for a long time. Deutsche Bank is once again bullish on US technology stocks, believing that recent adjustments have been excessive, valuations and positions have cooled down, while profit growth is still resilient; Mike Wilson, chief US stock strategist at Morgan Stanley, believes that this round of adjustments is nearing its end, focusing on high-quality companies whose valuations have declined and profits are highly sustainable. The opportunity they both point to is a rematch between adjusted prices and the quality of long-term business growth, rather than a simultaneous rebound in all AI assets.
Pershing Plaza, where Ackman is at the helm, further pointed out in the latest shareholder letter that the market may prolong huge AI capital expenses, but the subsequent revenue acceleration brought about by these investments is not fully taken into account; customer relationships, data, distribution channels, and commercialization capabilities of large technology companies make it easier to transform additional computing power into fee-based services. Ackman's latest judgment was supported by strong AI-related cloud computing business growth: Amazon's AWS revenue increased 39.3% in the third quarter, and Alphabet's Google Cloud revenue increased 103%. The latter included significant TPU system sales contributions. The popularity of Meta bonds adds a part of financing to this bullish logic: when revenue growth, availability of financing, and return on investment are gradually linked, high-quality platforms have the foundation to move from valuation compression to revaluation.