


EN
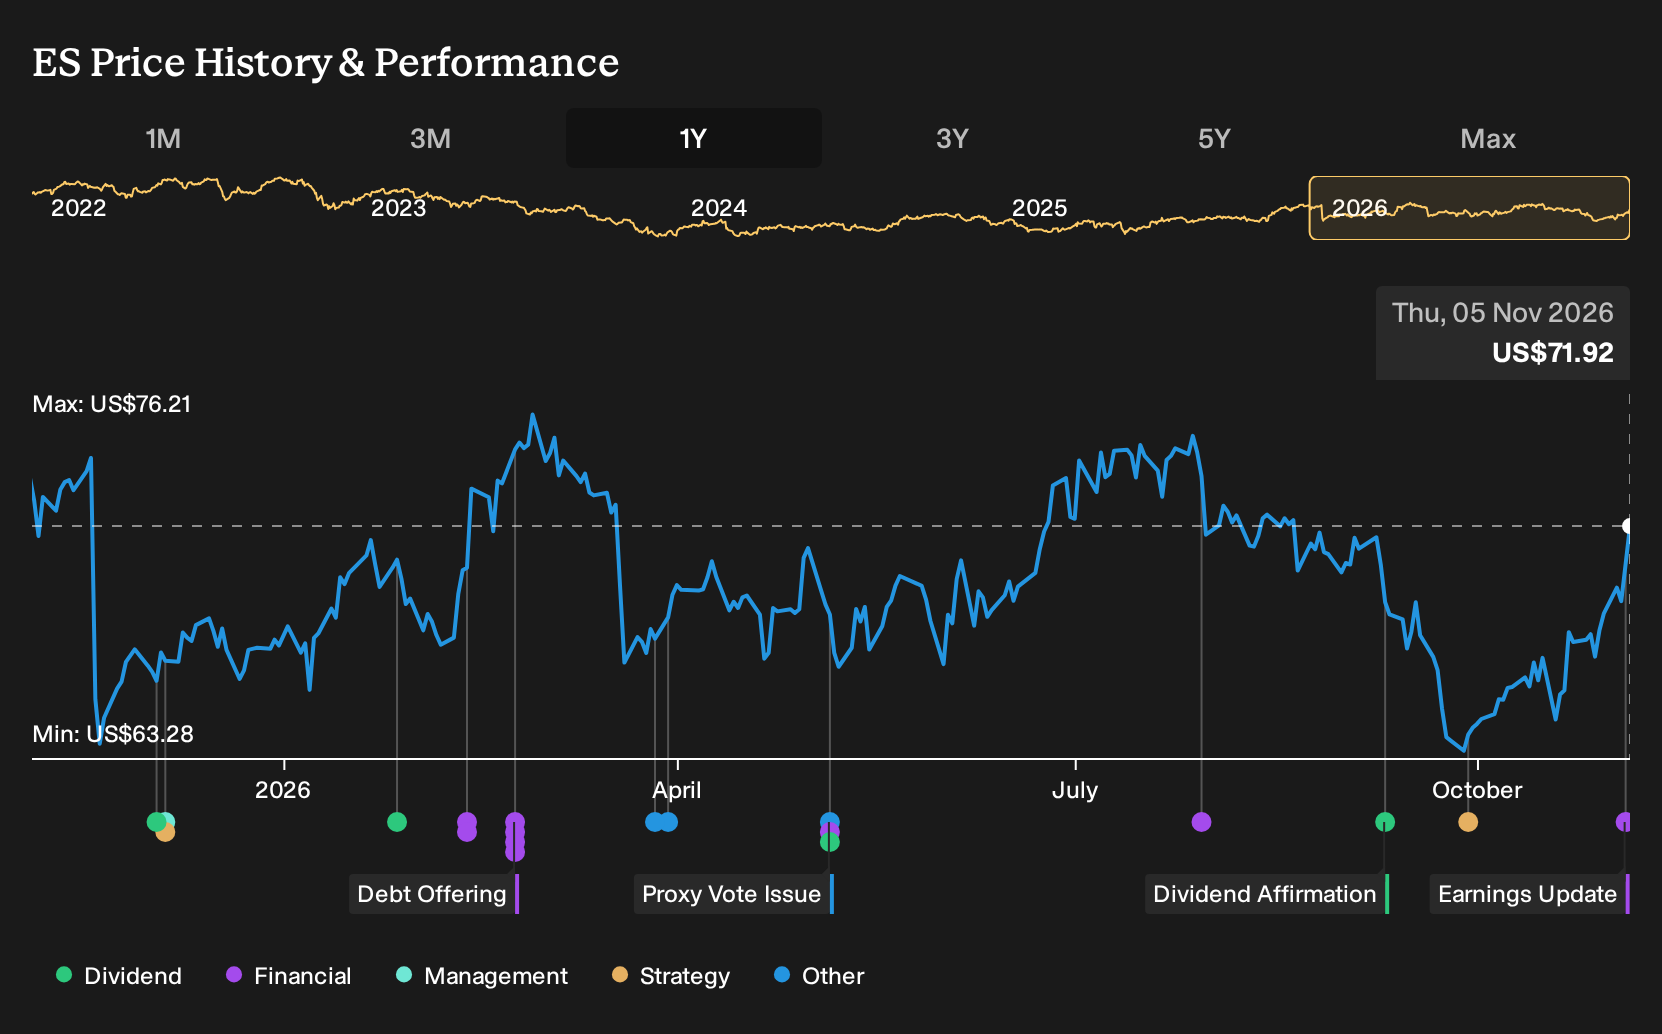
How Investors Are Reacting To Eversource Energy Stock After Earnings Miss
- Eversource Energy reported third quarter 2026 earnings below Wall Street expectations, with US$2.98b in sales and US$0.92 in diluted EPS from continuing operations, alongside a tighter full year earnings range.
- Behind the headline miss, the utility is dealing with softer quarterly revenue, lower year to date net income, and a less favorable near term earnings outlook that raises questions about cost recovery timing and project execution.
- The next focus is how this weaker quarter and subdued guidance influence Eversource Energy’s broader investment narrative around regulated growth.
Pressure test Eversource Energy against a curated peer set by scanning our 40 power grid technology and infrastructure stocks, which includes companies that are also wrestling with grid investment needs and regulatory scrutiny after earnings surprises.
Eversource Energy Investment Narrative Recap
For an investor to stay in Eversource Energy, the core belief is that its regulated utility model and multi year capital program can still turn rising electrification and grid modernization needs into a growing regulated rate base. The latest quarter, with EPS from continuing operations of US$0.92, softens that story in the near term but does not change the long run structure of the business.
The more immediate swing factor is how regulators handle cost recovery for that US$26.5b capital plan and recent storm spending. Weaker year to date net income and tighter guidance keep pressure on the 2026 CL&P outcome and other filings. The biggest risk right now remains tougher rate decisions or delayed cost recovery that compress earnings against rising interest costs.
The most relevant update for this news is management’s reaffirmation of its long term earnings growth framework through 2030, alongside an updated 2026 non GAAP recurring earnings range. That reinforces that Eversource Energy is still leaning on regulated capital spending, including projects such as Revolution Wind and advanced metering, as the key driver for future returns on its asset base.
For investors, the connection is straightforward. The recent earnings miss and tighter full year outlook put more weight on execution in that capital plan and on regulatory decisions in Connecticut, Massachusetts, and New Hampshire. Any shift in timing or allowed returns on projects, including storm cost securitizations and the CL&P rate case, can quickly change the near term risk reward balance around those longer term catalysts.
Eversource Energy's current earnings sit at US$1.4b, with analysts expecting earnings of US$2.1b by 2029. This implies an increase of roughly US$700m, while revenue is projected to reach US$15.4b by that same year on an assumed 3.3% yearly top line growth rate.
Uncover why Eversource Energy's fair value indicates performance that is roughly in line with its current price.
Exploring Other Perspectives
The sharpest contrast today is regulatory risk. Before this earnings miss, the most bearish analysts were already bracing for tighter oversight, building forecasts around revenue of about US$14.8b and earnings of roughly US$2.1b by 2029 on a 12.0x P/E. You can see how this weaker quarter could push those already cautious views even further.
Explore 2 other Eversource Energy fair value estimates, including one that suggests as much as 15% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Eversource Energy research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Eversource Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eversource Energy's overall financial health at a glance.
Looking for more investment ideas beyond Eversource Energy?
If this quarter has you reassessing Eversource Energy, use that same curiosity to broaden your watchlist with other stocks that fit different risk and income profiles.
- If capital preservation sits high on your priority list, take a look at a 32 resilient stocks with low risk scores to see which companies currently score well on resilience and balance sheet strength.
- If reliable cash payouts matter more to you than short term price moves, focus on income opportunities through a 6 dividend fortresses that highlights higher yielding payers.
- If you prefer to hunt for underappreciated quality, broaden your opportunity set with a 21 high quality undiscovered gems that surfaces fundamentally solid businesses flying under most investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com