


EN
TD SYNNEX (SNX) Stock Could Be A Bargain Despite Its 140% Run
TD SYNNEX has seen its share price surge over the past few years, yet the stock has recently pulled back even as headlines highlight new partnerships and industry awards. With the shares last closing at US$215.37, the key issue for you as an investor is whether that price is still grounded in the earnings the company produces.
- Over the past 3 years TD SYNNEX has delivered a 140.1% share price gain, which puts real pressure on the question of how much of its earnings power is already reflected in the stock.
- Recent moves into areas like cybersecurity and AI services, including new partnerships and expanded frameworks, can shape how quickly earnings might grow and how resilient those profits could be across different technology cycles.
- The analysts covering TD SYNNEX have run their own numbers. See what analysts think TD SYNNEX's shares could be worth.
The issue now is whether TD SYNNEX's current valuation can be explained by its earnings profile when stacked against the Fair Ratio benchmark.
If you want more ideas with a similar earnings focus to TD SYNNEX, a good next step is to run a focused stock screen using 42 high quality undervalued stocks.
Is TD SYNNEX Still Cheap on Earnings?
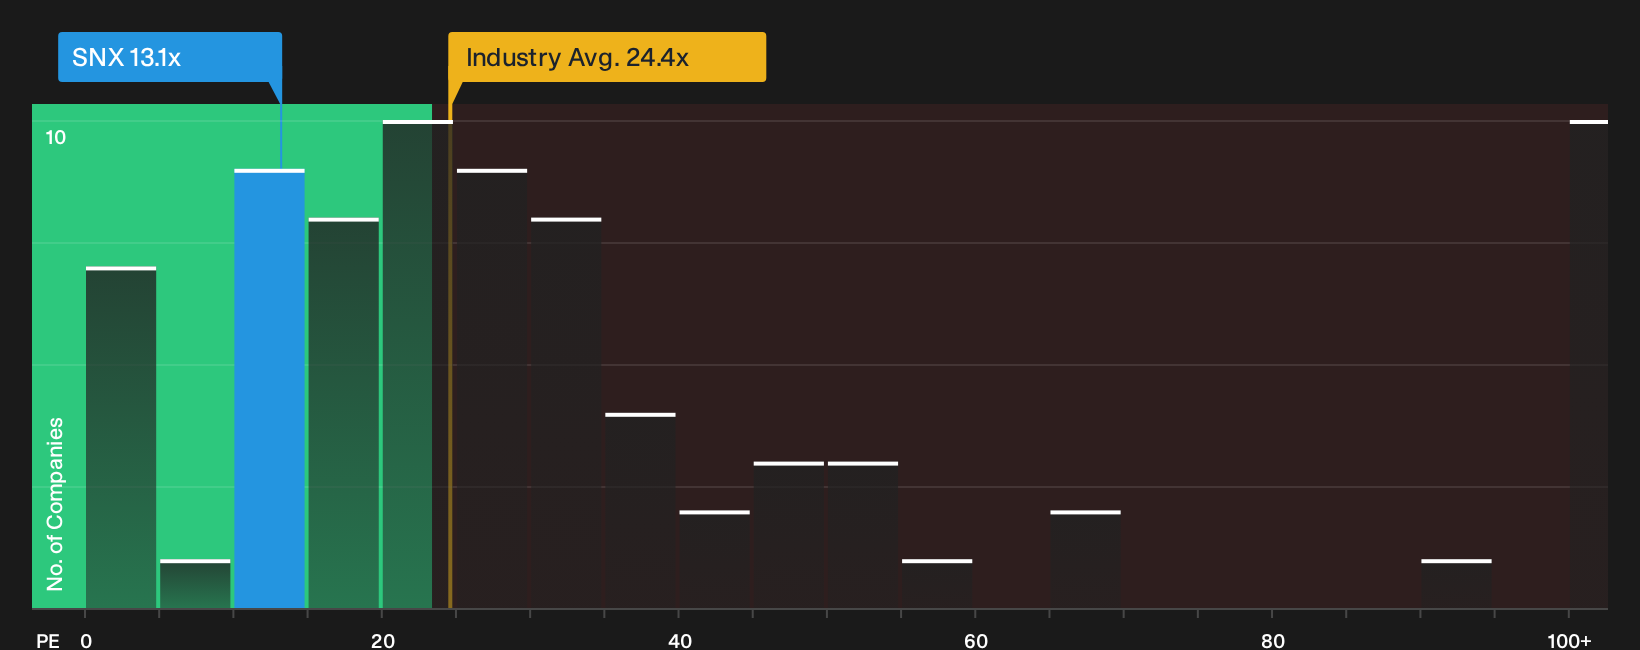
The P/E ratio suits TD SYNNEX because earnings remain the key yardstick most investors use for large distributors tied to broad tech spending. On this measure, the stock trades on a P/E of about 13.1x, which is almost identical to the peer average of roughly 13.1x and sits well below the wider Electronic industry on about 24.4x. This indicates that the market is applying a similar earnings multiple to close peers, even though the broader sector is priced higher relative to reported profits.
The Fair Ratio, which blends TD SYNNEX's growth profile, margins, risk and scale into a tailored benchmark, points to a higher P/E than the one currently on the screen, so the shares screen as undervalued on this framework. Despite recent headlines around expanded AI and cybersecurity offerings, the stock trades at a sizeable discount to the sector's richer earnings multiples. Explore the numbers behind TD SYNNEX's P/E valuation.
The TD SYNNEX Narrative: What Would Justify Today's Price?
Narratives on TD SYNNEX pick up where the valuation puzzle leaves off and describe what kind of future earnings path, margin profile and business mix would need to hold for the stock to be worth materially more or materially less than today's price. Each scenario connects a specific fair value estimate to a clear storyline about TD SYNNEX's potential catalysts and key risks so you can track over time which version seems closer to reality on Simply Wall St's Community page.
One of the top community narratives on TD SYNNEX: 37% undervalued
"The main factor that has to go right is Hyve converting its very rapid hyperscaler and AI server billings growth into healthier cash generation..."
Discover why this Narrative puts TD SYNNEX at 37% undervalued.
The TD SYNNEX price is only one piece of the decision
Valuation checks on TD SYNNEX tell only part of the story, because the research also flags specific risk signals that investors may want to weigh before going further. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com