


EN
Are Wall Street Analysts Predicting Airbnb Stock Will Climb or Sink?
San Francisco, California-based Airbnb, Inc. (ABNB) operates a platform for stays, experiences, and services worldwide. Valued at a market cap of $101.9 billion and hosts a marketplace that connects hosts and guests online or through mobile devices to book spaces, experiences, and services.
ABNB shares have rallied the broader market over the past year, surging 38.9% versus the S&P 500 Index’s ($SPX) 8.2% surge. Moreover, in 2026, the stock has grown by nearly 25.4%, outperforming the SPX’s 7.4% rise.
Focusing on its industry benchmark, the State Street Consumer Discretionary Select Sector SPDR ETF (XLY) has fallen 2.4% over the past year, underperforming the stock. In 2026, XLY has declined 1.5% and has also lagged behind the stock.
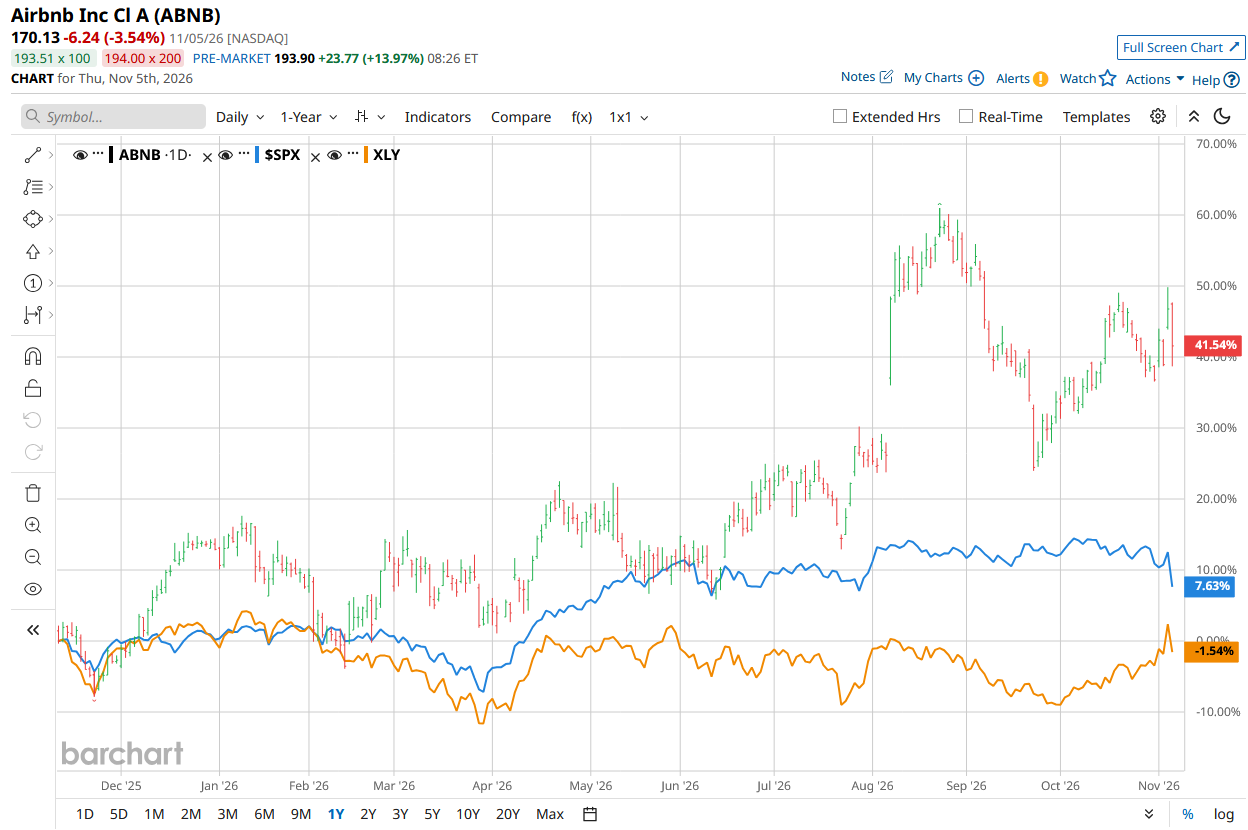
ABNB announced its better-than-expected Q3 2026 earnings in the last trading session. The company’s revenue for the period rose 18.9% from the prior year’s quarter and amounted to $4.9 billion, surpassing the Street’s forecasts. Moreover, its adjusted EPS came in at $3.16, also topping consensus estimates. ABNB also raised its full-year revenue growth and EBITDA margin guidance, ensuring operational excellence.
For the current year, which ends in December, analysts expect ABNB’s EPS to rise 31.3% to $5.29 on a diluted basis. The company surpassed the consensus estimate in two of the last four quarters, while missing on two other occasions.
Among the 40 analysts covering ABNB stock, the consensus is a “Moderate Buy.” That’s based on 20 “Strong Buy” ratings, four “Moderate Buys,” 14 “Holds,” one “Moderate Sell,” and one “Strong Sell.”
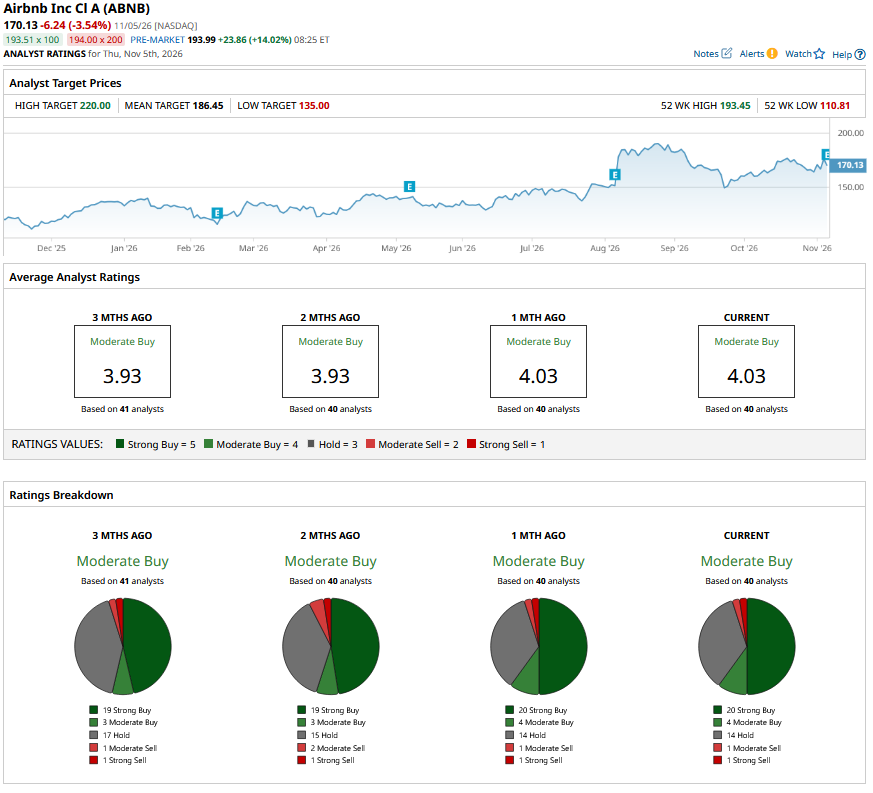
The configuration has grown more bullish, with the stock now having 20 Strong Buy ratings, compared to 19 two months ago.
On Oct. 27, Oppenheimer analyst Jed Kelly maintained a “Buy” rating for ABNB stock and raised its price target from $190 to $210.
ABNB’s mean price target of $186.45 offers a 9.6% upside compared to the current market price. Its Street-high target of $220 implies a robust 29.3% upside from current levels.
On the date of publication, Aritra Gangopadhyay did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.