


EN
Netflix (NFLX) Stock May Be 23% Below Fair Value As Ads Expansion Builds
Netflix has seen its share price fall sharply over the past year even after a strong three year run. This puts a spotlight on a simple question for investors: Is the current market value of the streaming giant adequately backed by the cash flows the business can be expected to produce over time?
- Netflix has returned 50.7% over the past 3 years, which makes it important to test whether that gain still lines up with what its cash flows can justify.
- Expansion of the ads business, including new leadership for the ads platform and plans to roll out ad tiers to more countries in 2027, can affect how quickly subscription and advertising cash flows grow and how predictable they become.
- What if you looked at Netflix through its earnings instead? See what Netflix's 18.2x P/E says about the price.
The stock's next move may depend on whether Netflix's current share price is well supported by its cash flows when viewed through a Discounted Cash Flow (DCF) lens.
If you are questioning whether Netflix's price still lines up with its cash flows, it can help to compare that same cash flow test across 42 high quality undervalued stocks.
Does Netflix Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) approach values Netflix by projecting its future cash generation and discounting it back to today. On this model, the business is built on meaningful cash production already, with latest twelve month free cash flow at about $11.6b, and analyst forecasts pointing to higher annual free cash flow by 2030 in dollar terms.
Growth baked into the projections looks steady rather than explosive, with free cash flow expected to rise over time but not at eye catching rates. That level of cash support, when set against today’s share price of $65.56, leads this DCF estimate to sit meaningfully above where the stock trades. The recent slide after concerns around viewership and engagement helps explain why the price stays below what the cash flows in this model would support. Find out what Netflix could be worth using our Discounted Cash Flow (DCF) estimate.
The Netflix Narrative: What Would Justify Today's Price?
Narratives pick up where that valuation puzzle leaves off. They outline the specific paths for Netflix's growth, margins, and earnings that would need to occur for the stock to end up worth substantially more or less than it is today. These narratives appear on Simply Wall St's Community page so you can see the future story that any single ratio or model number assumes, and then judge over time whether Netflix's real-world progress still aligns with it.
Community views on Netflix now hinge less on business quality and more on how much cash flow improvement is already priced in.
Bull case: 20% undervalued
"The bull case increasingly leans on pricing, advertising, margin expansion and buybacks rather than pure subscriber momentum..."
Discover why this Narrative puts Netflix at 20% undervalued.
Bear case: 13% overvalued
"We look to sustain double-digit revenue growth, we look to expand margins, and we look to increase free cash flow..."
Explore why this Narrative puts Netflix at 13% overvalued.
One more factor to weigh before acting on Netflix's valuation story
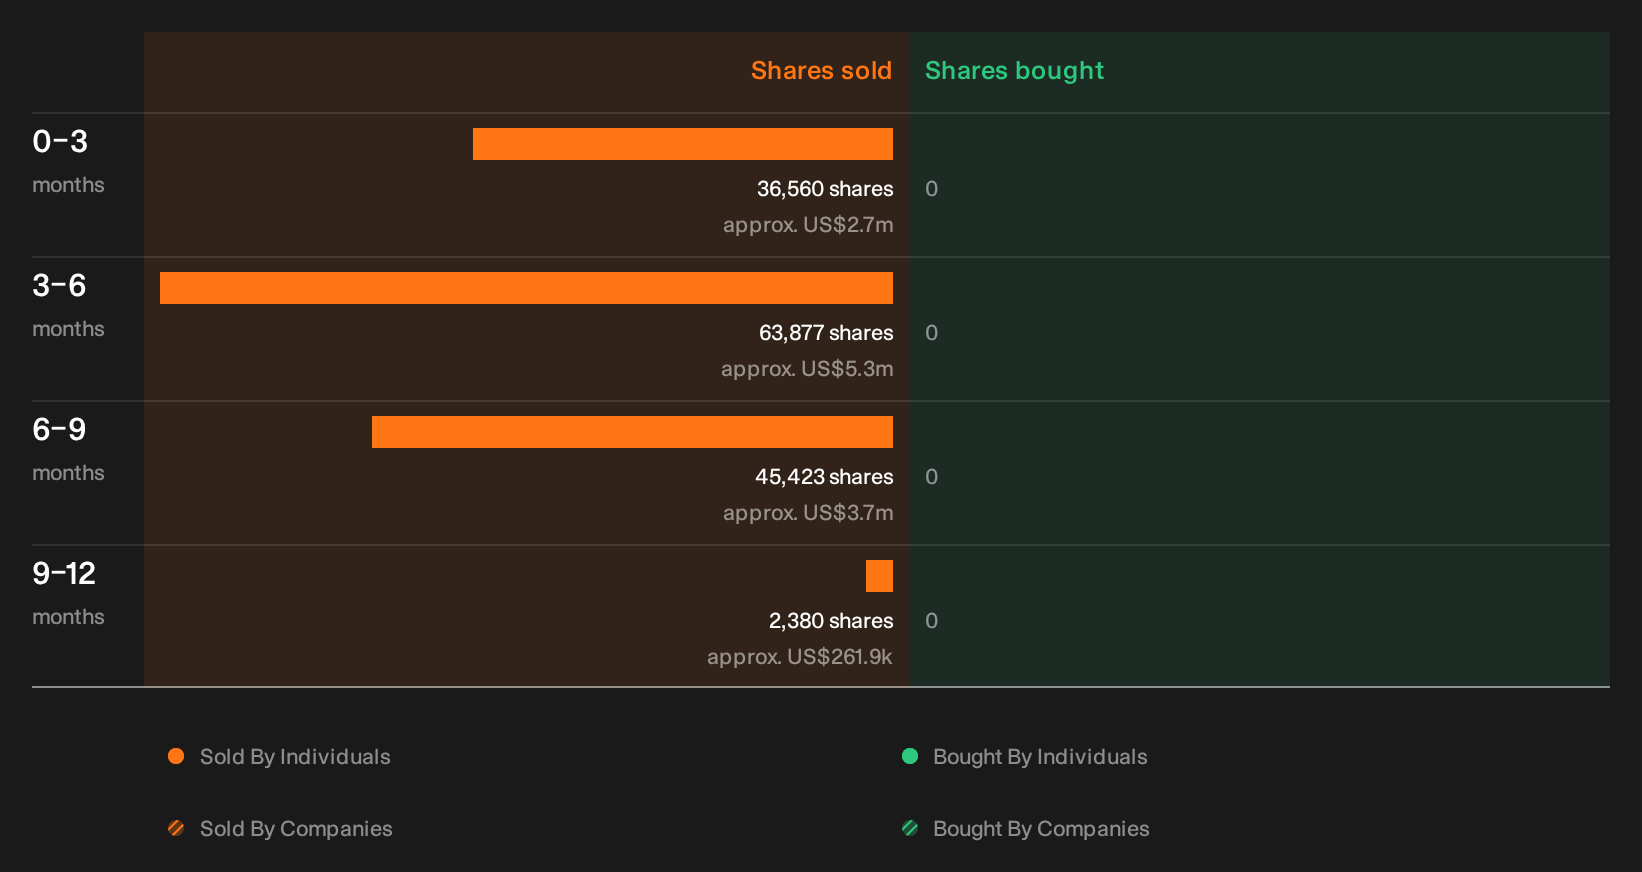
Before making any move on Netflix, it is worth checking what recent insider share sales might signal. Who sold, how much, and why can sharpen your view of risk and conviction. See the recent insider selling flagged for Netflix.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com