


EN
Earnings Beat Change The Bull Case For Federated Hermes (FHI)
- Federated Hermes reported third quarter 2026 revenue of US$507.33 million and net income of US$111.89 million, with basic and diluted earnings per share from continuing operations of US$1.50. The company also declared a US$0.38 dividend payable on November 13, 2026 to shareholders of record on November 6.
- The combination of higher quarterly earnings per share and continued cash returns through the affirmed dividend highlights how Federated Hermes is currently balancing profitability with shareholder payouts as it manages its fee based investment management platform.
- This article will examine how Federated Hermes' investment narrative is influenced by the higher third quarter earnings per share it has just reported.
Scan how Federated Hermes' latest earnings and dividend fit alongside peers by reviewing a curated set of income focused opportunities in 6 dividend fortresses
Federated Hermes Investment Narrative Recap
To own Federated Hermes, you need to be comfortable with a fee based asset manager that still leans heavily on money market products while trying to grow higher fee equity and private markets strategies. The recent quarterly revenue of US$507.33 million and net income of US$111.89 million support the idea that the core franchise is currently holding up.
The near term opportunity remains execution on expanding quantitative equity, ETFs and alternatives so that they offset any softness in money market flows or fee pressure. Key risks stay the same. Persistent industry fee compression, possible volatility in money market assets and higher operating costs could limit how much these reported earnings help.
The most relevant update for that story is the third quarter 2026 earnings release. Federated Hermes reported US$507.33 million of revenue and US$1.50 in basic and diluted earnings per share from continuing operations, with nine month revenue of US$1,489.06 million and net income of US$312.58 million.
This reporting period matters because it shows how the business is converting its broader product buildout into current profits while still carrying the cost of acquisitions and expansion. For an investor, a key point to watch is whether future results continue to support investment in quantitative equity, private markets and digital money market initiatives without eroding margins.
What Federated Hermes' Analyst Assumptions Are Telling You
Analysts are effectively sketching out a slow and steady path for Federated Hermes rather than a dramatic overhaul. Their models point to revenue expanding by 3.4% a year over the next three years, with profit margins edging from 20.3% today to 19.8% by 2029. That combination assumes modest top line progress while accepting a little squeeze on profitability.
On earnings, the consensus view is that profit could reach US$424.0 million, or US$6.78 per share, by around 2029 compared with US$393.2 million today. That is an increase of US$30.8 million in absolute profit. The forecast also incorporates a shrinking share count, with analysts expecting outstanding shares to fall by about 3.69% a year for the next three years. That would amplify earnings per share even if total profit only edges higher.
Valuation assumptions sit on top of these earnings and revenue building blocks. The analyst framework uses a discount rate just above 8% and assumes Federated Hermes could trade on a P/E of 11.5x those 2029 earnings. That multiple is lower than the current P/E quoted for the broader US Capital Markets industry at 39.7x, which points to expectations that are focused more on cash generation than on high growth.
Those inputs come together in a consensus price target of US$61.0 per share, compared with a recent price of US$56.5 as of October 2026. The implied 7.4% gap is relatively small, which suggests that the current share price already reflects much of the analyst scenario on revenue, earnings, margins and capital returns.
Federated Hermes' analyst framework points to forecast revenue of US$2.1b and earnings of US$424.0 million by 2029, supported by assumed yearly revenue expansion of 3.4% and an earnings increase of US$30.8 million from current earnings of US$393.2 million.
Uncover why Federated Hermes' fair value indicates a 5% potential downside to its current price, leaving little room for error.
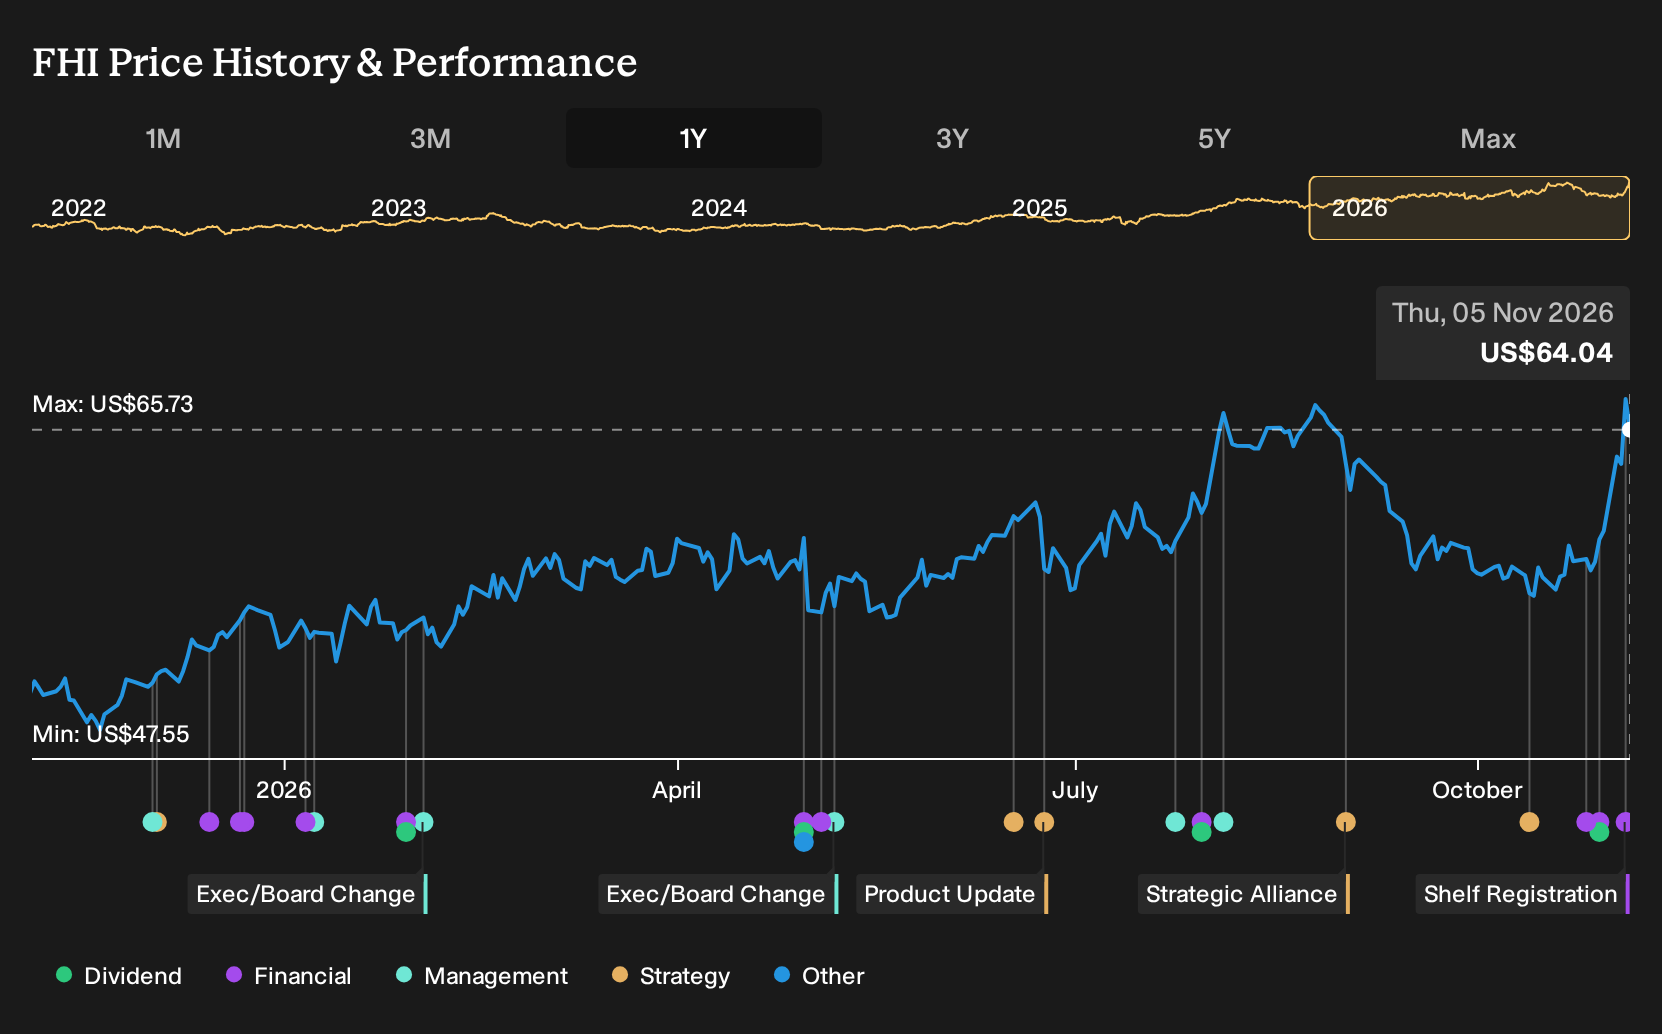
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between US$61 and about US$70 per share, with one investor at the low end and another pushing toward the upper bucket. That gap, formed before the latest Federated Hermes earnings and dividend affirmation, sits against fee compression and money market concentration risks that you should weigh carefully.
Explore another Federated Hermes fair value estimate, including one that suggests it could be worth just $61.00.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Federated Hermes research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Federated Hermes. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Federated Hermes' overall financial health at a glance.
Looking for more investment ideas beyond Federated Hermes?
If the Federated Hermes story has sharpened your thinking about income, risk and valuation, it can be useful to compare it with a wider set of listed businesses. The Simply Wall St Screener helps you move from one stock to a short list of candidates that match the kind of balance sheet strength, dividend profile or valuation setup you want to focus on next.
- If capital preservation matters to you, start with companies that pair resilient operations with measured risk profiles through the 32 resilient stocks with low risk scores.
- For investors who like to be early, scan financially sound smaller players that are less widely followed using the 21 high quality undiscovered gems.
- If dependable income is a priority, compare Federated Hermes with other high yield payouts by reviewing a curated 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com