


EN
Earnings Outlook Raised Might Change The Case For Investing In Nokian Tyres Stock
- Nokian Renkaat Oyj reported third quarter 2026 sales of €359.1 million and net income of €23 million, with nine month earnings turning from a prior loss to a profit and earnings per share from continuing operations at €0.17 for the quarter.
- The raised 2026 outlook, with net sales expected to grow versus last year and segment operating margin guided toward the top of the 9% to 10% range, highlights how recent cost measures and product mix choices are feeding through to profitability.
- The focus now is on how Nokian Renkaat Oyj's stronger quarterly profit and higher margin guidance could reshape its longer term investment narrative.
Scan how Nokian Renkaat Oyj's earnings reset compares with other profit-focused opportunities by reviewing the hand picked 229 high quality undervalued stocks, which pair resilient cash flows with disciplined balance sheets.
Nokian Renkaat Oyj Investment Narrative Recap
Nokian Renkaat Oyj appeals to shareholders who support a recovery story built on higher value tyres, tighter cost control and more disciplined capital spending. The near term focus is whether recent margin gains can hold as the product mix shifts further toward premium winter, all season and 18 inch plus tyres.
The biggest swing factor remains execution on that mix and efficiency plan in markets that have recently seen softer volumes. The key near term risk is that end demand in Central Europe and North America stays weak, which would pressure factory utilisation and make the margin targets harder to reach.
The raised 2026 guidance is the most relevant development. Management now expects full year net sales to grow compared with last year and segment operating profit margin to be at the higher end of the 9% to 10% range. This sits alongside the company-wide ambition to reach €1.8 billion to €2 billion of net sales by 2029.
This updated outlook links directly to the earnings catalyst investors are monitoring, which is evidence that the €220 million segment EBITDA uplift plan is progressing on schedule. It also aligns with the main concern that interest payments are not yet comfortably covered by earnings, so stronger and more consistent profitability remains important to the longer term equity narrative.
Nokian Renkaat Oyj Analyst Expectations In Context
Analyst models paint a very different earnings profile for Nokian Renkaat Oyj compared with the recent past. The consensus view ties the recovery story to a mix of steady top line expansion, firmer margins and a less stretched valuation multiple as earnings scale.
Assumptions in those models are straightforward on paper. Revenue is projected to expand by 7.5% a year over the next three years, while profit margins are expected to move from 1.4% today to 8.5% in that same window. That margin lift is a big part of why earnings forecasts step up so sharply into the back half of the decade.
Earnings today are put at €19.5 million. The same analyst set expects net profit to reach €150.8 million by around 2029, with some forecasters pencilling in as much as €218.1 million. That is roughly a 7.7x increase from the current level at the consensus point estimate, which gives a sense of how much of the story is tied to execution on margin and volume.
Those profit assumptions feed directly into the valuation bridge. On the numbers provided, analysts are using a P/E of 113.8x on current earnings, stepping down to 15.5x on the 2029 forecast, which is below the 71.2x quoted for the wider GB Auto Components industry. The discount rates referenced, at 8.38% and 8.4%, sit in the background of the models and influence how that future profit stream is translated into a present value.
Consensus also anchors to a revenue target. To line up with the forecasts, you would need to assume Nokian Renkaat Oyj reaches €1.8b of net sales and the €150.8 million profit level by 2029. Analysts suggest the share count stays broadly flat across this period, so the heavy lifting in their estimates is done by sales growth, firmer margins and a more conventional earnings multiple rather than financial engineering.
The current share price of €16.09 sits above the analyst average target of €13.33, which is 20.7% lower. That gap indicates a view that the market already discounts a lot of the improvement story and possibly more. For investors tracking this, the practical question is whether their own expectations for revenue progression, margin delivery and balance sheet resilience line up more with the present price or the analyst fair value range of €10.0 to €16.5.
Nokian Renkaat Oyj's narrative projects €1.8b revenue and €150.8 million earnings by 2029. This is based on 7.5% yearly revenue growth and roughly a 7.7x earnings increase from €19.5 million today.
Uncover why Nokian Renkaat Oyj's fair value indicates a 5% potential downside to its current price, suggesting a premium that may not be sustainable.
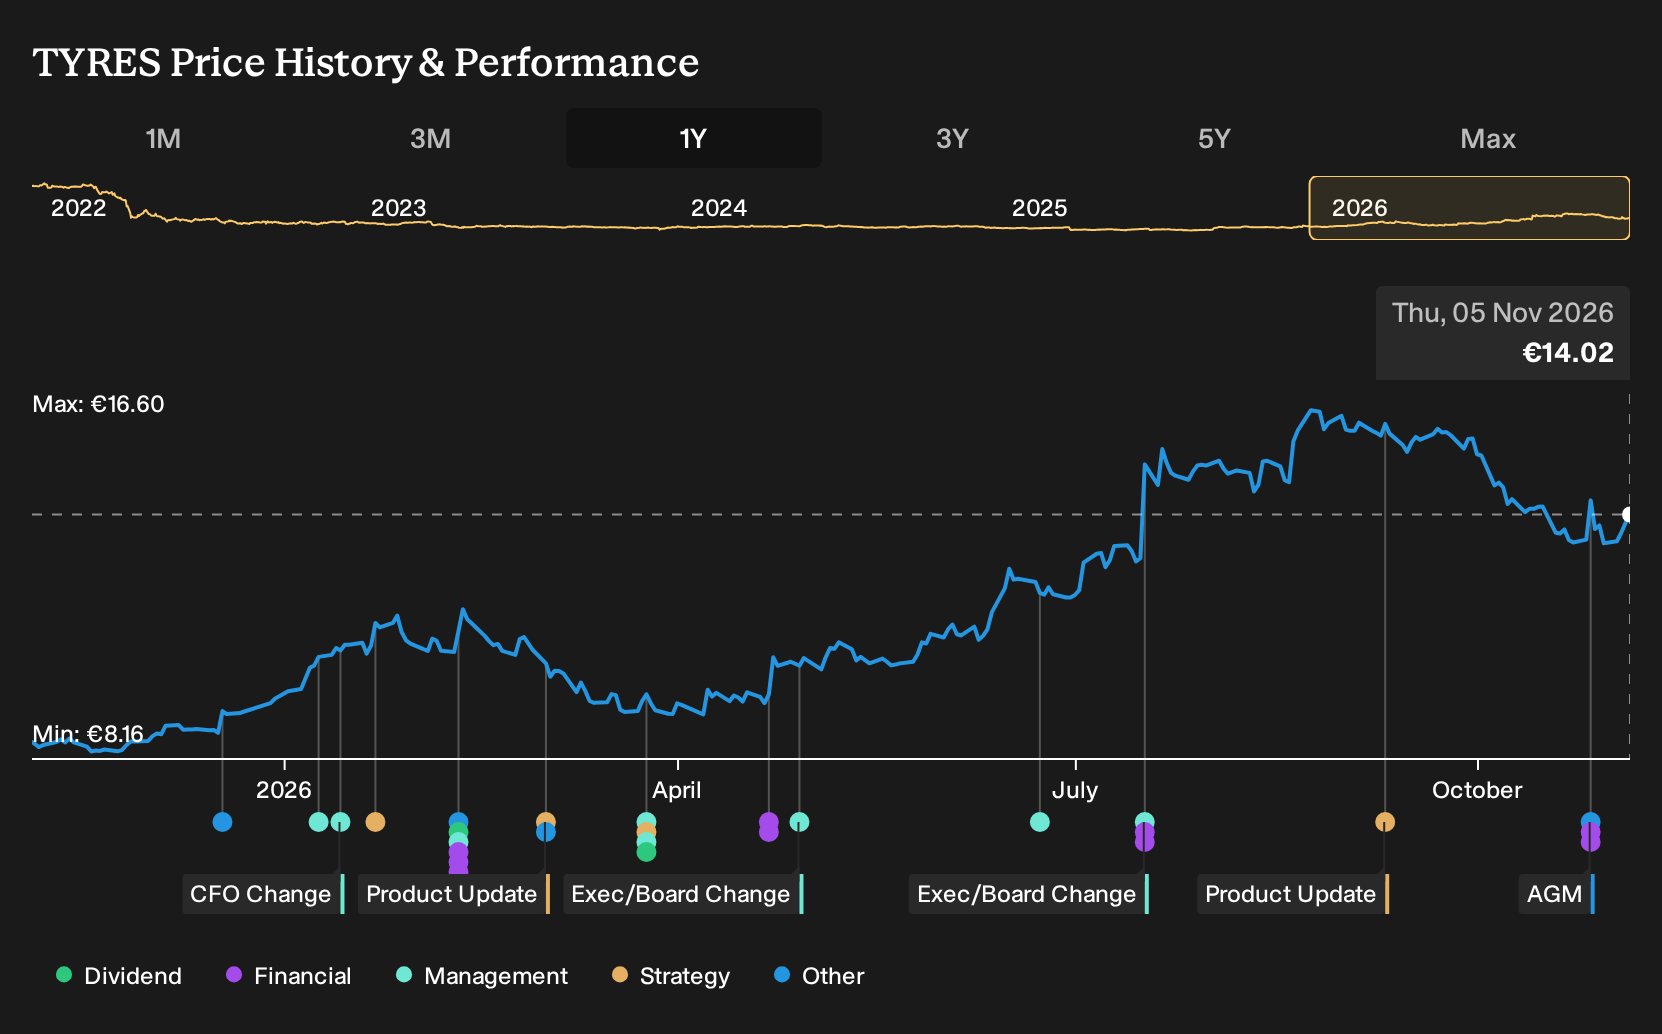
Exploring Other Perspectives
One alternate view on Nokian Renkaat Oyj leans hard into mix and pricing power as the real catalyst. The most optimistic analysts were already working with revenue reaching about €1.9b and earnings of €231.1 million by 2029, compared with €36.8 million before this earnings beat. Those figures did not factor in the latest margin guidance. You can treat this quarter as a fresh data point and compare how your own expectations stack up against both the cautious and the more optimistic scenarios.
Explore 2 other Nokian Renkaat Oyj fair value estimates, including one that suggests as much as 17% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Nokian Renkaat Oyj research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nokian Renkaat Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nokian Renkaat Oyj's overall financial health at a glance.
Looking For More Investment Ideas Beyond Nokian Renkaat Oyj?
Once you have a view on Nokian Renkaat Oyj, it can help to widen the lens and compare it with other listed businesses that share similar traits, whether that is value, resilience or income potential. The Simply Wall St Screener offers several focused sets of stocks that can help you pressure test your thesis and spot alternatives that better fit your risk and return preferences.
- If you want companies where pricing looks appealing relative to quality, compare Nokian Renkaat Oyj with a curated 229 high quality undervalued stocks that pairs solid fundamentals with more modest market expectations.
- For readers who care most about balance sheet strength and durability through different cycles, review the list of solid balance sheet and fundamentals (192 results) to see businesses with cleaner finances and stronger cushions against shocks.
- If you are hunting for less crowded opportunities, use the 591 high quality undiscovered gems to find under-the-radar stocks that combine firm fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com