


EN
Did Half Year Losses Just Shift LIXIL's (TSE:5938) Investment Narrative?
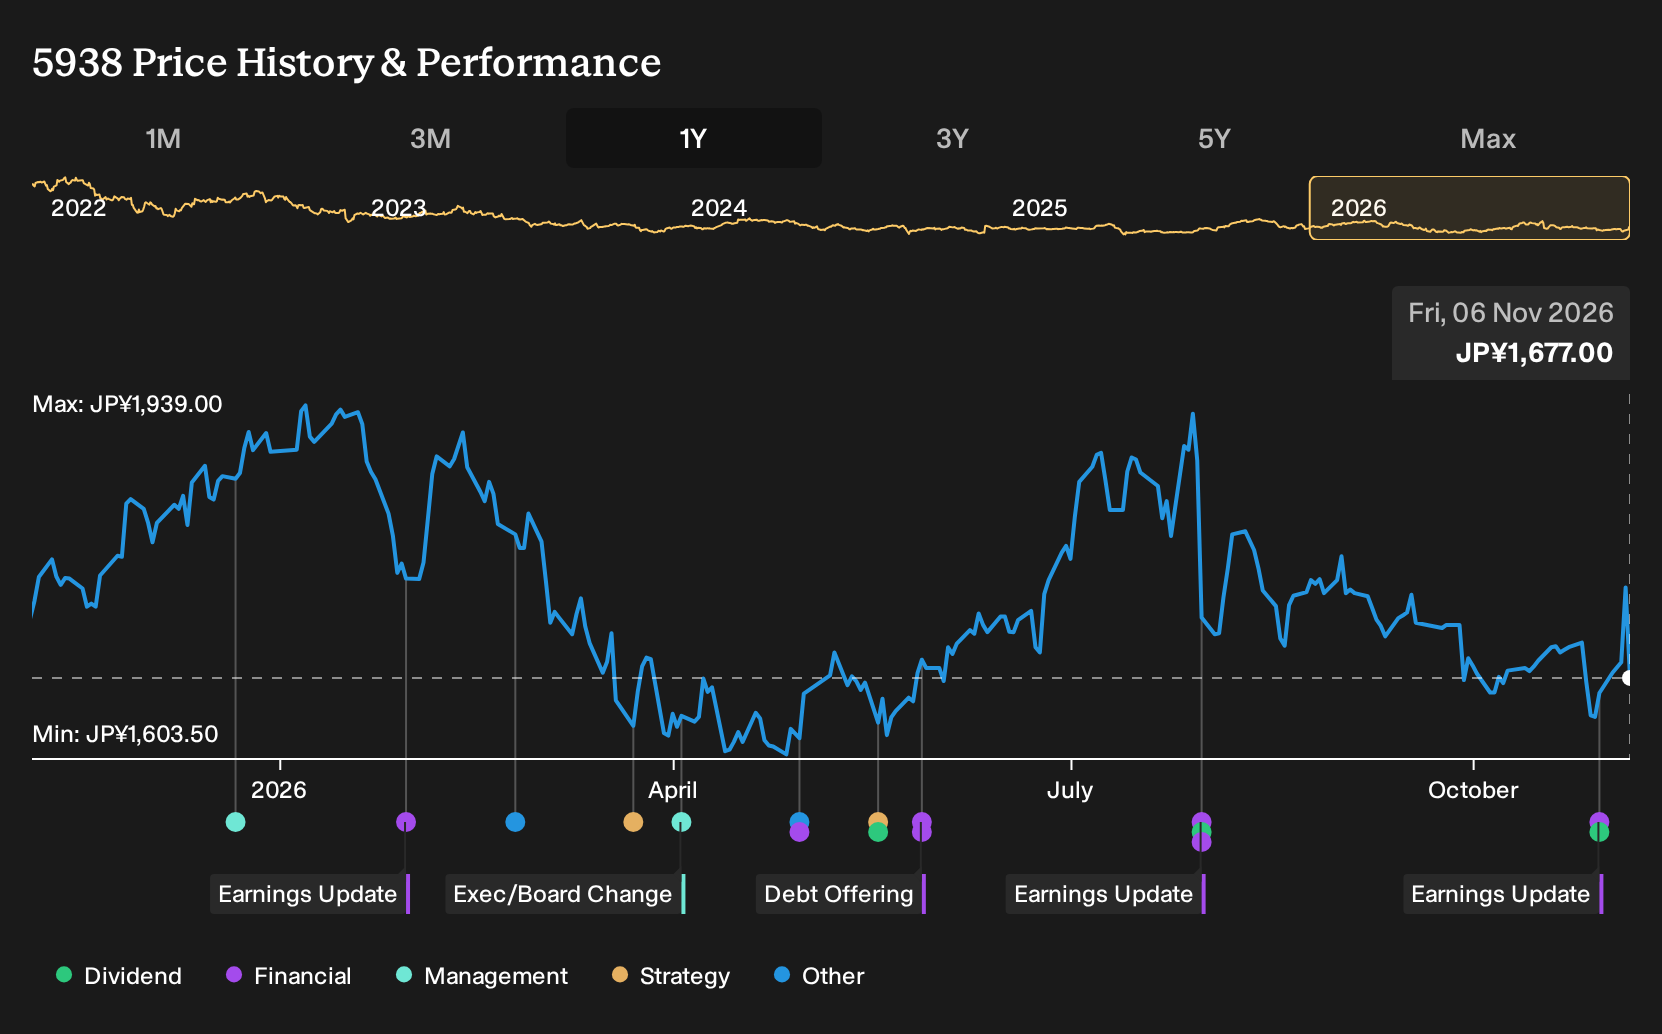
- LIXIL Corporation reported half year sales of JPY 762,461 million to September 30, 2026, alongside a shift from net income to a net loss and a basic loss per share of JPY 15.96.
- The board kept the second quarter dividend at JPY 45.00 per share, matching last year, which indicates management’s decision to maintain cash returns despite the loss.
- Investors may now assess how LIXIL’s investment narrative holds up in light of the loss-making half year and the unchanged dividend.
LIXIL Investment Narrative Recap
To own LIXIL, an investor needs to believe the renovation and premium product tilt can offset pressure in slower or loss making regions and support margins over time. The latest half year numbers show that even with sales of ¥762,461m, losses can appear quickly when costs or mix move in the wrong direction.
The most important short term swing factor remains execution on cost control and pricing so material and logistics volatility does not repeatedly drag earnings into the red. The biggest risk is that structurally weaker markets, such as U.S. housing and a soft domestic construction backdrop, keep profitability thin. This set of results reinforces that risk rather than changing it.
The dividend affirmation for the second quarter at ¥45.00 per share, payable on 30 November 2026, is the announcement that really matters here. It directly intersects with the loss making half year and the existing concern that interest costs and the payout are not well covered by earnings or free cash flow.
For readers, that dividend decision focuses attention on cash generation and balance sheet resilience as key near term catalysts. Any evidence that LIXIL can support this level of payout while lifting core earnings through renovation, premium products and overseas mix improvement would be important. If cash generation lags, dividend sustainability risk stays front and centre.
LIXIL's analyst narrative is based on forecast revenue of ¥1,635.5b and projected earnings of ¥29.9b by 2029, built on assumed 2.4% yearly revenue growth and an earnings increase of ¥24.4b from current earnings of ¥5.5b.
Uncover why LIXIL's fair value indicates a 12% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some bearish analysts focus on dividend risk rather than renovation upside. Before this loss making half year and unchanged ¥45.00 payout, they were working with revenue closer to ¥1,355.1b and earnings of ¥24.5b by 2029. That is a more cautious LIXIL story. Use it as a reference point and compare several viewpoints.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your LIXIL research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for LIXIL. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate LIXIL's overall financial health at a glance.
Looking for more investment ideas beyond LIXIL?
If LIXIL has sharpened your focus on income, valuation and balance sheet strength, it can help to line it up against other opportunities using the Simply Wall St Screener.
- For investors who want income that aims to be both generous and resilient, scan companies we flag as potential 38 dividend fortresses to see which payers might better match your payout expectations.
- If capital preservation ranks high for you, filter for businesses with steadier risk profiles through our set of 21 resilient stocks with low risk scores and compare their track records with LIXIL.
- To broaden your watchlist with lesser known opportunities, search the 74 high quality undiscovered gems that combine stronger fundamentals with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com