


EN
Thermo Fisher Scientific (TMO) Taps Swiss Debt Markets, Is The Stock Still 10% Undervalued?
Thermo Fisher Scientific fixed income moves
Thermo Fisher Scientific (TMO) recently tapped the Swiss franc debt markets, closing CHF 170 million in 1.4650% bonds due 2032 and CHF 110 million in fixed-to-floating rate notes maturing 2038.
Thermo Fisher Scientific’s latest bond deals come after a busy stretch that included a new US$5b share repurchase plan, a quarterly dividend of US$0.47 per share and fresh qPCR product launches. The 90 day share price return of 13.96% and 1 year total shareholder return of 20.03% indicate momentum that has eased slightly in the last week but remains stronger over longer periods.
Scan Thermo Fisher Scientific alongside hand-picked peers by tracking capital allocation and balance sheet strength with the list of solid balance sheet and fundamentals (24 results).
Thermo Fisher Scientific now trades about 10% below the average analyst price target, even as the shares have cooled over the last week. Is that discount reflecting opportunity, or caution that the recent rally has not fully resolved?
Most Popular Narrative: 9.9% Undervalued
On the narrative fair value of $750.92, Thermo Fisher Scientific trades below that mark at a last close of $676.94. As a result, the current pricing gap rests on whether you agree with the earnings and margin path analysts have mapped out.
Ongoing portfolio-deepening M&A, including the recent Clario and Solventum filtration deals that are tracking ahead of initial assumptions and are expected to contribute about 1.6b of revenue and about US$0.32 of adjusted EPS in 2026, together with the divestiture of the microbiology business, is set to tilt the mix toward higher value segments and support earnings and margin expansion.
See why 97 investors see Thermo Fisher Scientific as 10% undervalued.
Result: Fair Value of $750.92 (UNDERVALUED)
Still, weaker recovery from academic and government customers, or a slower payoff from the microbiology divestiture, could challenge Thermo Fisher Scientific’s upbeat narrative.
Find out about the key risks to this Thermo Fisher Scientific narrative.
Another View: What Thermo Fisher Scientific’s P/E Is Telling You
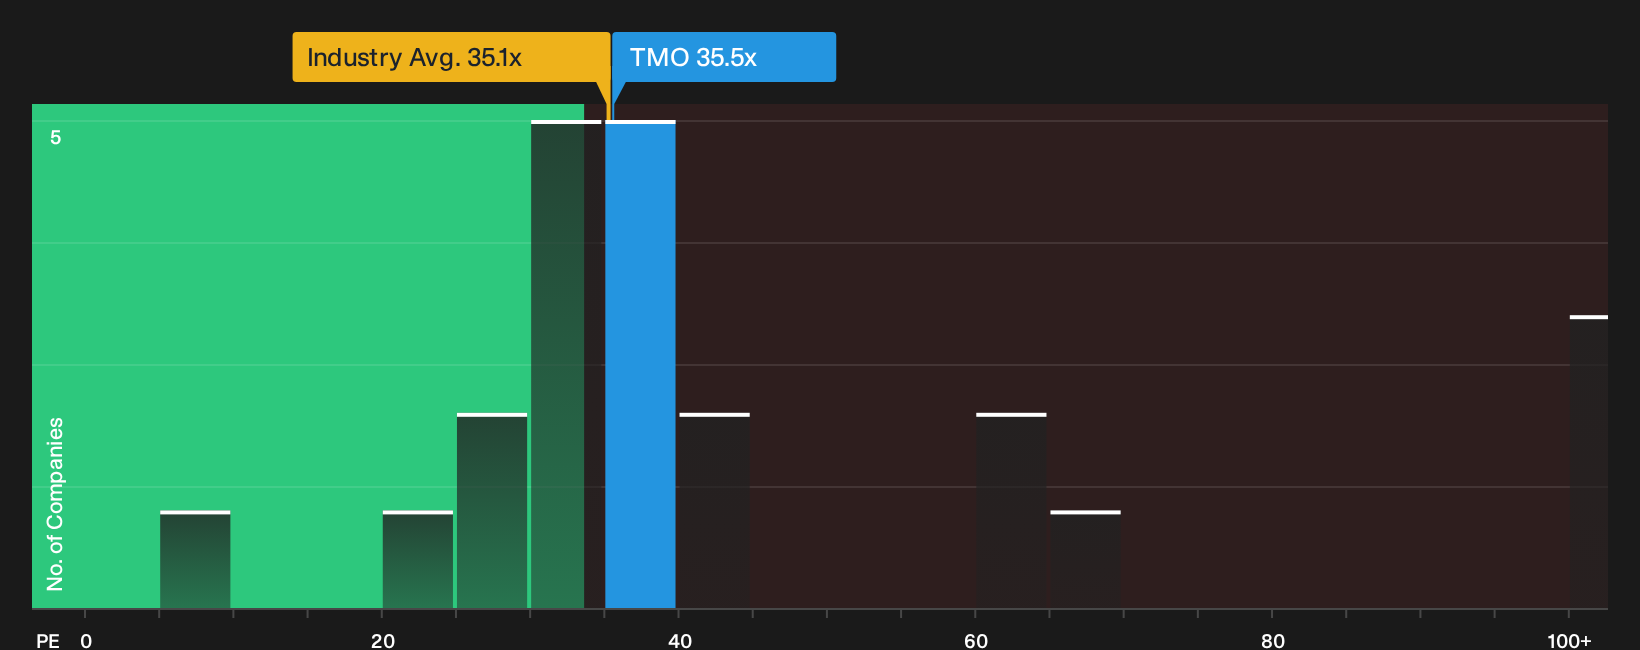
The narrative fair value suggests Thermo Fisher Scientific is 9.9% undervalued, yet the current P/E of 35.5x is slightly higher than both peers at 34.3x and the global life sciences average at 35.1x. At the same time, the fair ratio of 37.4x points to only a narrow valuation cushion if sentiment turns.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Thermo Fisher Scientific’s value case make this a moment to look directly at the numbers and consider potential actions before sentiment shifts again. To weigh the upside against the red flags yourself, start with the 1 key reward and 2 important warning signs.
Looking for more Thermo Fisher Scientific investment ideas?
If Thermo Fisher Scientific has you thinking about what else might be worth your attention, do not stop here. Broader context sharpens judgment and helps you spot what others overlook.
Use the Simply Wall Street Screener to compare different opportunities side by side and pressure test your investment watchlist against fresh ideas.
- Target steadier potential outcomes by reviewing a 32 resilient stocks with low risk scores that filters for businesses with resilient profiles and fewer financial shocks.
- Hunt for quality on sale by scanning a 42 high quality undervalued stocks that blends strong fundamentals with pricing that sits below intrinsic worth estimates.
- Seek future market favourites early by checking a 21 high quality undiscovered gems built to surface under-the-radar companies with solid underlying numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com